Which Day Makes the Weekly High? 30 Futures and 23,666 Weeks
Updated October 12, 2026
The rule everyone repeats#
It gets passed around as a working rule: the week's high or low is made on Monday or Friday, hardly ever mid-week. Whole plans are built on it, from waiting for Tuesday to look for the extreme to fading strong Fridays.
We measured it across the thirty contracts we cover, 23,666 complete weeks of index futures, metals, energy, grains, currencies, rates and crypto. Each week counts once: the day its high landed and the day its low landed.
The rule holds. And still, almost everything it says is noise. Both are true at once, and the gap between them is the reason for this study.
The split across thirty contracts#
The weekly high lands on Monday 26.9% of the time and on Friday 28.7%. Tuesday 14.4%, Wednesday 13.6%, Thursday 16.3%. More than half of all weeks make their high on one of the two edges.
The low splits almost the same way: Monday 28.8%, Friday 26.4%, and between 13.4% and 16.0% for the three days in the middle.
If the benchmark were 20% a day, which is what feels natural with five days, this would be a huge finding: Monday and Friday would sit about a third above expectations. But that benchmark is wrong.
Which day makes the weekly high
30 contratos, 7 familias
Swipe to see the sample →
| Day | All 30 contracts | Index futures | Chance | Weeks |
|---|---|---|---|---|
| Monday | 26.9% | 21.8% | 29.5% | 23,666 |
| Tuesday | 14.4% | 14.9% | 14.1% | 23,666 |
| Wednesday | 13.6% | 13.0% | 12.8% | 23,666 |
| Thursday | 16.3% | 16.0% | 14.1% | 23,666 |
| Friday | 28.7% | 34.4% | 29.5% | 23,666 |
n = 23,666 · 2010-06-07 to 2026-10-09 · historical futures data
Each week counts once: the day with the week's most extreme high (or low), Monday to Friday. The chance column is a trendless random walk over five equal days (the arcsine law): it is not 20% a day, because an extreme lands more often near the start or the end of the interval. Measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET); holidays shorten some weeks. Version of 12-Oct-2026, with data to 9-Oct-2026: SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
Chance does not split it 20% a day either#
A price that moves at random, with no trend, does not spread its extremes evenly over time. It pushes them to the edges. This is a classic result in probability, the arcsine law: in a random walk, the highest point of an interval lands far more often near its start or its end than in the middle.
Applied to five equal days, chance puts the extreme on the first day 29.5% of the time, on the second 14.1%, the third 12.8%, the fourth 14.1% and the last 29.5%.
Compare that with the table. The thirty contracts give 26.9%, 14.4%, 13.6%, 16.3% and 28.7%. It is nearly the same picture, with the edges even slightly below chance.
Put plainly: the weekly extreme landing on Monday or Friday is not a property of the market. It is what a coin would do. A rule that describes chance gives nobody an edge.
Where there is something: the index futures#
In the five index futures the split tilts. The high lands on Friday in 34.4% of weeks and on Monday in only 21.8%. The low goes the other way: 33.6% on Monday and 24.5% on Friday.
In ES it is sharper: the high on Friday 37.7%, on Monday 20.3%. The low on Monday 32.9%. Nasdaq behaves the same, with the high on Friday 37.3% and the low on Monday 34.6%.
The simplest explanation is trend. Between 2010 and 2026 US equity indices rose a lot. In a week that rises, the low tends to come early and the high late, and a market with upward drift piles up more of those weeks. Chance with a trend is no longer symmetric, and that is exactly what the table shows.
The difference is not small for a sample this size. With 853 weeks, a proportion near 30% carries an error of barely a point and a half; the ES Friday sits more than eight points away from chance.
Which day makes the weekly low
30 contratos, 7 familias
Swipe to see the sample →
| Day | All 30 contracts | Index futures | Chance | Weeks |
|---|---|---|---|---|
| Monday | 28.8% | 33.6% | 29.5% | 23,666 |
| Tuesday | 15.4% | 15.5% | 14.1% | 23,666 |
| Wednesday | 13.4% | 11.1% | 12.8% | 23,666 |
| Thursday | 16.0% | 15.3% | 14.1% | 23,666 |
| Friday | 26.4% | 24.5% | 29.5% | 23,666 |
n = 23,666 · 2010-06-07 to 2026-10-09 · historical futures data
Each week counts once: the day with the week's most extreme high (or low), Monday to Friday. The chance column is a trendless random walk over five equal days (the arcsine law): it is not 20% a day, because an extreme lands more often near the start or the end of the interval. Measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET); holidays shorten some weeks. Version of 12-Oct-2026, with data to 9-Oct-2026: SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
Contract by contract#
In metals, energy, grains, currencies and interest rates there are 92 key percentages (high and low on Monday and on Friday for 23 contracts), and 82 fall between 22% and 31%, around chance's 29.5% and with no clear direction. Of the ten that fall outside, the highest is palladium's low on Monday, 33.1%, and two belong to three-month SOFR (SR3), which has the shortest sample in the group, 249 weeks: high on Monday 32.5% and low on Monday 21.7%. The Canadian dollar makes its low on Friday in 31.3% of weeks; the yen in 30.2%. Those are deviations of less than two points, the size of noise.
Index futures are the only group where the pattern repeats in all five contracts at once: every one makes its high more often on Friday than on Monday and its low more often on Monday than on Friday.
Crypto needs a separate reading. Bitcoin and ether make their low on Monday in 36.1% and 35.8% of weeks, but here the week runs Monday to Friday even though their underlying trades at the weekend. That Monday absorbs Saturday's and Sunday's move, so the comparison is not the same as for the rest.
Weekly high and low on Monday and Friday, contract by contract
Los 30 contratos medidos
Swipe to see the sample →
| Contract | High Mon | High Fri | Low Mon | Low Fri | Weeks |
|---|---|---|---|---|---|
| ES | 20.3% | 37.7% | 32.9% | 23.8% | 853 |
| NQ | 19.0% | 37.3% | 34.6% | 23.2% | 853 |
| RTY | 23.8% | 29.8% | 30.6% | 26.5% | 483 |
| YM | 22.7% | 35.1% | 32.0% | 25.3% | 853 |
| NKD | 23.9% | 29.9% | 36.6% | 24.5% | 853 |
| GC | 25.4% | 29.4% | 31.3% | 23.8% | 853 |
| SI | 27.2% | 28.4% | 28.8% | 25.7% | 853 |
| HG | 31.1% | 29.9% | 31.3% | 23.1% | 853 |
| PL | 30.5% | 25.6% | 29.1% | 27.4% | 853 |
| PA | 30.2% | 27.9% | 33.1% | 21.6% | 853 |
| CL | 28.8% | 26.6% | 31.7% | 22.4% | 853 |
| NG | 28.5% | 23.0% | 31.5% | 29.1% | 853 |
| ZC | 27.7% | 27.5% | 27.5% | 25.1% | 853 |
| ZW | 28.0% | 25.4% | 24.5% | 27.2% | 853 |
| ZS | 27.8% | 27.2% | 25.3% | 27.1% | 853 |
| 6E | 26.1% | 28.4% | 26.0% | 30.1% | 853 |
| 6J | 30.6% | 26.6% | 22.6% | 30.2% | 853 |
| 6B | 25.9% | 28.6% | 26.7% | 29.1% | 853 |
| 6A | 24.3% | 26.7% | 25.7% | 28.3% | 853 |
| 6C | 26.1% | 27.0% | 24.6% | 31.3% | 853 |
| 6S | 28.1% | 30.5% | 25.7% | 28.1% | 853 |
| 6N | 24.9% | 27.2% | 25.6% | 28.5% | 853 |
| 6M | 28.1% | 30.6% | 27.9% | 26.5% | 853 |
| ZT | 30.0% | 27.3% | 26.8% | 28.1% | 853 |
| ZF | 26.1% | 29.4% | 25.2% | 28.4% | 853 |
| ZN | 26.7% | 28.1% | 27.2% | 26.4% | 853 |
| ZB | 27.4% | 27.9% | 28.6% | 25.6% | 853 |
| SR3 | 32.5% | 24.5% | 21.7% | 28.1% | 249 |
| BTC | 30.4% | 26.3% | 36.1% | 22.8% | 460 |
| ETH | 34.5% | 26.7% | 35.8% | 22.0% | 296 |
n = 23,666 · 2010-06-07 to 2026-10-09 · historical futures data
Each week counts once: the day with the week's most extreme high (or low), Monday to Friday. Chance (a trendless random walk over five equal days) puts 29.5% on Monday and 29.5% on Friday. Measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET); holidays shorten some weeks. Ordered by family: index futures, metals, energy, grains, currencies, rates and crypto. Version of 12-Oct-2026, with data to 9-Oct-2026: SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
What this study does not say#
It does not say what time of day the extreme lands, or how far it sits from the previous week's. It only counts which day it fell on.
It does not separate holiday weeks. A four-day week shifts the split toward the middle, and US contracts have a few every year.
It does not say the index trend will continue. The tilt in the table belongs to sixteen specific years of a bull market; in a bear period the picture would flip.
And it is not a signal. Knowing that the ES high lands on Friday in 37.7% of weeks means that 62.3% of the time it lands on another day.
October 2026 correction: the three weekly tables were recomputed with data through October 9, 2026, with the pre-2016 currency data cleaned, the day defined as the exchange trading day (18:00 ET the previous evening to 17:00 ET) and a few contract series rebuilt. The figures for all contracts together and for the index futures moved by less than one point; contract by contract, the largest change was 1.6 points, leaving aside three-month SOFR (SR3), whose earlier row was not valid and which is now measured since 2022.
Friday above the week's midpoint: an 82% that is arithmetic#
Another often-repeated calendar rule: if Friday opens above the midpoint of the Monday-to-Thursday range, the week closes higher. Measured on the four U.S. index futures (ES, NQ, RTY and YM), regular session, Fridays from 2010-06-18 to 2026-10-09, it holds 82.1% of the time, over 1,680 cases. Each week counts once per index.
It sounds like an edge and it is not. The figure is high because the condition already contains almost the whole week: 84.4% of the Fridays that open above the midpoint already open above Monday's open, and Friday has only one session left to undo it.
The control checks it. Each Friday's open and Monday's open are kept, and Friday's move is swapped for that of any other Friday of the same year and the same index. The result is 81.2%. The real Friday adds nothing.
What somebody could actually trade is Friday itself, and there is nothing there: it closed above its open 54.8% of the time when it opened above the midpoint and 52.7% when it opened below. The difference is 2.1 points, with a 95% confidence interval of -3.4 to +7.7, which includes zero. All Fridays together, 54.0%, over 2,806.
Friday opens above the midpoint of the week's range: what does it say about Friday, and about the week?
ES, NQ, RTY, YM
Swipe to see the sample →
| Friday's open | Friday closes above its open | The week closes above Monday's open | Weeks |
|---|---|---|---|
| Friday opens above the midpoint of the Monday-Thursday range | 54.8% | 82.1% | 1,680 |
| Friday opens below that midpoint | 52.7% | 20.7% | 1,122 |
| All Fridays | 54.0% | 57.5% | 2,806 |
| Control: Friday above the midpoint, with Friday's own move shuffled | -- | 81.2% | 1,680 |
n = 2,806 · 2010-06-18 to 2026-10-09 · historical futures data
Regular session (9:30-16:00 ET) of the four US index futures, Fridays from 18-Jun-2010 to 9-Oct-2026 (RTY from 14-Jul-2017). Weeks count when they have a Friday session and at least three sessions from Monday to Thursday, all in the same contract. Range = high and low of the regular sessions from Monday to Thursday; the condition is read at Friday's 9:30 ET open. 'Monday's open' = the 9:30 ET open of the first session of the week. Each week counts once per index: 'Weeks' adds up the four (ES 784, NQ 786, RTY 454, YM 782; 794 distinct calendar weeks). First column: the difference between opening above the midpoint and opening below it is +2.1 points [−3.4 to +7.7] with a 95% confidence interval (resampling whole weeks); with Fridays since 2022 only, +3.7 points [−5.7 to +12.7] (n = 968). The interval includes zero: opening above the midpoint does not say which way Friday will close. Second column: the figure is high because the condition already contains almost all of the week's move, not because Friday adds information. 84.4% of the Fridays that open above the midpoint already open above Monday's open, and Friday has only one session left to undo it. The control row checks this: it keeps each Friday's open and Monday's open, and swaps Friday's move (from its open to its close) for that of another Friday of the same year and the same index, picked at random (mean of 1,000 draws; 95% of them fall between 79.9 and 82.4%). The figure comes out practically the same. Since 2022: 82.6% observed and 81.1% shuffled. This is what happened, not a signal.
What to do with this when preparing the week#
Distrust the Monday-or-Friday rule when it arrives without its benchmark. Against 20% it impresses; against chance's 29.5% it says almost nothing outside the index futures.
If you trade index futures, the tilt is real and has a cause: in bull-market weeks the low comes early and the high comes late. Use it as context, not as a rule, and remember it depends on the underlying trend.
And in general: before you believe a calendar pattern, ask what chance would do in the same place. Often the answer is "the same thing".
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Which day of the week makes the weekly high?
- Across 30 futures, Friday (28.7%) and Monday (26.9%) account for more than half of all weeks. In index futures Friday weighs more: 34.4%, and 37.7% in ES.
- And the weekly low?
- Monday 28.8% and Friday 26.4% across the 30 contracts. In index futures the low comes earlier: 33.6% on Monday and 24.5% on Friday.
- Why is it not 20% a day?
- Because chance does not spread extremes evenly. In a random walk the highest point lands more often near the edges of the interval (the arcsine law): over five days, 29.5% on the first and another 29.5% on the last.
- So is the Monday-and-Friday pattern noise?
- In most markets, yes: metals, energy, grains, currencies and rates stay close to what chance would give. The exception is the index futures, where the 2010-2026 uptrend tilts the high toward Friday and the low toward Monday.
- Can I trade the Friday high?
- The table does not support that on its own. Even in ES, the high lands on another day in 62.3% of weeks, and the tilt depends on the market staying in an uptrend. It is context for preparing the week, not a signal.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
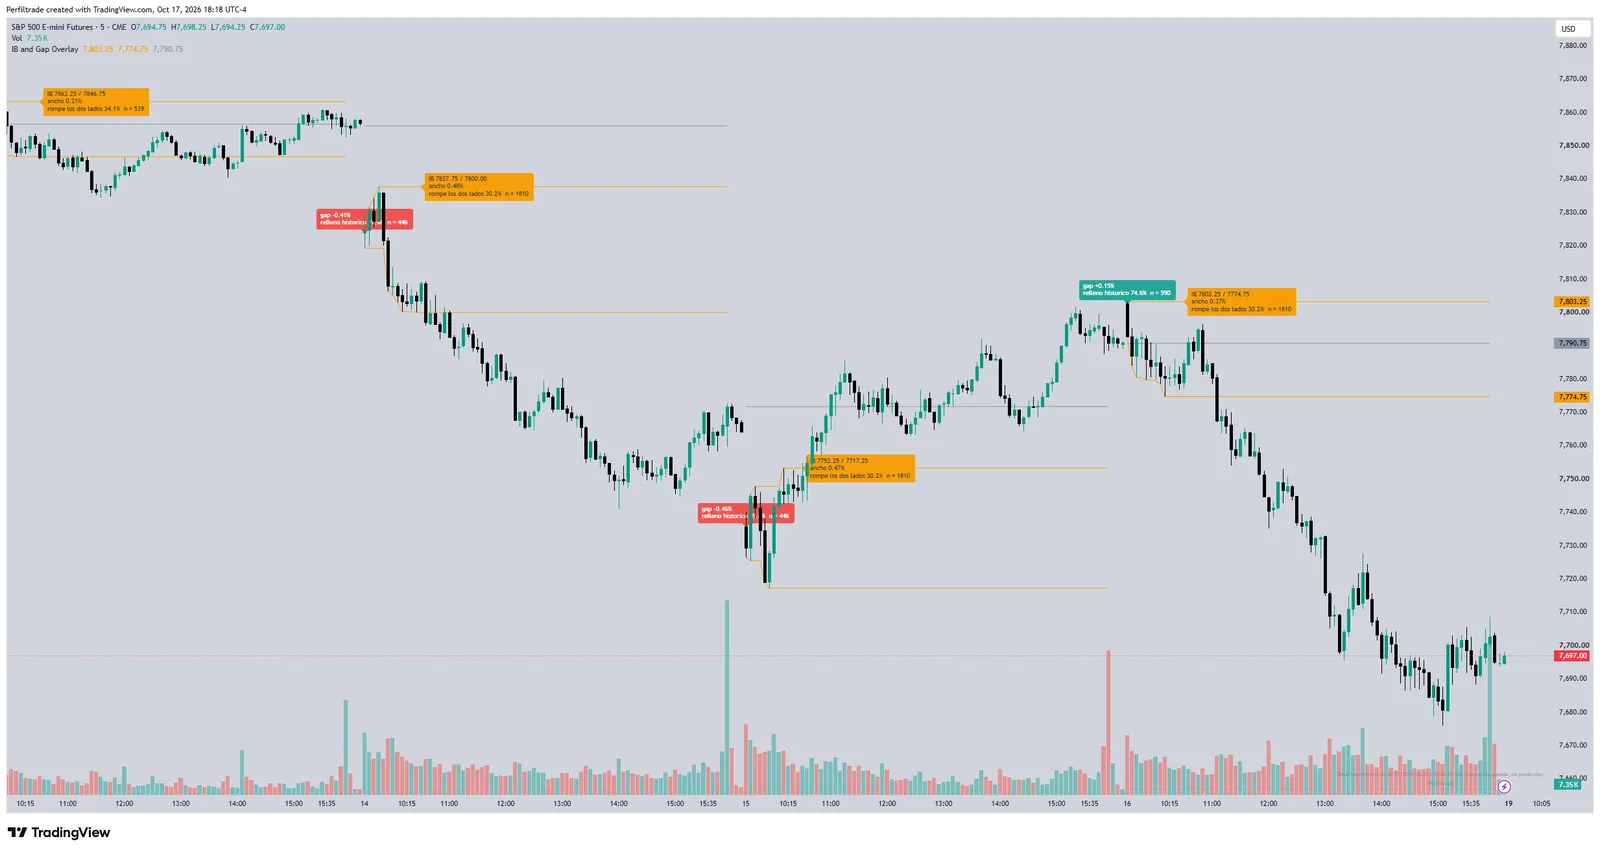
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). Which Day Makes the Weekly High? 30 Futures and 23,666 Weeks. https://www.perfiltrade.com/en/learn/weekly-high-low-day-of-week-thirty-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →