Before the open, you already know how much today tends to move and which scheduled release makes it bigger
Futures statistics measured over 16 years across 30 markets. Every figure with its sample, its control and its limits. No signals and no promises: we also publish what we measured and did not work.
For traders of US futures (indices, metals, energy, Treasuries or currencies) with their own or a funded account.
14 days with everything; then Free, with no end date. No card.
How it works →The sentence of the day · ES
Session of 11/2: ES usually moves about 74 points, more than a normal day (63). First session of the month (ISM manufacturing): the range is usually 1.14× the normal one.
Regular session, 70% band: 49 to 112 points. Out of sample, that band held the actual range 69.4% of the time (n = 2,791 sessions).
data through Fri, Oct 30 · delayed: updated every night
42
reports: 18 core and 24 in the archive
30
instruments with reports, 25 in the in-session screener
16+
years of history on most instruments
8
of our own tests that did not deliver what was expected, published with their control
what is already inside
What you get from day one
Your funded accounts
Rules of 20 firms with source and review date; distance to each limit in multiples of your worst real day.
see how it works →Alerts by Telegram or webhook
3 on Free, 20 on Trader, 100 on Pro. Each condition says how often it happened before, with its n.
see how it works →13 free TradingView indicators
Every percentage with its n, and “same as chance” when it does not beat the noise.
see how it works →Your figures inside your AI assistant
MCP connection with 14 read-only tools, plus a public API.
see how it works →Journal with imports
Upload your platform's file or connect a webhook, and each trade is logged with your state and whether you followed your plan.
see how it works →In Spanish, English and Portuguese
Same figure, same sample, same method in all three.
portal screenshots
What it looks like inside
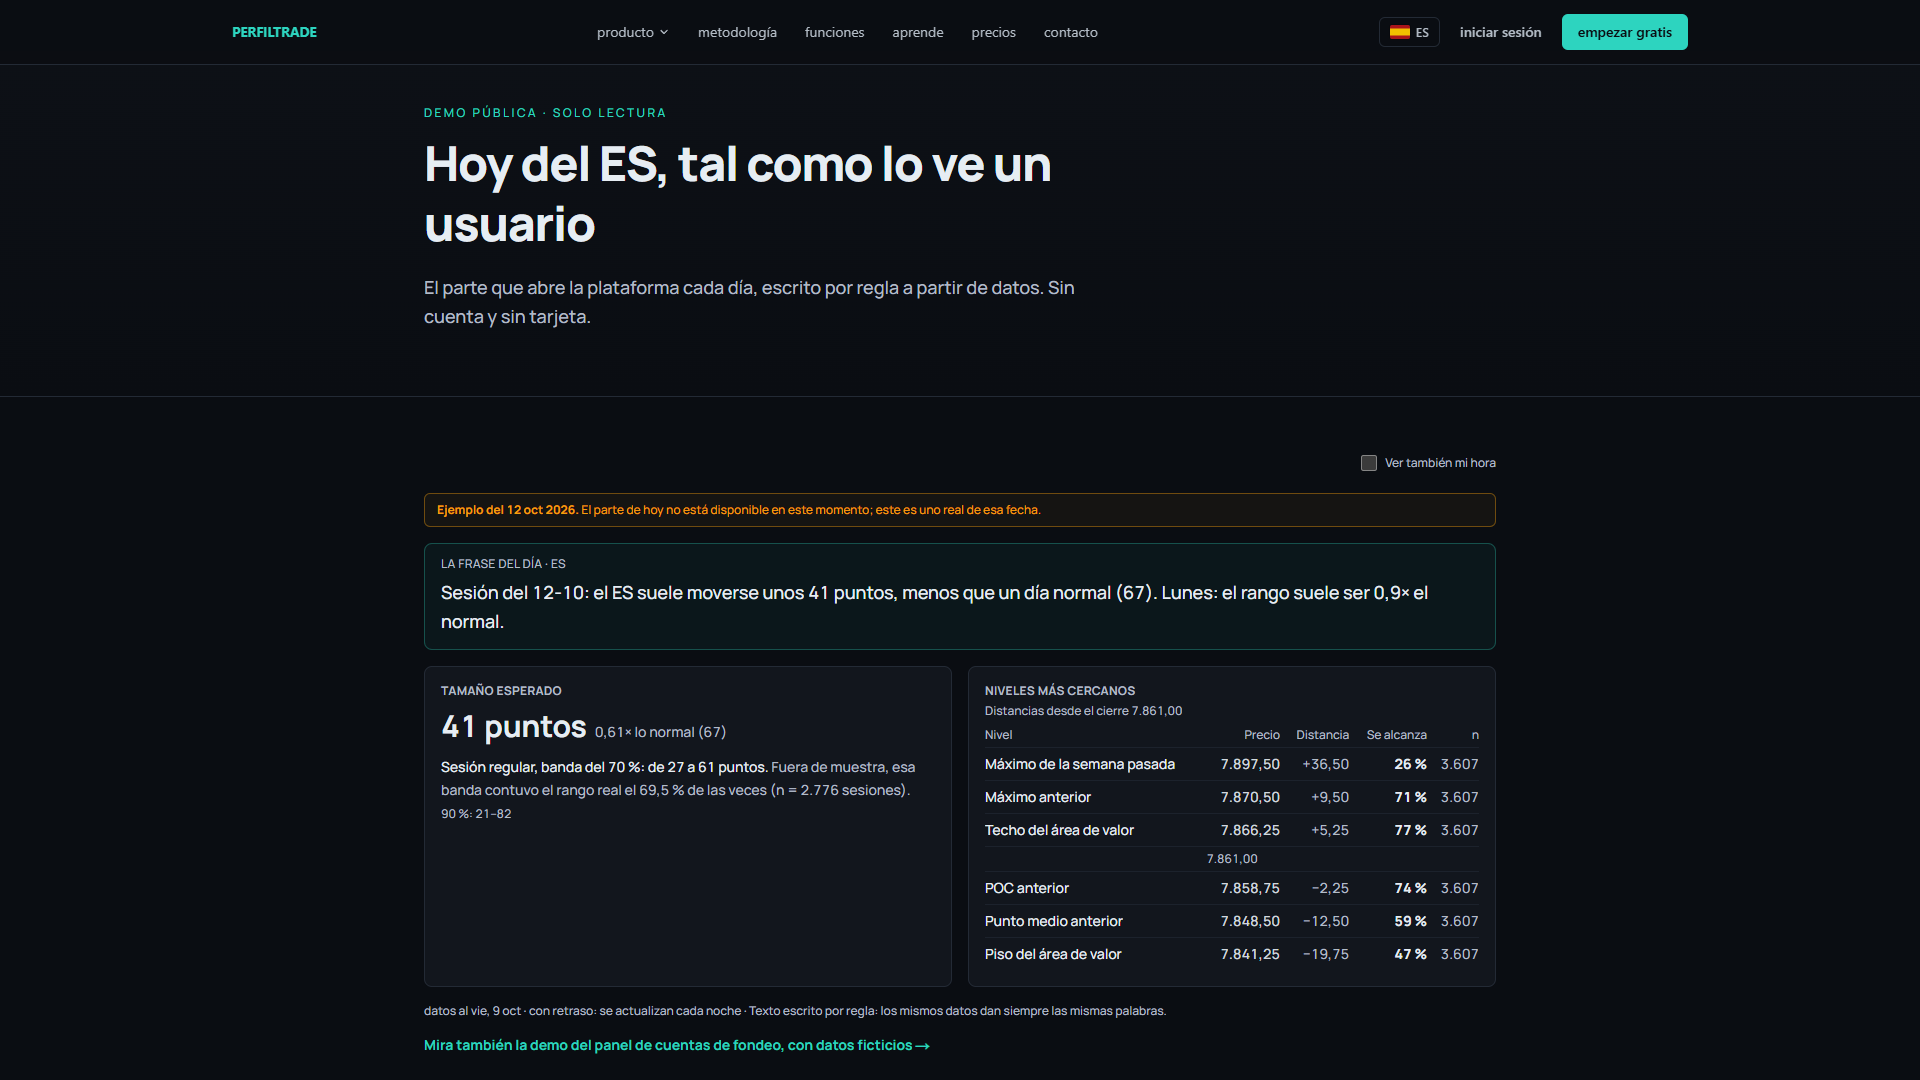
Today: the session's expected size, with its band and n 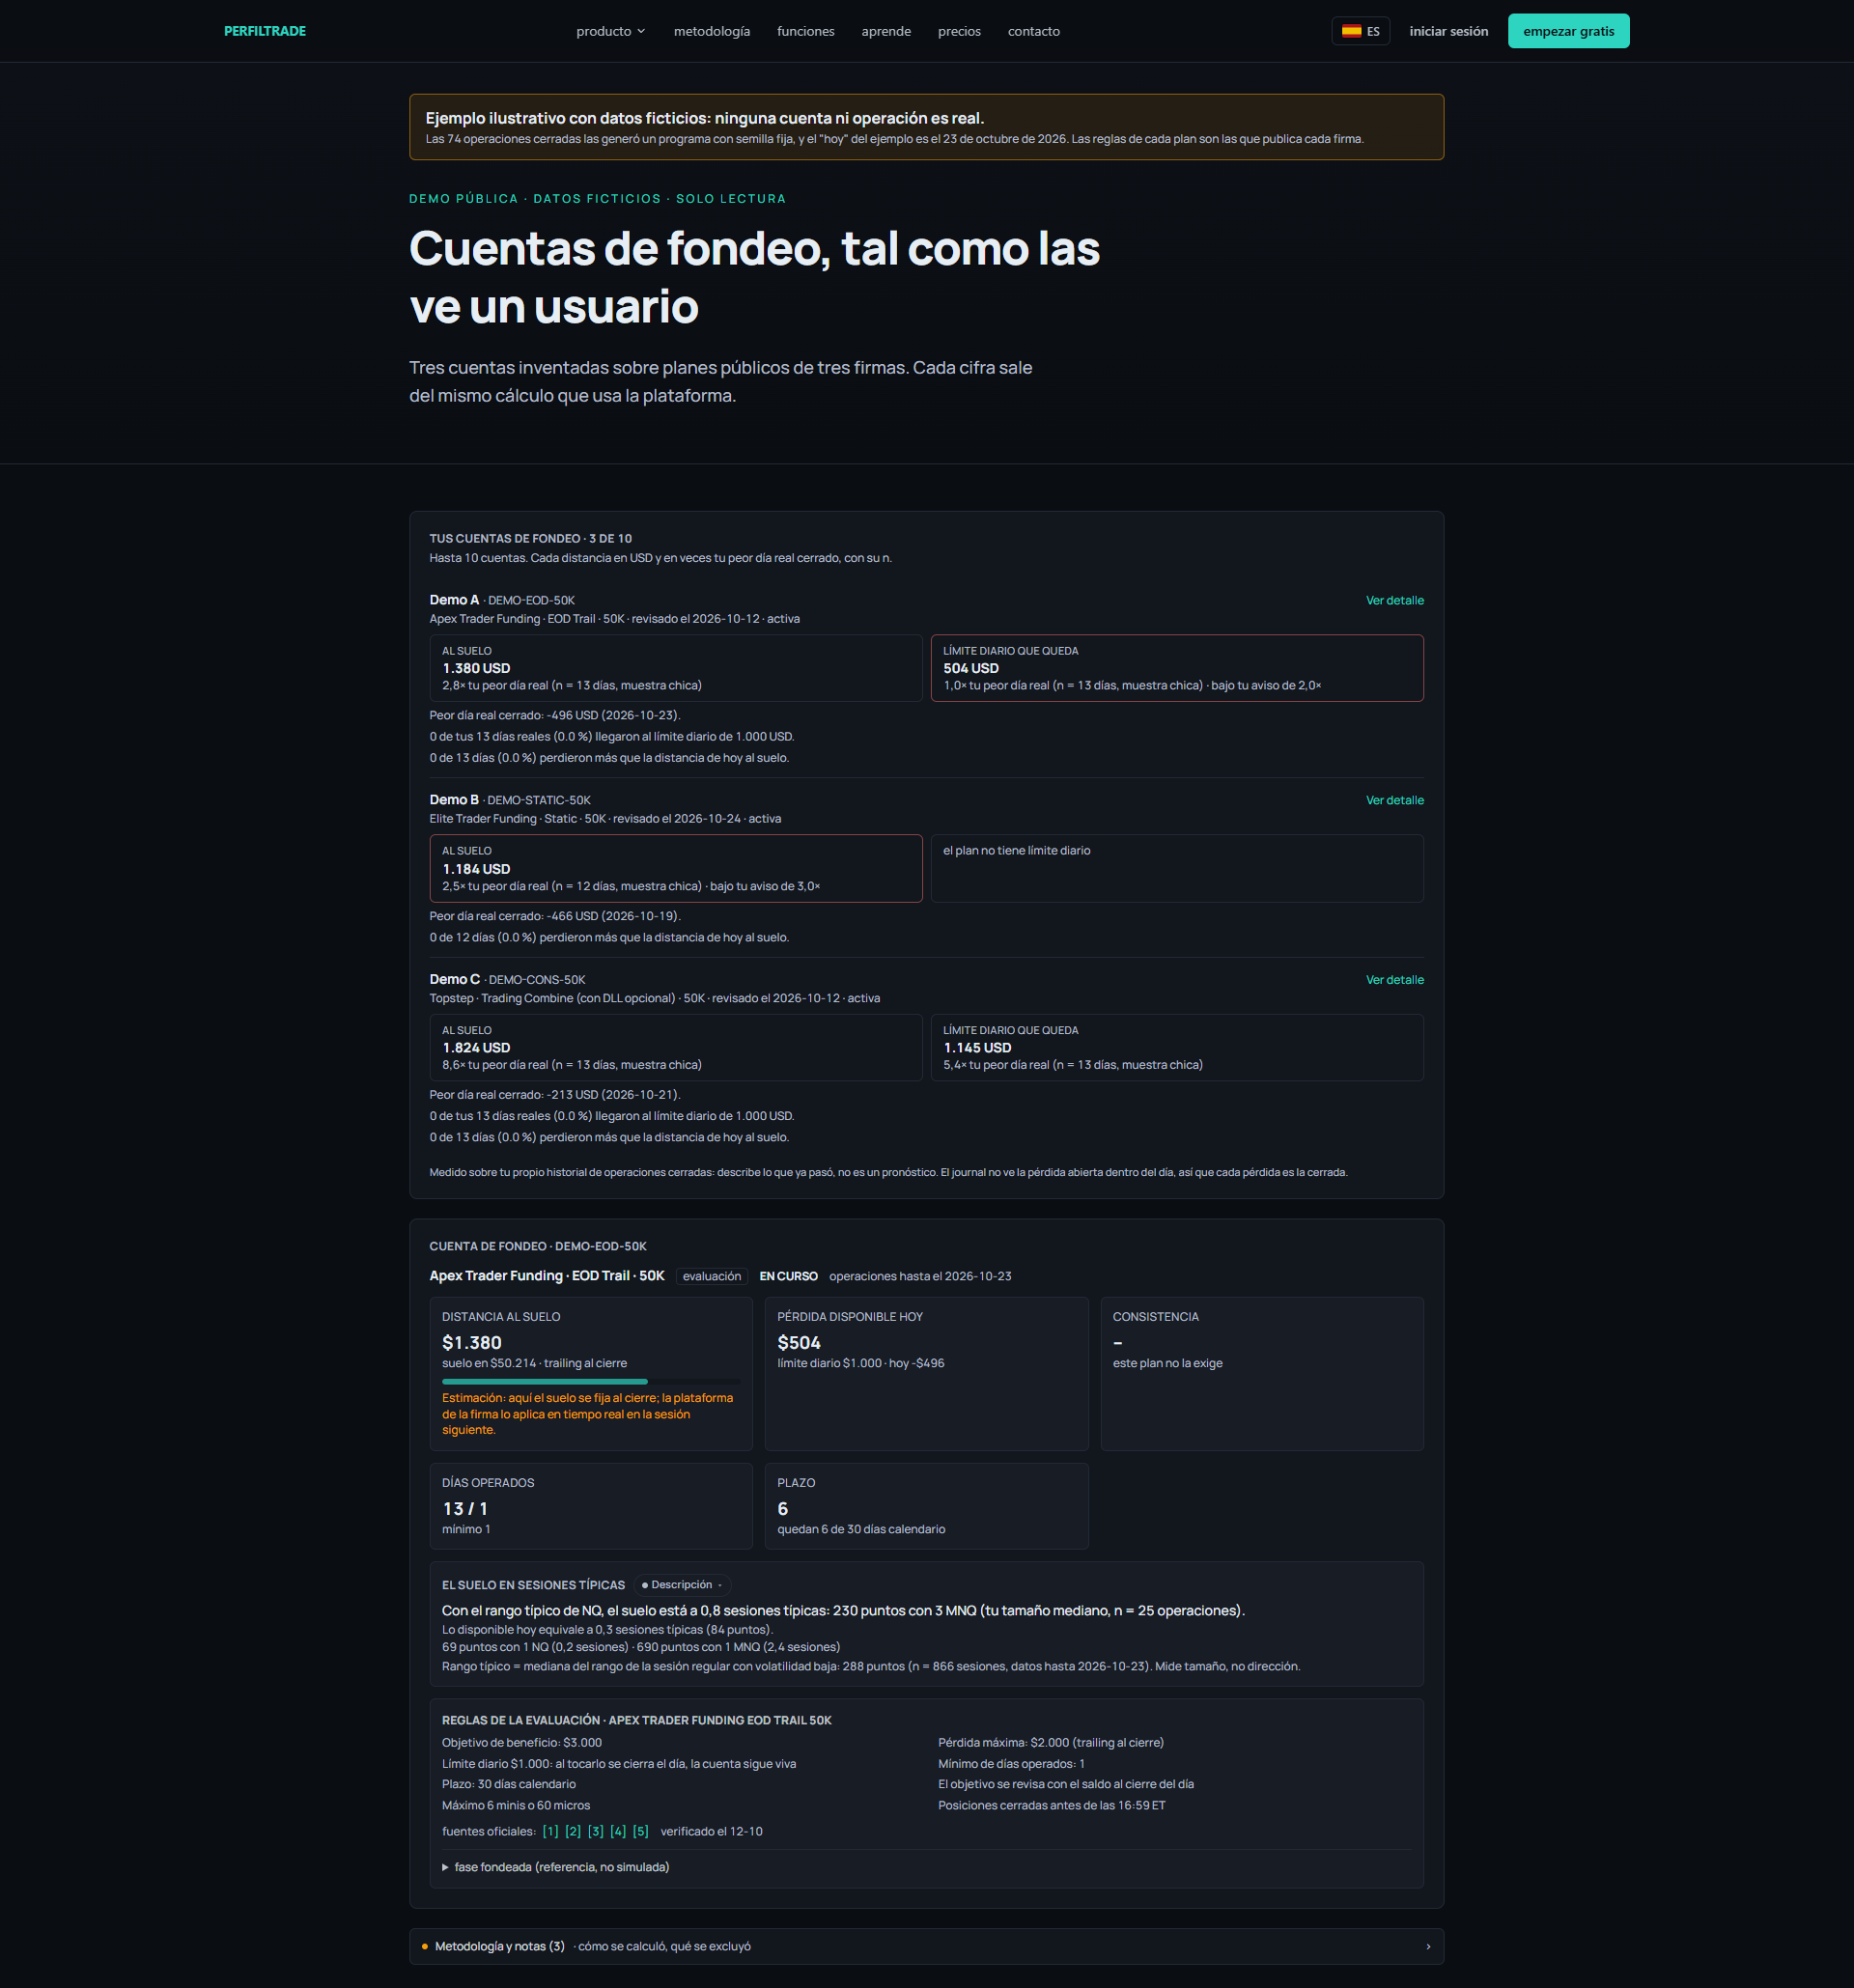
Funded accounts: distance to each limit, in multiples of your worst real day 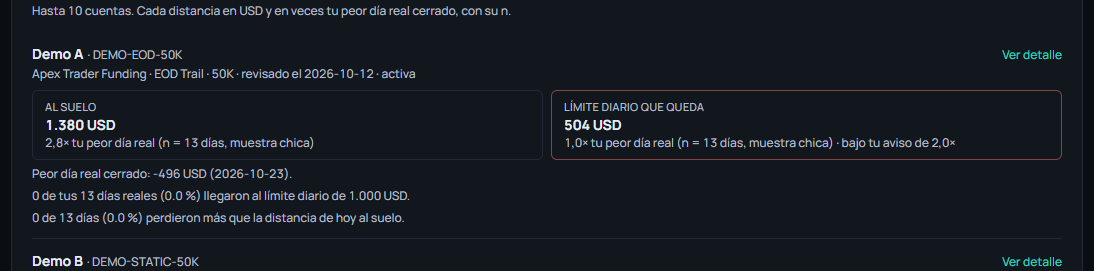
A Telegram alert: the condition, the time and how often it happened before
Screenshots from a test account, with made-up data.
funded accounts
Your funded accounts, on one screen
Load your firm's plan and see how much room is left to the daily limit and to the floor, in multiples of your worst real day and in typical sessions of your market. Rules for 20 firms, with source and review date. It is your own data: it does not say what to trade.
see how it works →the product, not the promise
Every report, with its sample in plain view
This is what a real report looks like: bucket, sample size, and the caveat that explains its limits -- always visible, never buried in fine print.
explore reports →NQ Initial Balance: breaks by IB size
Jun 7, 2010 to Oct 9, 2026 · n = 4,200 sessions
| IB size | Sessions | Breaks one side | Breaks both | Neither |
|---|---|---|---|---|
| 0–0.25 % | 124 | 75.0 % | 21.0 % | 4.0 % |
| 0.25–0.5 % | 1,069 | 67.3 % | 29.6 % | 3.2 % |
| 0.5–0.75 % | 1,228 | 74.6 % | 21.7 % | 3.7 % |
| 0.75–1.0 % | 836 | 74.5 % | 19.7 % | 5.7 % |
| 1.0–1.5 % | 650 | 77.2 % | 17.7 % | 5.1 % |
| 1.5–2.0 % | 206 | 77.7 % | 16.5 % | 5.8 % |
| >2.0 % | 87 | 69.0 % | 18.4 % | 12.6 % |
Size = (IB high − IB low) / IB low. Each row adds up to 100%.
today's brief, for real
The ES sentence of the day
How much the session usually moves, its band with how often it held, and the next timed release. A rule writes it, not an opinion.
see the full demo →The sentence of the day · ES
Session of 11/2: ES usually moves about 74 points, more than a normal day (63). First session of the month (ISM manufacturing): the range is usually 1.14× the normal one.
Regular session, 70% band: 49 to 112 points. Out of sample, that band held the actual range 69.4% of the time (n = 2,791 sessions).
Next timed release: Jobless claims, Thu 5 at 08:30 ET.
data through Fri, Oct 30 · delayed: updated every night
what we measured that did not work
We also publish the results that came out badly
Tests of our own features against what happened next, each with its control and its sample. In these, the result did not separate from its control or fell short of what it promised.
see all the results →What we measured that did not work
Seasonal windows that were “almost always positive”: positive in the following years
49.9 %·n = 1,489
Control: 49.7 % (any window of the same length)
Strategies that pass the robustness filter: profitable afterwards
38.3 %·n = 188
Control: 40.1 % (profitable without passing the filter)
POC of an earlier session: reached in the next session
23.1 %·n = 6,940
Control: 23.0 % (any price at the same distance)
The “80% rule”: reaches the opposite edge of value
61.4 %·n = 950
Control: 80 % (what its name promises)
Each row comes from a published table, with its scope and dates. Hypothetical results. A simulation on past data, not a real account. They do not guarantee future results.
see all the results →Market Profile
Initial Balance, Value Area, POC -- where the day's structure forms, during the session.
Reading the day
How much the session tends to move given the macro event and the context -- range size, not direction.
Historical statistics
Base rates over 16+ years of historical futures data -- every figure with its n and its caveats.
Positioning (COT) and liquidity
What large speculators are doing, plus real bid/ask spread -- the positioning and liquidity context.
The whole world of reports
Six entry points into the same data engine -- each one answers a different question.
Reports
18 core reports and 24 more in the archive -- gap, Initial Balance, opening range, macro events, open interest and spread where the data exists. Every number with its sample and limits in view.
see how it works →Ranking
First the reports that survive the false-positive control; then, by how far they sit from an ordinary day -- not a flat list.
see how it works →Lab
Reshuffles a setup's trades 1,000 times (Monte Carlo) to see whether the result depends on the order they happened in. Hypothetical results, not obtained in real trading.
see how it works →Setups
Session structure: Initial Balance, Value Area and POC, updated during the session (delayed by up to 15 minutes).
see how it works →COT
Large speculators vs. commercials positioning -- the CFTC weekly report, ready to read.
see how it works →Cerebro AI
Ask the platform directly about an instrument, a report or a setup.
see how it works →pricing
Start free and stay free. You pay only for more markets or for your funded accounts
You start with 14 days of everything, no card. Then you stay on Free with one market, 3 alerts and the calculator. Trader adds all 30 instruments and the full catalog; Pro adds the funded accounts, the Journal and the Lab.
$0
Free, with no end date
with 14 days of everything to start
$39
plan Trader /mo
$89
plan Pro /mo
everything included
14 tools to analyze, decide and review your process
Markets: price against the IB
FreeWhere price sits relative to the Initial Balance (above, below or inside), across 25 instruments.
Base-rate reports
Trader18 core reports and 24 more in the archive across 30 instruments, every figure with n, period and caveats.
Ranking
TraderRanking of patterns: first the ones that survive the false-discovery control.
In-session Market Profile
TraderInitial Balance, Value Area, POC and profile shape during the session, against their history.
COT positioning
TraderWeekly COT for 17 instruments with a 0-100 index and loaded positioning.
Correlations and reaction to data
TraderVIX/BTC correlations and the reaction to macro releases.
Week: a summary of what is coming
TraderWhat is coming this week in a paragraph written by rules, plus an optional AI report with its sources.
Cerebro AI
FreeAssistant that answers with platform data and cites the report, n and caveats. 5 questions a day on Free; 40 per hour on Trader and Pro.
Trading Journal
ProImport your trades from your platform's file or by webhook, and check whether your results differ from chance.
Funded accounts
FreeThe distance to each of your firm's limits, with your own history.
Alerts
FreeAlerts by Telegram or webhook, each with its historical frequency and its n.
API and MCP
TraderRead-only API and MCP: size, frequency and time, with n; never direction or prices.
Lab
ProMonte Carlo, chronological validation and funded-account simulation on setups.
Today, macro data, alerts and risk calculator
FreeToday, economic calendar, alerts and a risk calculator for 30 contracts.
We don't issue signals
We describe what happened and the current context. The decision to trade is yours.
We don't promise results
Past results do not guarantee future results, and trading futures involves risk of loss.
We don't hide the fine print
Every figure shows its sample, its period and its limits. If there isn't enough data, we say so.
no promises
What you will not find here
No entry or exit signals, no direction of the day, no promised returns, no trade win rates, no profit testimonials and no countdowns.
What you will
Every figure with its sample and, where there is one, its base rate or control. When a difference does not beat the noise, we call it the same as chance. And we publish 10 results of our own tests, including the ones that came out null or against what was expected, each with its table.
see our own results →instruments
One statistical report per instrument
Each page gathers a futures contract's own tables: how often something happens and out of how many sessions. Only instruments with enough sample to say something of their own are published.
See all instruments →TradingView
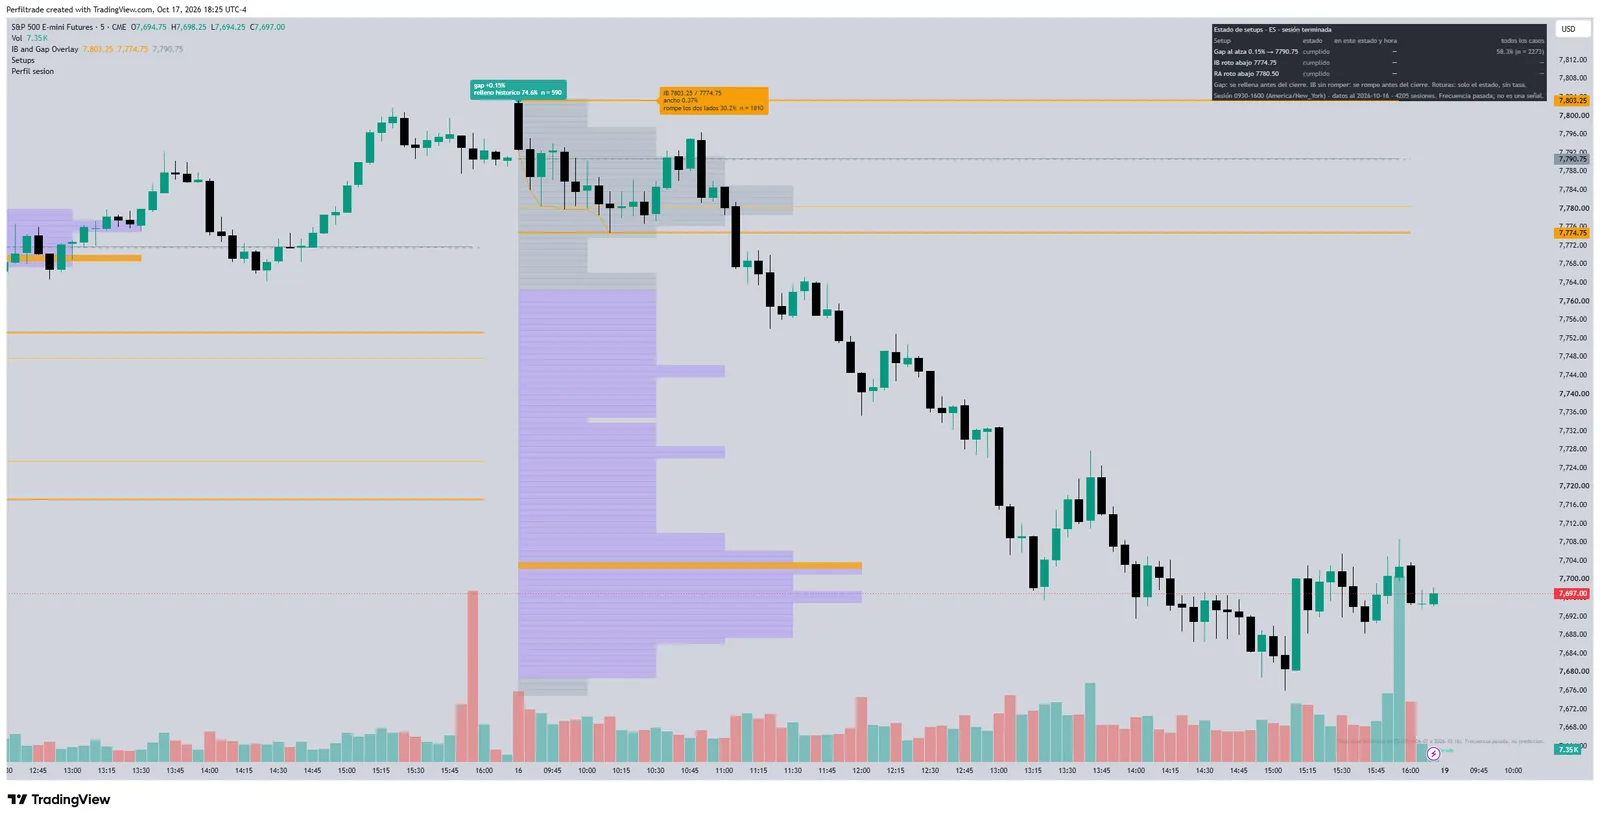
13 free indicators on your TradingView chart
Levels, profile, open type, VWAP and release days, every percentage with its n; when a difference does not beat the noise, the indicator says “same as chance”.
- IB and gap
- Key Levels
- Setup State
- Session Profile
- COT Positioning
- Volatility by Time of Day
- Open Type
- VWAP with Measured Bands
- Macro Release Days
- Prior Value Areas and POC
- Poor extremes and single prints
- Composite profile
- Overnight halfback
learn
Guides to Market Profile, COT and statistics
- Market Profile: What It Is and How to Read It in Futures
Market Profile in futures: TPO, POC, Value Area and Initial Balance explained with the real split of day types across 4,199 ES sessions.
- Initial Balance: What It Is and How to Use It Intraday
Initial Balance explained step by step: how the first-hour range is calculated and what 5,226 breaks and 4,182 ES sessions show about it.
- COT Report: How to Read Positioning in Futures
What the CFTC's COT report is, which participant groups it covers, why the data is from Tuesday but published on Friday, and the usual misreadings.
- VAH, VAL and POC: How to Read the Value Area in Futures
What VAH, VAL and POC mean and how the value area is read, using 4,188 prior-range breaks in ES to show what breaking yesterday's extreme really measures.
- Base Rates in Trading: What They Are and How to Read Them
What a base rate is, why sample size rules, what a degenerate cell is and how to check whether a historical statistic still holds.
- RTH vs Globex in Index Futures: What Changes
The difference between RTH and Globex in index futures: liquidity, hours and where the day's high and low really form.
- Open Interest in Futures: What It Is and How to Read It
What open interest is in futures, how it differs from volume, and how often each price and OI combination actually shows up in the ES.
- Opening Gap in Index Futures: A Data-Driven Guide
What the opening gap is in index futures, how it is measured against the prior regular close, and how often it fills in ES, NQ, RTY, YM and NKD.
- Position Sizing in Futures: How to Calculate It
How to calculate position size from risk per trade, stop distance and point value, with the average daily range of ES, NQ, RTY, YM and NKD.
- Best Day of the Week to Trade Futures
Best day of the week to trade futures: average daily range for ES, NQ, RTY, YM and NKD over 19,263 sessions, and why picking a day is no edge.
- What Time the High of the Day Is Made
What time the high of the day is made in ES, NQ, GC and ZN: how Asia, London and New York split the daily high over 4,000+ sessions per contract.
- ES vs NQ: The Differences, Measured
ES vs NQ compared with our own data: average range in points and in dollars, gap fill across 4,072 and 4,099 sessions, and the Initial Balance break.
- NQ Initial Balance Statistics
Initial Balance statistics for the E-mini Nasdaq-100: 4,929 breaks and 4,182 NQ sessions, plus the gap between breaking the high and the low.
- CME FX Futures Statistics: 6E, 6J, 6B, 6A
CME FX futures read as data: 15,963 previous-day range breaks and 16,035 sessions across 6E, 6J, 6B and 6A, each with its sample and date range.
- Gap Fill Statistics for Five Index Futures: 18,650 Sessions
The same opening gap measured the same way on ES, NQ, RTY, YM and NKD: by gap size, by weekday and on the weekly open. The Nikkei fills far less than the S&P, except over a weekend.
- Which Session Makes the Daily High and Low: 10 Futures, 39,937 Sessions
Where the daily extreme lands across five index futures, gold and the whole Treasury curve, checked against what chance would give. The stretch when London and New York overlap takes three or four times its share.
- Do Streaks Exist? Daily Continuation Across 30 Futures and 115,233 Sessions
After three or more days in the same direction, the next one goes the same way 48.1% of the time: the same as chance. Measured across 30 contracts in seven families, one definition, every sample size on the page.
- Breaking Yesterday's Range: the 70% Against Chance Across 30 Futures and 109,260 Breaks
The 70% of breaking yesterday's high is equal to chance: any level at the same distance above the open gives almost the same (70.4% against 69.8%, n = 55,574). It is explained by the distance the session already covered to reach the level, not by the level.
- Monday Has the Most Inside Days: 30 Futures and 109,806 Sessions
The session stays inside the prior day's range on 20.2% of Mondays and on 13.5% to 15.2% of the other days. The gap sits in interest rates and currencies; in energy and grains it does not appear.
- Which Day Makes the Weekly High? 30 Futures and 23,666 Weeks
The weekly high and low land mostly on Monday and Friday. That is exactly what chance produces. What chance does not produce is in the index futures: ES makes its weekly high on Friday in 37.7% of weeks.
- Monthly seasonality: almost no month departs from chance
Across 360 month-and-contract combinations, only 9 depart from what is normal for their own contract, fewer than the 15 that chance would give. Of thirteen classic calendar effects, only one, in Treasury futures, passes the false-discovery control.
- Which Futures Prop Firms Allow Bots (October 2026)
Firm by firm, what each allows for bots and automated trading in the evaluation, the funded account and the live account, with the official source for every rule. Checked on October 7, 2026.
- What the S&P 500 Does on Macro Data Days: CPI, Jobs and the Fed
How much bigger the first hour of ES gets with each release, over five years of releases, with its sample and its control. And what the data does not say.
- Event Hours: Treasury Auctions and the London Fix, Measured
What bond futures do around the 13:00 Treasury auctions and what currency futures do at the London fix: one pattern that disappeared and another that is about size, not direction.
- When to Roll: The Typical Roll Day in Futures
How many days before expiration volume moves to the next contract in ES, NQ, gold, crude oil, Treasuries and the euro, measured over the rolls of the last five years.
- What Time the Futures Market Opens in Your Country, and When It Changes
The S&P 500 regular session opens at 9:30 New York time. On your clock it moves up to three times a year depending on the country: the table for Spain, Mexico, Colombia, Peru, Chile, Argentina and Brazil, with its dates.
- The Prop Firm Consistency Rule: The Math and What Each Firm Requires
Best day divided by total profit: how the consistency rule is calculated in the evaluation, what it does and what percentage each of 20 futures prop firms sets, with sources. Rules checked in October 2026.