Position Sizing in Futures: How to Calculate It
Updated October 12, 2026
The calculation, in one line#
Position size is not chosen: it is calculated. The formula has four pieces and none is a matter of opinion. Contracts = (capital × risk percentage) ÷ (stop distance in points × the contract's point value).
The numerator is how much money you accept losing if the stop is hit. The denominator is what that loss costs with a single contract. The division tells you how many contracts fit within that limit.
The result is always rounded down. Never up. Rounding up means accepting more risk than you defined, which is exactly what the calculation existed to avoid.
The three inputs to set beforehand#
The first is risk capital. It is not your total net worth: it is the capital allocated to this activity. If that number is already larger than what you are willing to expose, the result will be too large from the very first step.
The second is the risk percentage per trade. There is no universally correct value and this article does not propose one. It is a personal decision that depends on capital, horizon and tolerance for losing streaks. The only objective part is the mechanics: the percentage multiplies the capital and sets the maximum money at stake.
The third is the stop distance, in instrument points. It is the one most people get wrong, because they choose it by looking at the size of their account instead of the market. A stop goes where the idea stops being valid, and that distance depends on how much that instrument moves.
The point value of each contract#
The point value converts movement into money. It is a public exchange specification, not an estimate. The ones used by the platform's risk calculator are taken from each contract's public specifications.
For the five indices with intraday reports: the E-mini S&P 500 (ES) is worth 50 USD per point, with a tick of 0.25 and 12.50 USD per tick. The E-mini Nasdaq-100 (NQ) is worth 20 USD per point, with a tick of 0.25 and 5.00 USD per tick. The E-mini Russell 2000 (RTY) is worth 50 USD per point, with a tick of 0.10 and 5.00 USD per tick. The E-mini Dow with a multiplier of 5 (YM) is worth 5 USD per point, with a tick of 1.00 and 5.00 USD per tick. The dollar-denominated Nikkei 225 (NKD) is worth 5 USD per point, with a tick of 5.00 and 25.00 USD per tick.
There is a one-line check: in every case the point value is the tick value divided by the tick size. It helps catch a miscopied figure before it ruins a calculation.
Micro contracts are a fixed fraction of these, usually one tenth, but they are not listed here as a verified specification. If you trade one, multiply by your contract's proportion and confirm the value on its official spec sheet.
Micro contracts are one tenth of the full-size contract, and that ratio is the only thing treated as verified here: MES is one tenth of ES and MNQ one tenth of NQ, so the point goes from $50 to $5 and from $20 to $2, and the tick from $12.50 to $1.25 and from $5.00 to $0.50. Before trading one, confirm the value on the contract's official page: the ratio is the norm, not a guarantee across every product.
The average range shapes the stop distance#
Before deciding on a stop it helps to know how far that market travels on a normal day. A stop that is roomy on one instrument is pure noise on another. The table shows the average daily true range, in index points, of those five instruments.
The difference between them is enormous and explains why there is no standard stop. The NQ travels several times the points of the ES on average. The NKD and the YM move in the hundreds of points because they trade at much higher price levels. Using the same number of points on all of them is a unit error.
A common-sense observation, not a recommendation: if the stop you need is a small fraction of the average daily range, normal noise during the day is likely to touch it. With the average since 2010, 43.7 points in the ES, a 10-point stop is already less than a quarter of that ordinary session; with today's range, in the next table, the share is smaller still.
Also look at each row's sample. Not all of them cover the same number of sessions: the RTY series is considerably shorter than the other four. Comparing instruments is not comparing exactly the same period.
Average true range by instrument, in points
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Average range | Quietest day | Busiest day | |
|---|---|---|---|---|
| ES | 43.7 pts | Tuesday 42.46 | Thursday 45.32 | 4,218 |
| NQ | 174.8 pts | Friday 169.44 | Thursday 181.88 | 4,218 |
| RTY | 39.6 pts | Monday 38.69 | Wednesday 40.69 | 2,388 |
| YM | 339.4 pts | Monday 332.67 | Thursday 350.03 | 4,222 |
| NKD | 451.1 pts | Monday 439.32 | Thursday 459.49 | 4,217 |
n = 19,263 · 2010-06-08 to 2026-09-16 · historical futures data
Average daily true range in index points, averaged over every session from 2010 to 2026. In points, that average depends mostly on the price level: ES closed at 1,049 in June 2010 and at 7,786 on 15 October 2026, so the ES average of 43.7 points sits far below what the market moves today and does not describe the size of a current day. How much each contract moves today, over its last 250 sessions and in dollars per standard contract and per micro, is in the table "How much each future moves today, in points and in dollars". It is what happened, not a signal.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
How much each future moves today, in points and dollars#
The average since 2010 is useful to compare markets, but it understates today's range: index prices have multiplied since then and the range in points grew with them. The next table uses only the last 250 complete sessions, from October 2025 to October 2026, and converts the range to dollars per standard contract and per micro.
In the ES, the typical day (the median) was 80.38 points: 4,019 USD per standard contract and 402 per MES; on three days out of four, less than 106.8 points. In the NQ, 466.6 points, 933 USD per MNQ. In crude oil, 3.33 USD per barrel, 333 USD per MCL. In gold, 97.95 USD per ounce, 979 USD per MGC.
It is an order of magnitude, not a target: a macro release day can easily go beyond the 75th percentile, and one day in four does so by definition. It is worth checking this table again every few months, because the window moves.
How much each future moves today, in points and in dollars
ES, NQ, RTY, YM, NKD, GC, SI, HG, CL, NG, 6E, 6J, 6B, 6A, 6C, 6S, ZN, ZB, BTC, ETH
Swipe to see the sample →
| Future | Micro | Median (pts) | 75th percentile (pts) | Median USD (standard) | P75 USD (standard) | Median USD (micro) | P75 USD (micro) | Sessions |
|---|---|---|---|---|---|---|---|---|
| ES | MES | 80.4 pts | 106.8 pts | 4,019 USD | 5,338 USD | 402 USD | 534 USD | 250 |
| NQ | MNQ | 466.6 pts | 629.2 pts | 9,332 USD | 12,585 USD | 933 USD | 1,258 USD | 250 |
| RTY | M2K | 47.9 pts | 63.4 pts | 2,392 USD | 3,171 USD | 239 USD | 317 USD | 250 |
| YM | MYM | 586.5 pts | 739.2 pts | 2,932 USD | 3,696 USD | 293 USD | 370 USD | 250 |
| NKD | -- | 1,462.0 pts | 1,984.0 pts | 7,312 USD | 9,919 USD | -- | -- | 250 |
| GC | MGC | 98.0 pts | 131.5 pts | 9,795 USD | 13,152 USD | 979 USD | 1,315 USD | 250 |
| SI | SIL | 3.11 pts | 4.92 pts | 15,562 USD | 24,581 USD | 3,112 USD | 4,916 USD | 250 |
| HG | MHG | 0.138 pts | 0.190 pts | 3,444 USD | 4,750 USD | 344 USD | 475 USD | 250 |
| CL | MCL | 3.33 pts | 5.55 pts | 3,330 USD | 5,547 USD | 333 USD | 555 USD | 250 |
| NG | MNG | 0.141 pts | 0.210 pts | 1,410 USD | 2,098 USD | 141 USD | 210 USD | 250 |
| 6E | M6E | 0.00553 pts | 0.00755 pts | 691 USD | 944 USD | 69 USD | 94 USD | 250 |
| 6J | MJY | 0.0000360 pts | 0.0000513 pts | 450 USD | 641 USD | 45 USD | 64 USD | 250 |
| 6B | M6B | 0.00740 pts | 0.00958 pts | 463 USD | 598 USD | 46 USD | 60 USD | 250 |
| 6A | M6A | 0.00490 pts | 0.00664 pts | 490 USD | 664 USD | 49 USD | 66 USD | 250 |
| 6C | MCD | 0.00283 pts | 0.00358 pts | 282 USD | 357 USD | 28 USD | 36 USD | 250 |
| 6S | MSF | 0.00748 pts | 0.0104 pts | 934 USD | 1,302 USD | 93 USD | 130 USD | 250 |
| ZN | -- | 0.438 pts | 0.594 pts | 438 USD | 594 USD | -- | -- | 250 |
| ZB | -- | 0.844 pts | 1.12 pts | 844 USD | 1,117 USD | -- | -- | 250 |
| BTC | MBT | 2,870.0 pts | 3,792.0 pts | 14,350 USD | 18,962 USD | 287 USD | 379 USD | 250 |
| ETH | MET | 112.0 pts | 164.9 pts | 5,600 USD | 8,244 USD | 11 USD | 16 USD | 250 |
n = 5,000 · 2025-10-28 to 2026-10-15 · historical futures data
Daily true range over the last 250 complete sessions of each future, from 28 or 29 October 2025 (depending on each market's holidays) to 15 October 2026: the day's high minus its low, extended to the previous close when the price opened with a gap (on a contract roll day, high minus low only). Exchange trading day, from 18:00 ET the evening before to 17:00 ET, on the most-traded contract, which changes after two days running of volume leadership. The median is the typical day: half the sessions moved less; three in four sessions fall below the 75th percentile. Dollars = points times the point value of the standard contract, taken from the public specifications of each contract used by the platform's risk calculator (silver, which is not in it, comes from the contract table of the prop-firm lab), and times the micro's fraction from that same contract table: one tenth of the standard in almost every case, one fifth for SIL, 1/50 for MBT and 1/500 for MET. Where that table has no micro, the cell is left empty. For comparison, the 2010 to 2026 median is 30.6 points in ES and 98.9 in NQ: in points, the range grows with the price level (ES closed at 1,049 in June 2010 and at 7,786 on 15 October 2026), so a figure spanning many years sits below what the market moves today. It is what happened, not a signal.
Points are not dollars#
Multiply the average range in points by the point value and you get what one contract moves, in money, on an average day. With the figures above: ES is 43.7 × 50 = 2,185 USD. NQ is 174.8 × 20 = 3,496 USD. RTY is 39.6 × 50 = 1,980 USD. YM is 339.4 × 5 = 1,697 USD. NKD is 451.1 × 5 = 2,255.50 USD.
The order flips relative to the table in points. The YM has the second-largest range in points and moves the least money per contract. The RTY has the narrowest range in points and moves more money than the YM. Reading only the points leads to wrong conclusions about risk.
A full example, for educational purposes only. Capital of 50,000 USD and 1% risk is 500 USD. With a 10-point stop in ES, each contract risks 10 × 50 = 500 USD: one contract fits. With a 40-point stop in NQ, each contract risks 40 × 20 = 800 USD, the result is 0.625 and, rounding down, zero contracts. The calculation can return zero, and then the correct answer is not to take that idea with that contract.
Not all days are the same size#
The average range is an average, and an average hides its dispersion. The second table classifies each ES session according to how closely its range resembles the instrument's own recent average range.
A little over half of sessions fall in the normal band, between 70% and 130% of that average. Around one in four is compressed below 70%, and somewhat more than one in five expands above 130%. Sizing always against the average day leaves out almost half of all days.
The effect is direct. A stop calibrated to the average day falls short in an expanded session and is oversized in a compressed one. Adjusting the distance to a recent volatility measure changes the denominator and, with it, the number of contracts.
Keep in mind that this table is calculated on ES only. The proportions for another instrument may be different and would have to be measured separately before carrying them over.
How closely the day's range matches its average
ES
Swipe to see the sample →
| Day type | Frequency | Days |
|---|---|---|
| Compressed (under 70% of the average range) | 26.3% | 1,105 |
| Normal (70-130%) | 51.1% | 2,148 |
| Expanded (over 130%) | 22.6% | 952 |
n = 4,205 · 2010-06-25 to 2026-09-16 · historical futures data
Compares each session's range with the instrument's own recent average range.
How far price travels from the open#
The average range says how big a day is. The third table answers a different question: from the 9:30 open, how often ES reached each distance before the 16:00 close, New York time. That is 4,133 sessions, from 2010-06-07 to 2026-10-09.
The distance is not in points but in units of expected move, a measure known before the open. It is not plain ATR: it is 0.8 times the daily deviation implied by the VIX, which is the previous close × VIX / 100 / √252. On days with no VIX reading, 0.88 times the 20-session average true range is used. An example for illustration only: with ES at 6,000 and the VIX at 16, the implied daily deviation is about 60 points and the expected move about 48.
A quarter of that move was reached to the upside in 69.4% of sessions and to the downside in 67.6%. Half, in 43.9% and 45.2%. Three quarters, in 25.6% and 27.9%. The full expected move, in 13.2% to the upside and 17.7% to the downside.
For position sizing this puts numbers on two intuitions. A stop a quarter of the expected move away from the open sits inside the noise: price went through there in two out of three sessions, in each direction. And a target a full expected move away was reached roughly one time in six.
Three limits. The two columns are independent: the same session can reach the distance both up and down, and the table does not say in which order. The distance is measured from the open, not from your entry. And it is measured in ES only. Note of October 13, 2026: in ES, NQ, RTY and YM the platform now estimates the expected range with a model that uses more data; this table still describes the previous unit.
How far ES travels from the open, in expected-move units
ES
Swipe to see the sample →
| Distance from the open | Reached on the upside | Reached on the downside | Sessions |
|---|---|---|---|
| 0.25 × expected move | 69.4% | 67.6% | 4,133 |
| 0.5 × expected move | 43.9% | 45.2% | 4,133 |
| 0.75 × expected move | 25.6% | 27.9% | 4,133 |
| 1.0 × expected move | 13.2% | 17.7% | 4,133 |
n = 4,133 · 2010-06-07 to 2026-10-09 · historical futures data
ES regular session (9:30-16:00 ET), 7-Jun-2010 to 9-Oct-2026. Expected move = 0.8 × the daily implied standard deviation (prior close × VIX / 100 / √252); on days without a VIX reading, 0.88 × the 20-session average true range. It is known before the open. The distance is measured from the 9:30 ET opening price and 'reached' = the session trades that price before the 16:00 ET close. The two columns are independent: one session can reach the distance in both directions. It is what happened, not a signal.
What about options positioning? Not demonstrated#
There is a popular idea that the daily options-positioning reading, positive or negative, anticipates whether the day will be quiet or busy. The reading is published by third parties before the open; it is not our data. We measured it against the ES range over the 131 sessions with a clear reading between 2026-03-06 and 2026-10-09.
On the raw numbers, the difference is there. With a positive reading the session range averaged 0.79 expected moves, over 79 sessions; with a negative reading, 0.90, over 52. Negative-reading days were 29.7% wider, with a 95% confidence interval of +3.5 to +52.4.
But those days already arrived with higher volatility. After accounting for the volatility index, yesterday's range and the opening gap, the difference drops to 4.1%, with an interval that includes zero.
The honest conclusion is 'not demonstrated', not 'refuted'. The sample is small: with these sessions only a much larger difference would be reliably detected. What can be said is that most of what that reading seemed to add was already in the level of volatility, which is public and free. And it says nothing about direction.
Options positioning and the day's range in ES: what is left once volatility is accounted for
ES
Swipe to see the sample →
| Reading of the day | Session range, in expected moves of the day | Raw difference in range | Difference after accounting for the volatility index, yesterday's range and the opening gap | Sessions |
|---|---|---|---|---|
| Positive reading before the open | 0.79 × | -- | -- | 79 |
| Negative reading before the open | 0.90 × | -- | -- | 52 |
| Difference: negative against positive | 0.10 × | 29.7% | 4.1% | 131 |
n = 131 · 2026-03-06 to 2026-10-09 · historical futures data
ES, regular session (9:30-16:00 ET), 6-Mar-2026 to 9-Oct-2026: 141 sessions with a reading, of which 10 with a mixed reading are left out. The reading is the one third parties post daily before the open about options positioning (positive or negative), transcribed as a number; it is not our data. Expected move = one-day move implied by the volatility index of the eve; the first column is the mean. Raw difference = mean range (in logs) of the negative sessions against the positive ones: +29.7% [+3.5 to +52.4]. The negative sessions arrived with a higher volatility index (19.9 against 16.9). After accounting for the volatility index, yesterday's range and the 20-session average range with a model fitted before the sample, the difference drops to +7.9% [−4.6 to +21.9]; adding the opening gap, to +4.1% [−8.5 to +17.7] (51 and 78 sessions). 95% confidence intervals from resampling blocks of 5 sessions (the reading repeats from one day to the next). Small sample: with these sessions only a difference of about 19.2% of range would be detected reliably; seeing one of 10% would take about 213 sessions per group. Conclusion: not demonstrated; most of the difference is explained by the level of volatility. It says nothing about direction.
What the formula does not include#
The formula assumes the stop is executed at the stop price. That does not always happen. Slippage at a moment of low liquidity, or an opening gap that jumps the level, produces a larger loss than calculated. The number that comes out of the division is a minimum, not a guaranteed ceiling.
It also excludes commissions, exchange fees and financing. With short stops and frequent trades those costs stop being a detail.
It does not model correlation. Three positions at 1% in instruments that move together are not three 1% risks: on an adverse day they behave almost like a single, larger one.
And it does not replace aggregate limits: maximum daily loss, total simultaneous exposure and the margin required by the broker. The calculation says how many contracts fit within the risk of one idea, not whether your account can sustain several at once.
Calculations, not advice#
Everything above is arithmetic. The specifications come from the exchange, the average ranges from a historical series with its sample and period in plain view, and the formula is a division. None of it offers an opinion on what you should do.
The decisions remain yours: how much capital you allocate, what percentage you risk, where you place the stop, and whether the trade fits your plan.
Historical ranges describe what happened in the measured period; they do not predict tomorrow's. This article is informational and educational material, not personalized investment advice or a recommendation to buy or sell. Trading futures involves risk of loss, which can exceed the initial capital.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- How do you calculate position size in futures?
- You divide the money you accept losing, which is capital times the risk percentage, by the cost of that loss with one contract, which is the stop distance in points times the point value. The result is rounded down.
- How much is a point worth in the ES and the NQ?
- One point of the E-mini S&P 500 is worth 50 USD per contract, with a 0.25 tick equal to 12.50 USD. One point of the E-mini Nasdaq-100 is worth 20 USD, with a 0.25 tick equal to 5.00 USD. These are public exchange specifications.
- What percentage of capital should you risk per trade?
- There is no universally correct percentage, and we do not give personalized recommendations here. It is a decision that depends on capital, horizon and tolerance for losing streaks. The formula works with whatever percentage you define.
- What happens if the calculation gives less than one contract?
- It means that, with that risk distance and that risk per trade, not even a single contract fits within the limit; rounding up breaks the calculation. The calculation does not say what to do.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- Trading Journal — Import your trades from your platform's file or by webhook, and check whether your results differ from chance.
- Lab — Monte Carlo, chronological validation and funded-account simulation on setups.
- Today, macro data, alerts and risk calculator — Today, economic calendar, alerts and a risk calculator for 30 contracts.
The calculation and its limits are in the methodology.
Take it to your chart, free
Key Levels: How far did price travel from the open in past sessions?
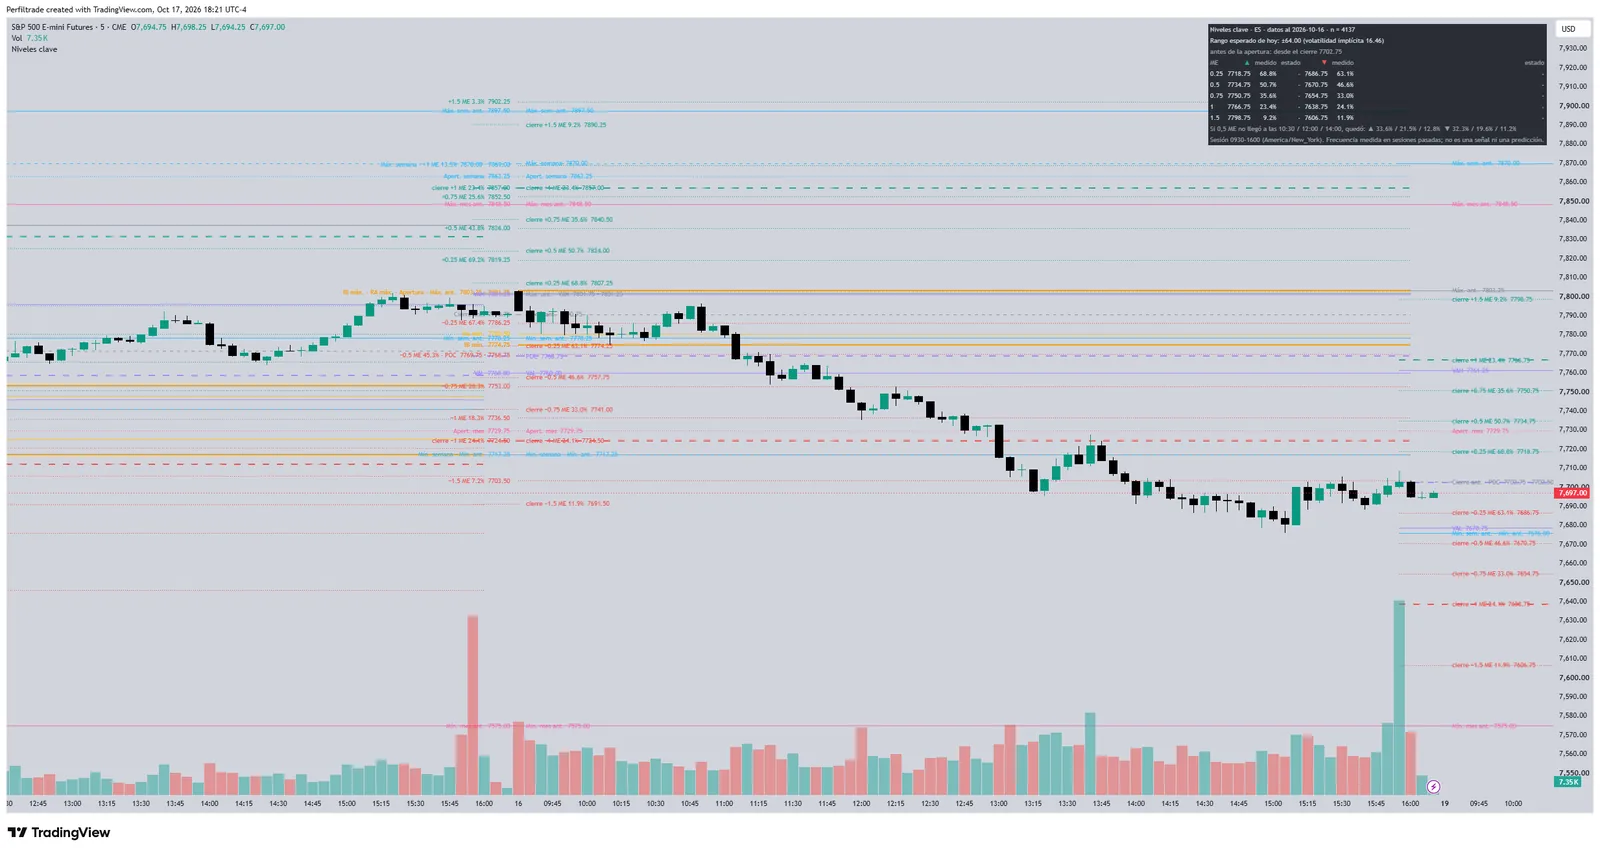
A ladder of distances from the open, from 0.25 to 1.5 times the day's typical move, with how often price reached each rung and its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). Position Sizing in Futures: How to Calculate It. https://www.perfiltrade.com/en/learn/position-sizing-risk-management
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →