COT Report: How to Read Positioning in Futures
Updated October 19, 2026
What the COT report is and who publishes it#
The Commitments of Traders, known as COT, is a public report from the Commodity Futures Trading Commission (CFTC), the U.S. derivatives markets regulator. It is not an analysis: it is an administrative count. The CFTC collects the open positions reported to it by intermediaries and publishes them aggregated by participant category.
That nature defines how it is used. The report does not say what will happen. It says who was positioned, on which side and with how many contracts, on a specific cutoff date. Everything else is the reader's interpretation.
The breakdown only includes participants that exceed the reporting levels set by the CFTC itself. Positions below that threshold are grouped as non-reportable, with no detail. That is why the COT portrays the large participant, not the entire market.
The calendar: Tuesday data, Friday release#
The report is published once a week. The snapshot is taken at Tuesday's close and the CFTC releases it on Friday afternoon, U.S. Eastern time. Three full business days pass between the data date and its release.
That lag is the most important thing about the report and the one most often ignored. When you read it on Friday, the market has already traded three days. A position that looks loaded in the snapshot may have been unwound in that time, or doubled.
Holidays shift the release. If there is one during the week, the CFTC's official calendar governs, not the Friday habit. The practical consequence is clear: the COT is not useful for deciding an intraday entry, but for describing positioning at a weekly resolution.
Participant categories are not always the same#
There is a widespread basic mistake: talking about “the COT categories” as if there were a single list. There is not. The CFTC publishes several reports and each one uses its own category scheme.
Financial futures (stock indexes, currencies, interest rates) appear in the Traders in Financial Futures report, abbreviated TFF. It has four categories: Dealer/Intermediary, Asset Manager/Institutional, Leveraged Funds and Other Reportables, plus the non-reportable block.
Dealer/Intermediary are intermediaries and market makers who hedge the risk of what they sell to their clients; their net reflects hedging, not a directional bet. Asset Manager/Institutional is real long-term money: pension funds, mutual funds, insurers. Leveraged Funds is the most speculative part. Other Reportables covers large traders who do not fit the previous three.
Commodities use another report, the Disaggregated, with different categories: Producer/Merchant/Processor/User, Swap Dealers, Managed Money and Other Reportables. There is also the older Legacy scheme, which only separates Commercial, Non-commercial and non-reportables. The three schemes are not equivalent. Comparing a category from one report with another from a different report makes no sense.
Open interest: the other half of the reading#
Open interest is the total number of contracts still alive on the cutoff date: positions that nobody has closed or that have not expired. It is not volume. Volume counts what was traded in a period; open interest counts what remains standing.
Every contract has a buyer and a seller, so in aggregate longs equal shorts. Each category reports its longs and its shorts, and the net is the difference. The sum of all the nets is zero. That is why the phrase “everyone is long” is impossible by construction: if one group is net long, another is net short by the same amount.
Open interest supplies the missing scale. A net of one hundred thousand contracts means something different depending on whether total open interest is growing or falling. Positioning built with rising open interest is new money coming in. The same net with falling open interest usually comes from closings, not from new conviction.
Normalizing: from contract counts to a 0-to-100 index#
A net in contracts cannot be compared across markets or across eras. Market size changes, the contract changes, and the absolute number does not say whether that level is high or low for that instrument. You have to normalize.
The usual normalization places the current net position within its own recent history: 0 is the low of the window, 100 the high. A value near the extremes indicates the group is more loaded to one side than in almost the entire chosen window.
On the platform this index uses a 156-week window, that is, three years, and covers 17 financial instruments with weekly history since 2010. Each page shows the net for dealers, asset managers and leveraged funds, the weekly change, the one-year percentile and total open interest with its change.
The window is a decision, not a fact. With 52 weeks the same data gives a different index than with 156. That is why the window is always stated alongside the number, and when the available history is shorter than the window, that is stated too.
Typical reading mistakes#
The first is treating the data as if it were from today. It is from the previous Tuesday. Any conclusion that depends on the current price needs, at a minimum, to check what price did in those three days.
The second is confusing net position with opinion. Dealers do not trade a view of the market: they absorb the other side of what their clients do. Their net moves because client flow moves.
The third is mixing contracts. The CFTC lists the E-mini contract, the micro and the consolidated line of the same index separately. They are different rows with different sizes. Adding them together or switching between them from one week to the next corrupts any weekly-change or percentile calculation.
The fourth is comparing series that do not measure the same thing: the CFTC publishes futures-only versions and combined futures-and-options versions. And the fifth, the costliest, is reading an extreme as a dated turning-point call. An extreme describes a situation; it does not schedule its end.
Does a positioning extreme announce a big move?#
The most repeated idea about the COT is that when large speculators reach an extreme, a big move is coming. The table measures it in ES with the Legacy report, from 2010-06-01 to 2026-10-13, without looking at the side: how much price moved, in absolute value, 4, 13 and 26 weeks later. The reading is the non-commercials' net position within its range of the last 156 reports: 80 or more is an extreme long and 20 or less an extreme short.
Taking every week, ES moved 5.90% on average over 13 weeks, over 841. With speculators at an extreme long, 5.02% (113 weeks, 26 episodes); at an extreme short, 6.57% (108 weeks, 20 episodes), and with no extreme, 5.94%.
To know whether those differences mean anything, we moved the same extreme stretches to random dates 2,000 times. None of the six cells stands apart from chance: the extreme long at 13 weeks gives 5.02% against 5.93% on random dates, and the extreme short 6.57% against 5.90%. An extreme did not announce a bigger or smaller move than any given week.
The sample is smaller than it looks. An extreme reading lasts many weeks in a row and those weeks overlap: the 113 of the extreme long are 26 separate episodes and the 108 of the short, 20. The extreme describes who is positioned and by how much; it does not say when or how much price will move.
After a positioning extreme: how much ES moved, whichever the side
ES
Swipe to see the sample →
| Weekly report reading | Mean absolute move at 4 weeks | At 13 weeks | At 26 weeks | Weeks |
|---|---|---|---|---|
| Speculators at an extreme long (26 episodes) | 3.0% | 5.0% | 7.9% | 113 |
| Speculators at an extreme short (20 episodes) | 3.9% | 6.6% | 9.2% | 108 |
| No extreme | 3.1% | 5.9% | 9.1% | 620 |
| All weeks | 3.2% | 5.9% | 8.9% | 841 |
n = 841 · 2010-06-01 to 2026-10-13 · historical futures data
ES, CFTC Legacy report (futures only), readings from 1-Jun-2010 to 13-Oct-2026. Index = large speculators' net position as a share of open interest, inside its own range of the last 156 reports: 80 or more is an extreme long, 20 or less an extreme short. Move = absolute size of the price change from the first close of the Monday after publication to 4, 13 and 26 weeks later, on the roll-adjusted continuous series; which side is not measured. Weekly readings overlap: the number of separate episodes is next to each extreme. Control: the same extreme stretches moved to random dates (2,000 draws); a cell is only different from chance when its p is below 0.05 / 6. Extreme long at 4 weeks: 2.96% vs 3.19% on random dates (same as chance, p = 0.692); at 13 weeks: 5.02% vs 5.93% (same as chance, p = 0.317); at 26 weeks: 7.90% vs 8.91% (same as chance, p = 0.560). Extreme short at 4 weeks: 3.89% vs 3.20% (same as chance, p = 0.128); at 13 weeks: 6.57% vs 5.90% (same as chance, p = 0.412); at 26 weeks: 9.15% vs 8.98% (same as chance, p = 0.892). The 'Weeks' column is the 13-week one. Size only; it is what happened, not a signal.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The limits of what this report measures#
Coverage has clear boundaries. The TFF report includes stock indexes, currencies and rates, but not metals, energy, agricultural products or crypto. Those markets are in the Disaggregated report, with other categories and a different file format.
Resolution is weekly and the lag is three business days. There is no daily version. In addition, the CFTC can revise published data, so a series downloaded months ago does not always match the current one.
And there is a conceptual limit: the report counts contracts, not intentions. It does not distinguish a directional position from a hedging leg within a larger strategy. A large net short can be a bearish fund or the hedge of a long cash portfolio. Also, a loaded positioning can persist for months: nothing in the report forces it to unwind.
How to use it without asking for what it does not give#
The reasonable use of the COT is as a background context filter. It answers slow questions: who is on each side? How extreme is that compared with its history? Is positioning being built or unwound?
A richer reading appears when two groups diverge. If institutional money and leveraged funds point in opposite directions, the data describes a real tension between two types of participant. That is information, not an instruction.
That context is then cross-checked against price structure and against historical statistics that come with their sample and period. The COT alone never closes a decision.
This article is informational and educational material. It is not personalized investment advice or a recommendation to buy or sell. Trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- How often is the COT report published?
- Once a week. The data corresponds to Tuesday's close and the CFTC publishes it on Friday afternoon, U.S. Eastern time. A holiday during the week can shift that date, so it is worth checking the official calendar.
- What does Leveraged Funds mean in the COT?
- It is one of the four categories in the financial futures report. It groups leveraged funds, the most speculative, shortest-horizon segment. It is usually contrasted with Asset Manager, which represents long-term institutional money.
- Does a COT extreme anticipate a big move?
- In ES it did not. Over 13 weeks, with large speculators at an extreme long price moved 5.02% and at an extreme short 6.57%, against 5.90% for all weeks since 2010. Compared with the same stretches on random dates, no difference stands apart from chance.
- Is the COT report useful for stocks?
- Not for individual stocks. It covers futures markets, including futures on stock indexes, currencies and rates. There is no equivalent in this report for a specific stock.
- What is the 0-to-100 COT Index?
- It is a group's net position placed within its own history: 0 marks the low of the window and 100 the high. The number depends entirely on the window chosen, which is why it should always state how many weeks it covers.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- COT positioning — Weekly COT for 17 instruments with a 0-100 index and loaded positioning.
The calculation and its limits are in the methodology.
Take it to your chart, free
COT Positioning: Where is each group positioned, and what happened after similar readings?
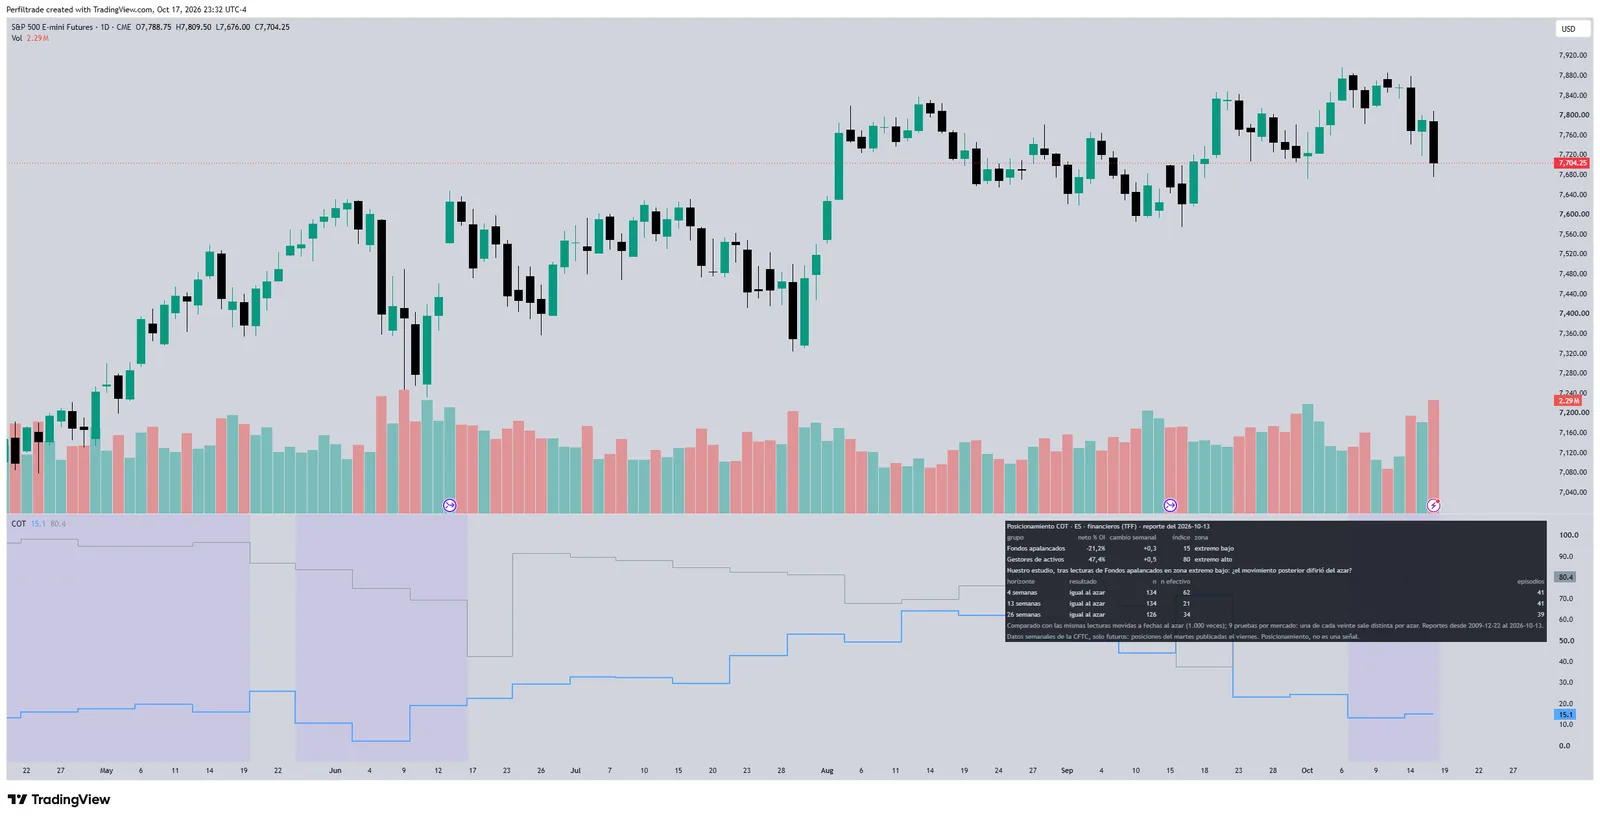
Next to each zone, our study's verdict at 4, 13 and 26 weeks, with its n: whether the later move differed from chance, never a return or its sign.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 19, 2026). COT Report: How to Read Positioning in Futures. https://www.perfiltrade.com/en/learn/cot-report-how-to-read
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →