VAH, VAL and POC: How to Read the Value Area in Futures
Updated October 24, 2026
What the Value Area is#
The Value Area is the band of prices where about 70% of a session's activity took place. It can be computed on time or on volume, but the idea is the same: mark where most of the trading happened and leave the tails out.
That 70% does not come from any property of the market. It is a convention borrowed from the standard deviation of a normal distribution, which covers about 68%. It was rounded up and it stuck.
Its usefulness is framing. A price inside the Value Area is in a zone the market accepted during the session. A price outside is where there was little agreement and little time spent.
POC, VAH and VAL, one by one#
POC stands for Point of Control: the single price with the most time or volume traded in the session. It is the widest point of the profile and the one that often acts as a reference when price rotates.
VAH, Value Area High, is the upper edge of the band. VAL, Value Area Low, is the lower edge. Between the two sits that 70% of the session's activity.
All three are fixed once the day closes. The next day they serve as references for yesterday's value, and that is where their interest lies: they give a map of the prior day on which to read the current one.
Do not confuse the POC with the VWAP. The POC is the price where the most trading took place; the VWAP is the volume-weighted average price. They can coincide or be far apart.
How the Value Area is built#
The most common method starts at the POC and keeps adding the adjacent levels with the most activity, upward or downward, until it covers 70% of the total. The highest level reached is the VAH and the lowest is the VAL.
There are variants. Some start from TPO, short for Time Price Opportunity: the block that shows price touched a level during a period, normally thirty minutes. Others start from the volume traded at each price. The results are similar, not identical.
The decision that moves the result most is which session you use. Computing the Value Area on the regular session or on the full session of almost twenty-four hours gives different levels for the same day. Before comparing figures across sources, check that they refer to the same session.
The open versus the prior day's value#
The most common use is comparing today's open with yesterday's Value Area. Opening inside suggests the market is still accepting the same value; opening outside suggests it is probing a new one.
The usual scenarios come from there. Inside value, rotation between VAL and VAH is expected, with the POC as the central reference. Outside value, either price is accepted and the day turns directional, or it returns to the range and the move away proves false.
All of this is a vocabulary, not a forecast. The only way to know whether a scenario has anything behind it is to measure it on a large sample and accept the result even if you do not like it.
The 80% rule, measured#
The most repeated Value Area script is the so-called 80% rule: if price opens outside yesterday's value and comes back in, it will travel through the value to the opposite edge. Here it is measured in ES, regular session, from 2010-06-07 to 2026-09-30, with 30-minute profiles and a 70% Value Area.
The condition is the usual one: open outside yesterday's Value Area and make two consecutive 30-minute closes inside. In the 950 sessions where it happened, price reached the opposite edge before the close 61.4% of the time. When acceptance came in the first two hours, 67.2%, over 509.
The important nuance: in many of those sessions price had already touched the opposite edge when acceptance completed. Keep only the cases where the edge was still untouched, the ones somebody could actually trade, and the figure drops to 47.8%, over 703 sessions. It is the same opening above or below value.
It is not 80%. With the rule as stated, six out of ten; when there is still ground to cover, a coin. And it does not say how far price moved away before getting there.
The '80% rule' measured: back into yesterday's value and across to the other edge
ES
Swipe to see the sample →
| Case | Reaches the opposite edge in the same session | Sessions |
|---|---|---|
| All acceptances | 61.4% | 950 |
| Acceptance within the first two hours | 67.2% | 509 |
| The opposite edge had not been touched yet | 47.8% | 703 |
| Opens above value: all | 64.9% | 507 |
| Opens above value: opposite edge untouched | 47.8% | 341 |
| Opens below value: all | 57.3% | 443 |
| Opens below value: opposite edge untouched | 47.8% | 362 |
n = 950 · 2010-06-07 to 2026-09-30 · historical futures data
ES regular session (9:30-16:00 ET), 7-Jun-2010 to 30-Sep-2026. Value area = 70% of the TPOs of the previous regular session, 30-minute period profile. Acceptance = the session opens outside that area and two consecutive 30-minute periods close inside it. 'Reaches' = it trades the opposite edge of the area before the close. 'First two hours' = the acceptance completes by the fourth period at the latest. 'The opposite edge had not been touched yet' leaves out the sessions that had already traded it when the acceptance completed: in those the rule is met by definition and there is nothing left to gain. Previous-day levels adjusted to the day's contract on contract changes. It is what happened, not a signal.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
What can be measured with yesterday's range#
A simpler version of the same idea uses the prior day's range instead of its Value Area: just the high and the low, with no weighting by time or volume. It is less refined, but it can be measured without ambiguity.
The table takes the ES sessions in which price broke the prior day's high or low, and calculates how often that session closed green after breaking above, or red after breaking below. The color is the close versus the same day's open.
It is, therefore, a measure of consistency between the break and the sign of the session. It does not say that the close ended beyond the level that was broken, and that difference matters when interpreting it.
Breaking yesterday's range and the color of the close
ES
Swipe to see the sample →
| Day | Breaks the high and closes green | Breaks the low and closes red | Breaks |
|---|---|---|---|
| Monday | 72.4% | 61.9% | 770 |
| Tuesday | 67.3% | 68.8% | 864 |
| Wednesday | 69.0% | 65.3% | 850 |
| Thursday | 70.3% | 65.2% | 873 |
| Friday | 74.1% | 69.2% | 765 |
n = 4,122 · 2010-06-07 to 2026-10-09 · historical futures data
Session color = close versus the same day's open. It does not measure whether the close ended beyond the broken level. A day that breaks both sides counts in both columns. Version of 12-Oct-2026, with data to 9-Oct-2026: a close equal to the open no longer counts as red, which used to inflate the low column. Measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET).
What the table shows, and what it does not#
The frequencies are strikingly similar. Breaking yesterday's high and closing green happens in 74.1% of the 765 Friday breaks in ES, the highest case, and in 67.3% of the 864 Tuesday ones, the lowest.
On the downside, breaking the low and closing red ranges from 69.2% of the 765 Friday breaks in ES to 61.9% of the 770 Monday ones. The range of variation between days is narrow. The table was recomputed in October 2026, with data through 2026-10-09, the day defined as the exchange trading day and a close equal to the open no longer counted as red; that is why some rows changed by several points from the first version.
The reasonable conclusion is not that the day of the week decides anything, but that the relationship between breaking a prior extreme and closing in the same direction is stable in this ES series. What cannot be inferred is that trading that break would be profitable.
That is because the color of the close does not say how far from the broken level the day ended, or what happened along the way. The adverse excursion, how far price moved against you before the close, is left out. And a day that breaks both extremes counts in both columns: the figures in a row are not mutually exclusive.
Does closing outside value announce a bigger day?#
It is often said that closing outside the value area sets up a big day next. We measured it in ES, NQ, YM and RTY, from 7-Jun-2010 to 23-Oct-2026 (RTY since 2017): how much the next session moved, as a percentage of its ATR, against the sessions that follow a close inside value after a day of similar size.
In ES, the session after closing outside had a range of 106.7% of its ATR, against 100.6% after closing inside (3,949 sessions): the same as chance. In NQ, 107.6% against 99.8% (3,949): once the size of the day is matched, 7.6 ATR points more, a difference that does hold up after correcting for 54 comparisons. In YM and RTY, the same as chance.
The type of day does not change beyond chance either: in all four indices, the next trend day cannot be told apart between closing inside or outside. The four move together, so their rows are not four independent confirmations. It is size, not direction.
Closing outside the value area: the next session's range and type, against closing inside
ES, NQ, YM y RTY
Swipe to see the sample →
| Market | Closes outside its value area | Next range after closing outside (% of ATR) | Next range after closing inside (control) | Difference with the own-range control (ATR points) | Reading | Next-day trend day: after closing outside | Next-day trend day: after closing inside (control) | Difference with the control (points) | Reading | Sessions |
|---|---|---|---|---|---|---|---|---|---|---|
| ES | 43.4% | 106.7% | 100.6% | 4.4 | same as chance | 19.9% | 19.9% | 0 | same as chance | 3,949 |
| NQ | 40.7% | 107.6% | 99.8% | 7.6 | more than the control | 17.5% | 15.1% | 2.4 | same as chance | 3,949 |
| YM | 41.5% | 105.4% | 101.0% | 3 | same as chance | 16.1% | 17.3% | -1.2 | same as chance | 3,951 |
| RTY | 38.8% | 104.2% | 101.0% | 2.5 | same as chance | 13.5% | 14.9% | -1.4 | same as chance | 2,219 |
n = 14,068 · 2010-06-07 to 2026-10-23 · historical futures data
Regular session (9:30-16:00 ET) of ES, NQ, YM and RTY, front contract, 7-Jun-2010 to 23-Oct-2026 (RTY from 10-Jul-2017); complete sessions only (early closes left out) and no contract change between the sessions compared. Value area = 70% of the TPOs of 30-minute periods, grown from the POC. ATR = average regular-session range of the 14 previous complete sessions. Closes outside = the last price at 16:00 is above the VAH or below the VAL of the session itself. The next session is measured: its range as a percentage of its ATR and whether it is a trend day (leaves the Initial Balance on one side only by more than its width and closes in the outer third). Control = the sessions that follow a close inside value; the difference is computed inside five buckets of the day's own range in ATR, because a big day closes outside more often and tends to be followed by another big one. Reading: Benjamini-Hochberg correction at 5% over 54 comparisons, the 46 fixed before looking at any result and the 8 rotation and 5-session ones of these tables, which were not; a cell that does not survive it is 'same as chance'. The four indices move together: their rows are not four independent confirmations. Different from the control: NQ (range); the rest is same as chance. It is size, not direction. It is what happened, not a signal.
The limits of this measurement#
The first limitation is fit. The table uses the prior day's range, not its Value Area. They are different references: the range includes the tails where there was hardly any trading, and the Value Area discards them. These figures should not be read as if they measured breaks of the VAH or VAL.
The second is drift. The series is ES, runs from 2010-06-07 to 2026-09-16 and gathers 4,188 breaks of an index that rose over the period as a whole. That pushes up any figure that depends on green closes.
The third is cost: no percentage accounts for spread, commissions or slippage. The fourth is the definition of green. Close versus open is one convention among several; taking yesterday's close as the reference would give a different table. None is the correct one, you just have to state which one is used.
How to use these levels#
These references help you prepare the session; they do not replace your own judgment. Marking the prior day's POC, VAH and VAL, along with its high and low, leaves a few specific prices to pay attention to when the market reaches them.
From there, the useful step is to record what price did at each level and compare that record with the corresponding base rate, that is, the historical frequency of the same scenario under similar conditions.
This text is informational material on reading historical data and is not personalized investment advice. Past results do not anticipate future results, and trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Does the Value Area 80% rule hold?
- In ES it does not reach 80%. When price opens outside yesterday's value and makes two 30-minute closes inside, it reaches the opposite edge in the same session 61.4% of the time, over 950 sessions since 2010. If the opposite edge had not been touched yet at that point, 47.8%, over 703.
- What happens if price opens right at yesterday's POC?
- It is considered an open in value, at the point of greatest acceptance of the prior day. It is the most neutral scenario: it gives no directional information and requires waiting to see which way price moves.
- Why is the Value Area 70%?
- It is a convention inherited from the standard deviation of a normal distribution, which covers about 68%. Nothing in the market requires that number, and some implementations use different percentages to define the zone.
- Is the Value Area useful when trading European hours?
- The concept can be computed on any session, including the European one. What you cannot do is mix them: the levels and statistics of one session do not apply to another without recalculating from scratch with that definition.
- How long do the prior day's POC and Value Area remain valid?
- They are references for the following session, mainly during its first hours. They lose relevance as the day builds its own profile and price moves away from the zone. They are not permanent levels.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- In-session Market Profile — Initial Balance, Value Area, POC and profile shape during the session, against their history.
The calculation and its limits are in the methodology.
Take it to your chart, free
Session Profile: Where did price spend the most time during the session?
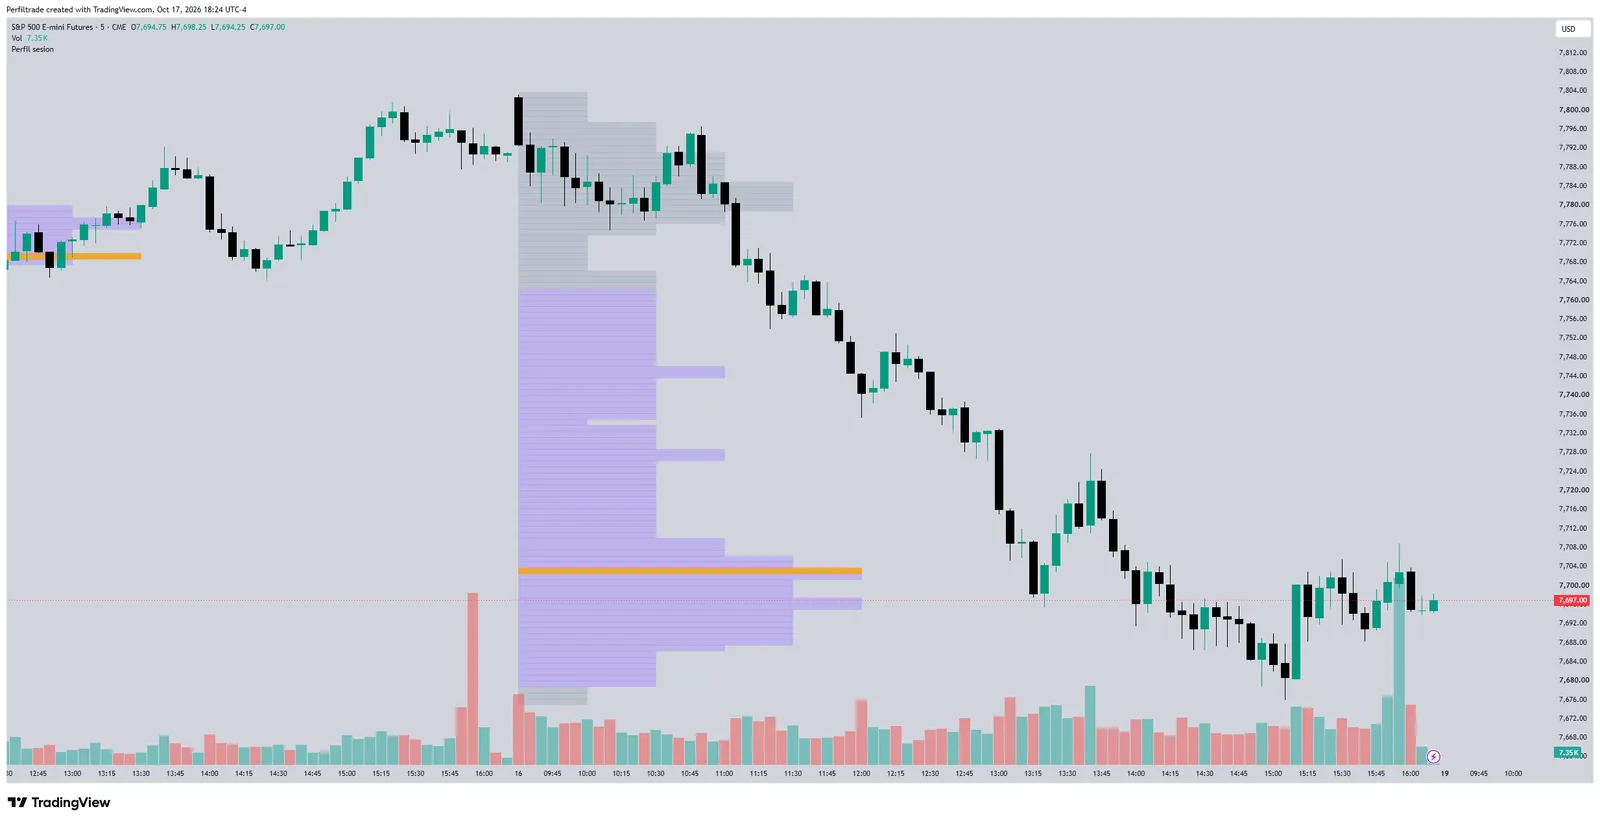
POC and a 70% Value Area, with optional period letters.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 24, 2026). VAH, VAL and POC: How to Read the Value Area in Futures. https://www.perfiltrade.com/en/learn/value-area-poc-vah-val
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →