RTH vs Globex in Index Futures: What Changes
Updated October 12, 2026
One contract, two sessions#
Index futures such as ES or NQ trade almost twenty-four hours a business day. The regular session, abbreviated RTH for Regular Trading Hours, is the window that matches the US stock market: 9:30 to 16:00 New York time.
Everything else is the extended electronic session, or ETH. In CME futures it is called Globex, after the name of the electronic platform where they trade. It is the same contract, the same account and the same order book; what changes is who is in front of the screen.
The practical difference is participation. The regular session concentrates most of the institutional volume. On Globex the book is thinner and a few contracts move price more. That is why almost all structure statistics are computed on RTH.
What exactly the overnight session is#
Overnight is the stretch of Globex from one day's regular close to the next day's regular open. It includes the European early morning and the Asian day, and it is where most of the news the US market cannot digest live comes in.
That stretch produces two things that are used all day: the overnight range, with its high and low, and the opening gap, which is the distance between yesterday's regular close and today's open.
It is worth fixing the hours in writing, including the time zone and the holiday calendar. Without that, two people can call different stretches overnight and get figures that cannot be compared.
Where the day's extreme really forms#
If the regular session concentrates the volume, it would be logical to think the day's extreme is decided there. The table distributes ES's daily high and low across the segments of the 24-hour cycle, over 4,175 sessions, and that is not what comes out.
The regular session carries weight, but it does not decide everything. Between 9:30 and 16:00 New York time, 48.1% of ES highs and 47.3% of lows form, over those 4,175 sessions. The European morning before the open contributes 18.3% of highs and 17.7% of lows.
Asia contributes 15.5% of highs and 22.3% of lows: it is the segment with the clearest imbalance between the two extremes. The minutes left between close and open, grouped as off-session, take 18.0% of highs and 12.7% of lows.
The reading cuts both ways. The first two hours of the regular session, which coincide with the end of the London day, account for 18.7% of highs on their own. But anyone looking only at the RTH chart misses the 51.9% of highs that form overnight or during the European morning.
Where the day's high and low form
ES
Swipe to see the sample →
| Session | Day's high | Day's low | Sessions |
|---|---|---|---|
| Asia | 15.5% | 22.3% | 4,175 |
| London | 18.3% | 17.7% | 4,175 |
| London/NY overlap | 18.7% | 19.5% | 4,175 |
| New York | 29.4% | 27.8% | 4,175 |
| Outside sessions | 18.0% | 12.7% | 4,175 |
n = 4,175 · 2010-06-07 to 2026-09-15 · historical futures data
Split of the daily extreme across the sessions of the 24-hour cycle. 'London/NY overlap' is when the extreme prints while both sessions are open, so it cannot be credited to just one. 'Outside sessions' are the minutes left between close and open.
See it on a real day
The Today brief: how much your market usually moves, how far its levels are and when the next release is due, every figure with its n. No sign-up.
See the demo →The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The night's direction and what the following day does#
The second natural question is whether what happens overnight marks the day. The table measures the direction of the overnight stretch, from yesterday's regular close to today's open, and then looks at how often the regular session kept moving in that same direction.
When the night is up, continuation in ES ranges from 50.8% on Wednesday, over 832 sessions, to 56.5% on Friday, over 770 sessions. Monday shows 53.4% with 801 sessions, Tuesday 53.6% with 838 and Thursday 53.0% with 831.
When the night is down, the values fall below those: 42.2% on Monday, 49.3% on Tuesday, 44.0% on Wednesday, 46.0% on Thursday and 47.0% on Friday, with the same ES samples.
All of these figures orbit around one half. Put plainly: knowing the night's direction barely tilts the balance of the day, and it certainly does not decide it. It is context data, not a filter that works on its own.
Does the overnight direction continue in the regular session?
ES
Swipe to see the sample →
| Day | Overnight up | Overnight down | Sessions |
|---|---|---|---|
| Monday | 53.4% | 42.2% | 801 |
| Tuesday | 53.6% | 49.3% | 838 |
| Wednesday | 50.8% | 44.0% | 832 |
| Thursday | 53.0% | 46.0% | 831 |
| Friday | 56.5% | 47.0% | 770 |
n = 4,072 · 2010-06-07 to 2026-09-15 · historical futures data
Overnight direction = from yesterday's regular close to today's open. The percentage is how often today's regular session then moved in that same direction.
The night's range: what happens if it is still intact at 10:00#
The night's direction tells you little. Its range, on the other hand, works as a reference. Here the overnight range is the Globex high and low from 18:00 New York time the previous day (Sunday 18:00 for Monday) to 9:29, on the same contract as the regular session. It leaves out the hour after the regular close, 16:00 to 18:00, and it is a different window from the previous table, which runs from yesterday's close to today's open.
The question is what happens when, at 10:00, price has not yet taken out the night's high or its low during the first half hour. In ES, on those days the session closed inside the overnight range 51.2% of the time, over 1,858 sessions. Across all days it does so 42.8% of the time, over 4,195, and when at least one extreme was already taken before 10:00, 36.1%, over 2,337.
NQ gives almost the same: 50.8% with the night intact, over 1,352 sessions, against a 38.7% baseline and 32.9% with one extreme taken. That is nine points above the usual in ES and twelve in NQ, and it is something you can check every day at 10:00.
It says where the close ended up, not where price travelled in between, and it gives no direction: with the night intact, ES closed above the range 27.8% of the time and below it 21.0%. Days that take both extremes before 10:00 are rare, 21 in ES and 92 in NQ, so they are grouped with the one-extreme days.
Rango nocturno y apertura: qué pasó si a las 10:00 no se tomó ningún extremo
ES, NQ
Swipe to see the sample →
| Situación a las 10:00 ET | Cierra dentro del rango nocturno | Cierra por encima | Cierra por debajo | Días |
|---|---|---|---|---|
| ES · ningún extremo tomado a las 10:00 | 51.2% | 27.8% | 21.0% | 1,858 |
| ES · al menos un extremo tomado | 36.1% | 36.9% | 27.0% | 2,337 |
| ES · todos los días (base) | 42.8% | 32.9% | 24.3% | 4,195 |
| NQ · ningún extremo tomado a las 10:00 | 50.8% | 27.4% | 21.7% | 1,352 |
| NQ · al menos un extremo tomado | 32.9% | 38.6% | 28.5% | 2,843 |
| NQ · todos los días (base) | 38.7% | 35.0% | 26.3% | 4,195 |
n = 8,390 · 2010-06-07 to 2026-10-05 · historical futures data
Rango nocturno = máximo y mínimo de la sesión electrónica desde las 18:00 ET del día anterior (domingo 18:00 para el lunes) hasta las 09:29 ET, en el mismo contrato que la sesión regular; no incluye la hora posterior al cierre regular (16:00-18:00 ET). «Tomado a las 10:00» = la primera media hora regular (09:30-09:59 ET) superó el máximo o perdió el mínimo nocturno. Cierre = último precio de la sesión regular (16:00 ET). Datos de 1 minuto, sin costos.
Two famous effects, before and after they became public#
Two time-of-day effects came out of serious studies and are still taught. The first is the overnight drift in the S&P: the idea that price rises between 2:00 and 3:00, New York time. The second, that the last half hour of the session follows the direction the day already had.
Both were real in the period in which they were described. In ES, that hour moved +1.5 basis points per session on average between 2010 and 2020. The last half hour, +1.7 basis points between 2010 and May 2020.
After they became public, in ES they can no longer be told apart from zero: -0.3 basis points for the overnight drift in 2021-2025 and -0.4 for the last half hour since June 2021.
And both were always smaller than what it costs to trade them: over the whole history, one tick per side plus the commission exceeds the average size of each one (4,183 sessions for the overnight drift and 4,069 for the last half hour).
An honest nuance: in the 10-year note the last half hour can still be told apart before costs (+0.4 and then +0.8 basis points), but it is worth a fraction of a tick, less than the cost of trading it. 'No longer distinguishable' applies to the index futures.
Two famous effects, before and after they became public
ES, ZN
Swipe to see the sample →
| Effect, market and periods | In the period in which it was described (bp per session) | After it became public (bp per session) | Net of costs, whole history (bp per session) | Sessions |
|---|---|---|---|---|
| Overnight drift of the S&P between 2:00 and 3:00 ET (ES): 2010-2020 and, afterwards, 2021-2025 | 1.5 pb | -0.3 pb | -1.4 pb | 4,183 |
| The last half hour follows the rest of the day (ES): 2010-May 2020 and, afterwards, Jun 2021-Oct 2026 | 1.7 pb | -0.4 pb | -1.5 pb | 4,069 |
| The last half hour follows the rest of the day, 10-year note (ZN): 2010-May 2020 and, afterwards, Jun 2021-Oct 2026 | 0.4 pb | 0.8 pb | -2.4 pb | 4,003 |
n = 12,255 · 2010-06-07 to 2026-10-09 · historical futures data
ES (S&P 500) and ZN (10-year US Treasury note) futures, 1-minute bars of the front contract, from 7-Jun-2010 to 9-Oct-2026; times in ET; bp = basis points of price (1 bp = 0.01%) per session; the n in the footer adds the three rows. These are two effects that have been described in the literature. Overnight drift: buy at 2:00 and sell at 3:00. Last half hour: trade the last half hour of the session (15:30-16:00 on ES, 14:30-15:00 on ZN) in the direction the price had been taking since the previous close. 'In the period in which it was described' = the part of the described sample that these data cover: 2010-2020 for the overnight drift and 2010 to May 2020 for the last half hour. 'After it became public' = 2021-2025 for the overnight drift (the period over which its disappearance was later described) and June 2021 to October 2026 for the last half hour. The first two columns are before costs; the third subtracts 1 tick per side and USD 4.50 of round-trip commission, over the whole history, and the Sessions column is that of the whole history. With 95% confidence intervals (resampling by weeks). Overnight drift on ES: +1.53 [0.86 to 2.22] bp (n = 2,694) and afterwards −0.26 [−0.97 to 0.41] (n = 1,289); from October 2023, once formally published, +0.36 [−0.34 to 1.09] (n = 780); net of costs, −1.57 [−2.23 to −0.89] even in 2010-2020 and −1.44 [−1.90 to −0.96] over the whole history. Last half hour on ES: +1.68 [0.55 to 3.00] (n = 2,483) and afterwards −0.42 [−1.82 to 0.92] (n = 1,337); net, −1.50 [−2.65 to −0.18] in the first period and −1.52 [−2.33 to −0.64] over the whole history. On ZN: +0.39 [0.16 to 0.61] (n = 2,437) and afterwards +0.79 [0.41 to 1.15] (n = 1,320): there it can still be told apart from zero before costs, but it is worth a fraction of a tick (net, −2.33 [−2.71 to −1.97] from June 2021) and since that date it comes from the last 5 minutes before 15:00 (+0.51 bp) and is given back in the next 5 (−0.49 bp). Reading: both effects were real in the period in which they were described, neither ever covered the cost of trading it and in the index futures they can no longer be told apart from zero. It is what happened, not a signal.
What changes in your levels depending on the session you choose#
The Initial Balance, which is the range of the first sixty minutes of the regular session, only makes sense with a defined opening time. Computed on the full session it stops measuring what its name says.
The same goes for the Value Area and the POC. Including the night adds hours of low volume that shift the day's most traded price. Two charts of the same contract can show a different POC just because of that choice.
And the gap depends entirely on the reference. Measured against the prior regular close it gives one number; measured against the last early-morning price it gives another. Before comparing two statistics, confirm that both use the same session.
What this measurement does not say#
The distribution of extremes does not say at exactly which minute the high occurred within each segment, nor how far it stood from the rest of the day. A session can set its high in Asia by a few points and spend the rest of the day far from there.
It also says nothing about profitability. That the extreme forms outside the regular session does not mean it can be traded there at the same cost: on Globex the spread is wider and book depth is lower.
Period biases weigh in. The range runs from June 2010 to September 2026 and mixes very different regimes. The continuation by day of the week splits 4,072 ES sessions into five boxes, so a difference of a couple of points between neighboring days should not be read as a rule.
Finally, the segment hours are a convention. Moving the London cutoff by half an hour redistributes extremes from one column to another without the market having changed anything.
How to work with both sessions#
A reasonable routine uses RTH for structural levels and Globex for context: where price moved while you were not watching, what range the night left and where the open stood relative to the prior close.
Document the definition next to each figure, just like the sample. A futures statistic without a declared session is not reproducible and, therefore, not comparable with any other.
This text is informational material on how to read market data. It is not personalized investment advice or a recommendation on any instrument. Past results do not anticipate future ones, and trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- What are the ES regular session hours?
- 9:30 to 16:00 New York time, on US stock market business days. The rest of the 24-hour cycle is the extended electronic session.
- What does Globex mean in futures?
- Globex is CME's electronic platform and, by extension, the name used for the session that takes place outside regular hours. It is the same contract, with less volume and wider spreads.
- At what time does the day's high form in ES?
- Over 4,175 ES sessions, 48.1% of daily highs form inside the New York regular session, and 18.7% in its first two hours, while London is still open. The European morning before it contributes 18.3%, Asia 15.5% and the off-session minutes 18.0%.
- Does the overnight session's direction predict the day's?
- Barely. In ES, when the night is up, the regular session continues in that direction between 50.8% of the time on Wednesday, over 832 sessions, and 56.5% on Friday, over 770. It is too close to one half to treat as a rule.
- Is the overnight range a useful reference for the day?
- More than its direction. In ES, if at 10:00 New York time price has not yet taken out the night's high or low, the session closed inside that range 51.2% of the time, over 1,858 sessions, against 42.8% across all days. It does not say whether the close will be above or below.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- Base-rate reports — 18 core reports and 24 more in the archive across 30 instruments, every figure with n, period and caveats.
- Today, macro data, alerts and risk calculator — Today, economic calendar, alerts and a risk calculator for 30 contracts.
The calculation and its limits are in the methodology.
Take it to your chart, free
IB and gap: How often did a gap like today's fill?
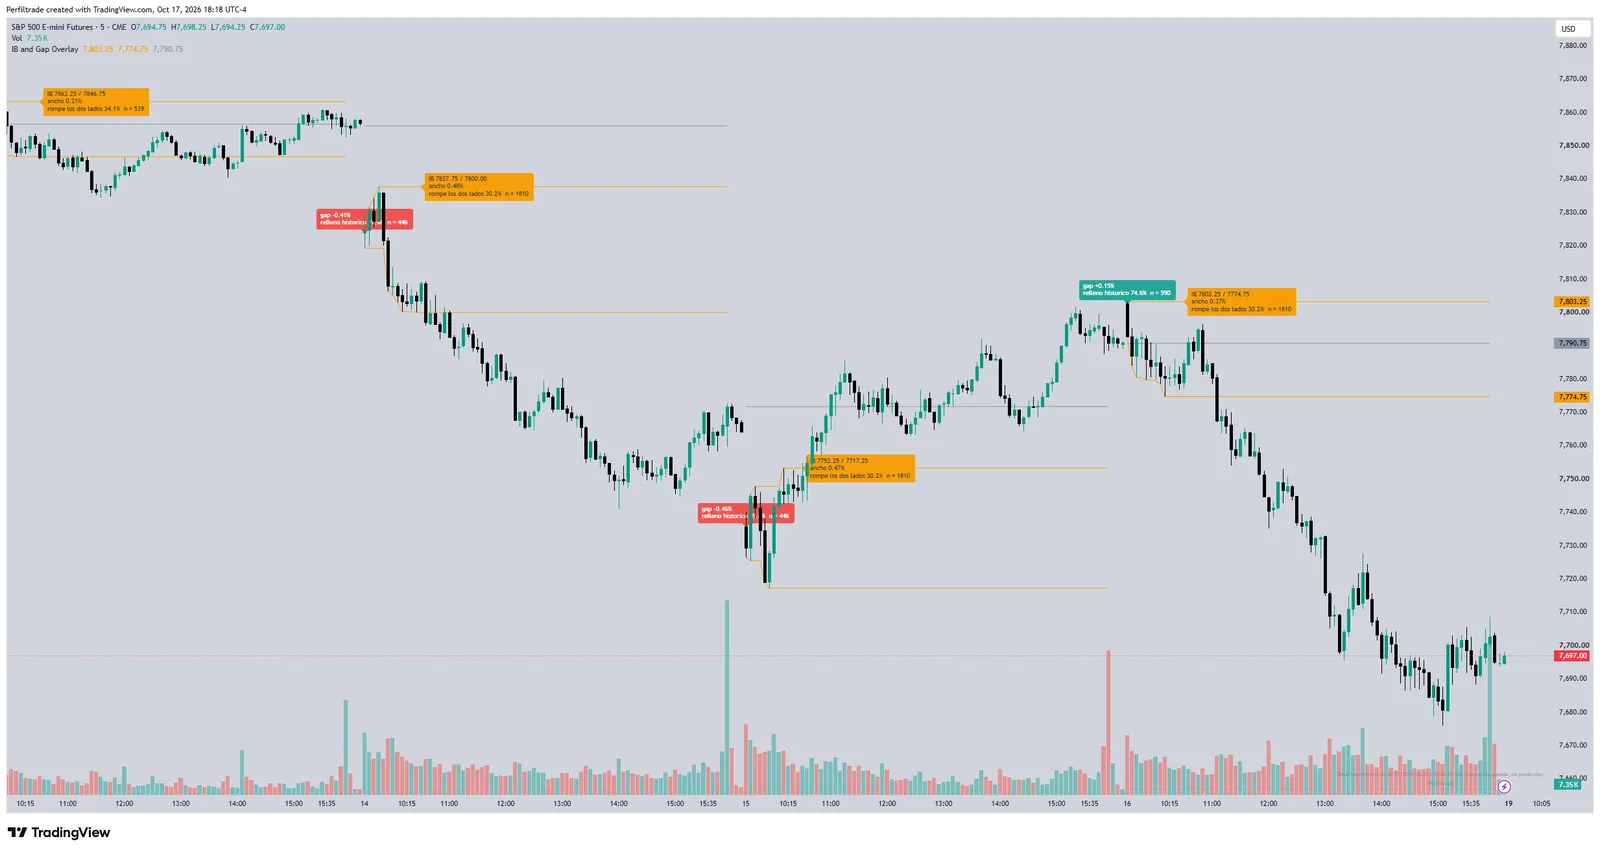
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). RTH vs Globex in Index Futures: What Changes. https://www.perfiltrade.com/en/learn/rth-vs-globex-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →