Opening Gap in Index Futures: A Data-Driven Guide
Updated October 16, 2026
What exactly an opening gap is#
An opening gap is the distance between the price at which the regular session opens and the price at which the previous regular session closed. If the open is above that close, the gap is up. If it is below, the gap is down. The word sounds technical, but it describes a subtraction.
In index futures the nuance matters more than in stocks, because the contract almost never stops trading. Between the 4:00 p.m. New York close and the 9:30 a.m. open, price keeps moving. The gap is not a void: it is a stretch that traded outside the main hours.
That is why the reference should be fixed before measuring anything. In these tables the gap always runs from the previous regular close to today's regular open. Another choice, such as the last overnight price, produces another number and another statistic.
What it means for a gap to fill#
Filling the gap means price touches the previous regular session close again. Here, it also has to do so within the same regular session. If it touches it the next day, it counts as not filled.
That time cutoff is a decision, not a law of the market. Giving price three days to come back yields much higher percentages that are much less useful for anyone trading intraday. When you compare figures across sources, match the window first.
The second decision is what counts as a touch. It is enough for price to return to the level, with no requirement of a close beyond it or of staying there. It is the loosest possible definition, and even so many gaps do not make it.
The definition matters when you compare. Higher fill rates circulate for these same indices, and they almost always measure something else: the calendar-day gap in a contract that trades nearly 24 hours, which is tiny and closes almost always, or a touch at any later point rather than inside the same regular session. Neither is wrong; they measure a different event. Here the gap is measured against the prior regular-session close and the fill has to happen inside that same day's regular session.
Gap size changes the whole result#
If you could keep only one variable of gap analysis, it would be size. The table sorts ES sessions by the magnitude of the gap, as a percentage of price, and the result tilts from one extreme to the other.
Tiny gaps, from 0 to 0.1%, fill 90.4% of the time when up and 92.3% when down, over 781 ES sessions. In the 0.1 to 0.25% band, with 1,068 sessions, the values drop to 74.4% and 74.5%.
At the other extreme the picture reverses. Gaps of more than 1% fill 18.6% of the time when up and 22.0% when down, and the sample there is only 379 ES sessions. The crossover happens in the intermediate 0.25 to 0.5% band, with 1,069 sessions: 51.1% up and 59.9% down.
There is a boring explanation behind it. A small gap is close by definition, and price passes through there almost without trying. A large gap demands a long move against it. The table does not uncover an anomaly: it describes a distance.
Gap fill by gap size
ES
Swipe to see the sample →
| Gap size | Gap up | Gap down | Sessions |
|---|---|---|---|
| 0-0.1% | 90.4% | 92.3% | 781 |
| 0.1-0.25% | 74.4% | 74.5% | 1,068 |
| 0.25-0.5% | 51.1% | 59.9% | 1,069 |
| 0.5-1.0% | 33.9% | 32.2% | 775 |
| >1.0% | 18.6% | 22.0% | 379 |
n = 4,072 · 2010-06-07 to 2026-09-15 · historical futures data
Gap measured from the prior regular-session close (16:00 ET) to today's open (9:30 ET). Fill = price trades back to that close within the same regular session. Zero gaps are excluded.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The same gap, five different indices#
Here is the finding most worth internalizing. With the same definition and the same period, the gap up fills 58.3% of the time in the ES, over 4,072 sessions, and only 40.6% in the NKD, over 4,062 sessions.
The other three sit close to the ES, and all of them well above the NKD. The NQ fills 60.3% of up gaps and 64.2% of down gaps, over 4,099 sessions. The RTY shows 63.0% and 62.2% over 2,321 sessions, a considerably smaller sample. The YM sits at 57.6% and 62.2% over 4,096 sessions.
The conclusion is uncomfortable for headlines: a gap fill figure that does not say which instrument it comes from tells you nothing. Carrying the ES number over to the NKD, or the other way around, changes the expectation completely, and the contrast is not explained by sample size, because both are similar.
The same gap, five instruments
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Gap up | Gap down | Sessions |
|---|---|---|---|
| ES | 58.3% | 61.3% | 4,072 |
| NQ | 60.3% | 64.2% | 4,099 |
| RTY | 63.0% | 62.2% | 2,321 |
| YM | 57.6% | 62.2% | 4,096 |
| NKD | 40.6% | 43.1% | 4,062 |
n = 18,650 · 2010-06-07 to 2026-09-15 · historical futures data
The same measurement applied to each index. Differences between instruments are why a bare figure, without saying which market it comes from, is useless.
Measured in ATR, ES and NQ almost match#
A percentage of price is not the only way to measure a gap. Another is to divide it by the average true range of the last 14 sessions (ATR): that way a gap of the same relative size weighs the same on a quiet day as on a nervous one, and in an index that moves a lot as in one that moves little.
Measured that way, in the regular session from 2010-06-28 to 2026-10-16, gaps under 0.1 ATR filled 91.7% of the time in ES and 90.9% in NQ; gaps of 0.1 to 0.25 ATR, 70.9% and 71.8%; gaps of 0.25 to 0.5 ATR, 47.5% and 47.8%. Between 0.5 and 1 ATR it drops to 23.5% in ES and 28.0% in NQ, and above 1 ATR to 8.3% (n=120) and 15.0% (n=100).
As a percentage of price, NQ and ES do not give the same result; in ATR, in the first three buckets, they almost do. Much of the difference between the two indices is simply that NQ moves more. One caveat: the 0.5 to 1 ATR bucket in ES has not been stable, moving from 20.7% through 2021 to 30.3% since 2022.
As in the previous table, 'fills' means trading yesterday's close before 16:00 ET, without saying how far price went first or when it came back. Up and down gaps are counted together here.
How often the gap fills by its size in ATR: ES and NQ
ES y NQ
Swipe to see the sample →
| Gap size | ES | NQ | Sessions |
|---|---|---|---|
| Under 0.1 × ATR | 91.7% | 90.9% | 916 |
| 0.1 to 0.25 × ATR | 70.9% | 71.8% | 1,231 |
| 0.25 to 0.5 × ATR | 47.5% | 47.8% | 1,167 |
| 0.5 to 1 × ATR | 23.5% | 28.0% | 647 |
n = 4,081 · 2010-06-28 to 2026-10-15 · historical futures data
Regular session (9:30-16:00 ET), 28-Jun-2010 to 15-Oct-2026: 4,081 gaps in ES and 4,108 in NQ. Gap = today's open minus yesterday's regular-session close, measured in multiples of the 14-session ATR known at the open. 'Fills' = the session trades yesterday's close before 16:00 ET. Up and down together; contract-roll days excluded. The 'Sessions' column is ES's; NQ's are, by bucket, 1,015, 1,220, 1,156, 617. Gaps above 1 ATR filled 8.3% of the time in ES (n=120) and 15.0% in NQ (n=100). In ES, the 0.5-1 ATR bucket went from 20.7% up to 2021 to 30.3% since 2022; the other buckets were stable across both periods. Measured this way, ES and NQ agree in the first three buckets; measured as a percent of price, they do not. It is what happened, not a signal.
Outside yesterday's range and Fed days, at the same size#
Two questions keep coming up: does it matter that the open lands outside yesterday's range, and that it is a release day? So as not to mix them up with size, each day is compared with what days in its same ATR bucket and same direction filled.
Opening outside yesterday's range subtracts: in the ES, 43.6% of those gaps filled against 48.1% expected for their size, 4.5 points less, over 1,710 days; in the NQ, 46.4% against 51.2%, over 1,649. Fed decision days add: in the ES, 78.0% against 64.5% expected, over 127 days.
CPI and payrolls cannot be told apart from an ordinary day of their size: 56.2% against 53.2% in the ES and 56.7% against 56.3% in the NQ, over 372 days each. What does change on those days is the size of the gap, not how often it fills.
The study runs 94 comparisons. Corrected for that number, only three hold: ES and NQ outside yesterday's range, and ES on Fed days. NQ on Fed days (73.6% against 63.1%, over 129) does not hold after the correction.
How often the gap fills by context, against what its size would predict: ES and NQ
ES y NQ
Swipe to see the sample →
| Context | Fills (observed) | 95% interval | Expected for its size | Difference (points) | z | Days |
|---|---|---|---|---|---|---|
| ES, opens outside yesterday's range | 43.6% | 41.3-46.0% | 48.1% | -4.5 | -4.1 | 1,710 |
| NQ, opens outside yesterday's range | 46.4% | 44.0-48.8% | 51.2% | -4.8 | -4.2 | 1,649 |
| ES, FOMC decision day | 78.0% | 70.0-84.3% | 64.5% | 13.5 | 3.7 | 127 |
| NQ, FOMC decision day | 73.6% | 65.4-80.5% | 63.1% | 10.5 | 2.8 | 129 |
| ES, CPI or employment-report day | 56.2% | 51.1-61.1% | 53.2% | 3 | 1.3 | 372 |
| NQ, CPI or employment-report day | 56.7% | 51.6-61.7% | 56.3% | 0.4 | 0.2 | 372 |
n = 4,081 · 2010-06-28 to 2026-10-15 · historical futures data
Regular session (9:30-16:00 ET), 28-Jun-2010 to 15-Oct-2026: 4,081 gaps in ES and 4,108 in NQ; contract-roll days excluded. Gap = today's open minus yesterday's regular-session close, measured in multiples of the 14-session ATR known at the open (today's session not included). 'Fills' = the session trades yesterday's close before 16:00 ET. 'Opens outside yesterday's range' = the open is above the high or below the low of yesterday's regular session. 'Expected for its size' = each day is given the fill rate that the comparison days had in its same size bucket (under 0.1; 0.1 to 0.25; 0.25 to 0.5; 0.5 to 1; over 1 ATR) and its same direction (up or down gap), and those rates are averaged: for the days that open outside, the comparison is the days that opened inside yesterday's range; for release days, the days with no CPI, employment report or FOMC decision. So the difference does not come from those days having larger or smaller gaps. The interval is the 95% interval of the observed rate. z = (observed fills minus expected) divided by the square root of the sum of each day's p(1-p), against that stratified expectation. The study computed 94 comparisons across ES and NQ; with a Holm correction at 5% over all of them, ES outside the range, NQ outside the range and ES on FOMC days hold up; NQ on FOMC days, ES on CPI or employment days and NQ on CPI or employment days do not. It is what happened, not a signal.
Day of the week adds less than it seems#
The calendar also sorts the figures, though less strongly than size. In the ES, Monday is the day with the least filling of up gaps: 50.8% over 801 sessions. That same Monday fills 56.2% of down gaps.
Wednesday sits on the other side of the table, with 64.3% filling for up gaps and 68.4% for down gaps over 832 sessions. In between are Tuesday, with 59.5% and 60.1% over 838 sessions; Thursday, with 59.6% and 62.8% over 831; and Friday, with 56.2% and 59.2% over 770.
Before drawing a rule from Monday, remember where the data comes from. Monday's gap accumulates the whole weekend of news, so it tends to be larger. The day column may be showing the size effect again, disguised as calendar.
Gap fill by day of the week
ES
Swipe to see the sample →
| Day | Gap up | Gap down | Sessions |
|---|---|---|---|
| Monday | 50.8% | 56.2% | 801 |
| Tuesday | 59.5% | 60.1% | 838 |
| Wednesday | 64.3% | 68.4% | 832 |
| Thursday | 59.6% | 62.8% | 831 |
| Friday | 56.2% | 59.2% | 770 |
n = 4,072 · 2010-06-07 to 2026-09-15 · historical futures data
Same gap and fill definition as the size table, split by day of the week.
What these figures do not measure#
They do not measure how painful the path is. A session can fill the gap after moving hard against you, and it counts the same as one that fills it in the first minute. There is also no data on time to fill.
They do not measure profitability. A high fill percentage says nothing about commissions, slippage or stop size. The 90.4% for tiny ES gaps comes with a tiny move: the hit is frequent and small at the same time.
And they carry the biases of their period, from June 2010 to September 2026, sixteen years in which U.S. indices rose much more than they fell. Large gaps, moreover, are not spread evenly: they cluster in episodes of stress, so those sessions are far from independent of one another.
How to use it in your preparation, without turning it into a signal#
A historical percentage serves to calibrate expectations before the open, not to trigger an order. Seeing that today's gap falls in the ES band of more than 1% changes what is reasonable to expect from the day; it does not tell you what to do with it.
The useful routine is simple: identify the instrument, measure the gap with a single definition, place it in its size band, and note the sample of that cell. If it has few observations, treat it as a hint and not as hard data.
This content is informational and educational material on reading market data. It is not personalized investment advice, and historical behavior does not anticipate that of upcoming sessions. Trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Do all gaps close on the same day?
- No. In the ES, gaps of more than 1% filled within the same regular session 18.6% of the time when up and 22.0% when down, over 379 sessions. The frequency rises a lot when the gap is small.
- What percentage of gaps fill in the ES?
- Taking all sessions with a gap, the ES fills 58.3% of up gaps and 61.3% of down gaps, over 4,072 sessions. That average hides huge differences depending on gap size.
- Which day of the week do the most gaps fill?
- In the ES it is Wednesday, with 64.3% up and 68.4% down over 832 sessions. Monday is the lowest for up gaps, at 50.8% over 801 sessions. Part of that difference may come from gap size, which tends to be larger on Monday.
- How do you measure a gap in futures that trade almost 24 hours?
- You have to pick a fixed reference and not change it. Here the previous regular session close, at 4:00 p.m. New York time, is used against the 9:30 a.m. open. Using the last overnight price gives another gap and another statistic.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- Base-rate reports — 18 core reports and 24 more in the archive across 30 instruments, every figure with n, period and caveats.
The calculation and its limits are in the methodology.
Take it to your chart, free
IB and gap: How often did a gap like today's fill?
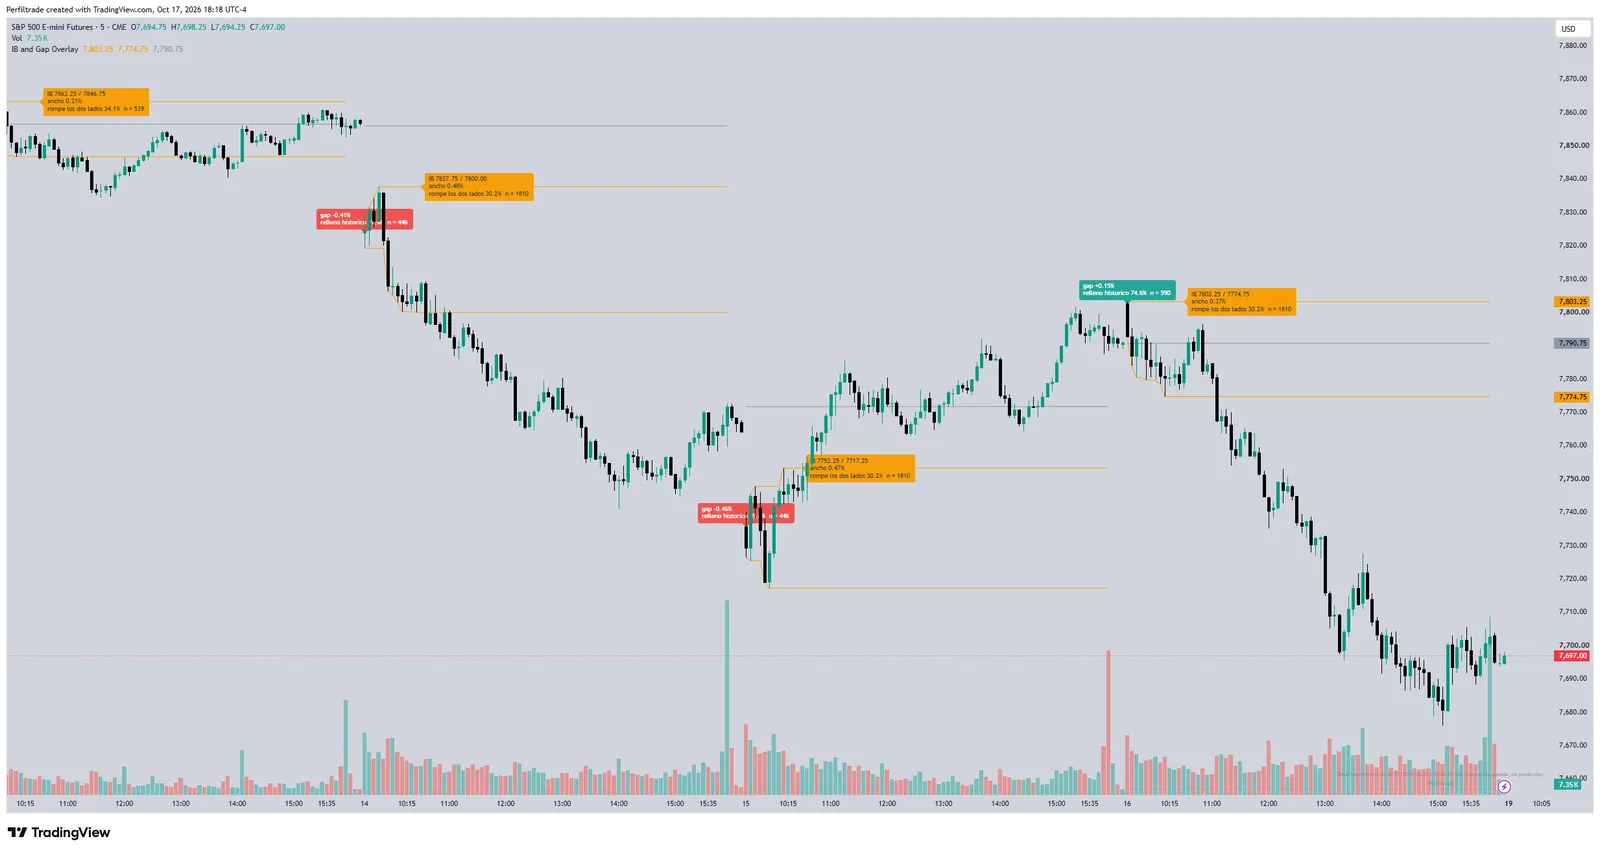
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 16, 2026). Opening Gap in Index Futures: A Data-Driven Guide. https://www.perfiltrade.com/en/learn/opening-gap-index-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →