Initial Balance: What It Is and How to Use It Intraday
Updated October 6, 2026
What the Initial Balance is#
The Initial Balance, abbreviated IB, is the high and low price sets during the first sixty minutes of the regular session. Nothing more. It is a rectangle defined by two prices and a cutoff time.
The regular session, or RTH, is the U.S. stock exchange's trading hours: 9:30 a.m. to 4:00 p.m. New York time. In index futures such as ES and NQ, the Initial Balance therefore runs from 9:30 to 10:30 a.m. in that same time zone.
It gets attention because that first hour concentrates the day's position opening and the reaction to what happened overnight. The range that comes out of it ends up working as a frame of reference for the rest of the day.
How it is calculated and what to fix beforehand#
The calculation is no mystery: the high and low of the first sixty-minute period. The delicate part is the decisions made beforehand, because they change the number.
You have to fix the session (regular or full), the time zone, the calendar of holidays and half-days, and which contract to use when an expiration is near. Two different definitions produce different Initial Balances for the same day, and their statistics stop being comparable.
That is why every figure about the IB should come with its definition, its sample and its period. Without those three things, a percentage is just a sentence with numbers in it.
Breaking the IB is not the same as closing outside it#
The usual question is whether an Initial Balance break continues. To answer it you have to separate two measures: how many times price leaves the range, and how many times the session ends beyond the extreme it broke. They are often confused and they are not the same thing.
The table measures the second one on ES. Across all recorded breaks, it calculates how often the close ended up on the far side of the broken level, split by day of the week.
It is best read with the breaks column in front of you. Each row rests on more than a thousand cases, which makes the differences between days more stable than in tables with few observations.
Initial Balance break and close beyond the level
ES
Swipe to see the sample →
| Day | Breaks the high | Breaks the low | Breaks |
|---|---|---|---|
| Monday | 54.9% | 43.6% | 1,000 |
| Tuesday | 54.5% | 46.6% | 1,061 |
| Wednesday | 51.6% | 48.7% | 1,109 |
| Thursday | 56.6% | 43.9% | 1,047 |
| Friday | 57.4% | 47.7% | 1,009 |
n = 5,226 · 2010-06-07 to 2026-09-15 · historical futures data
IB = range of the first 60 minutes of the regular session (9:30-10:30 ET). The percentage is how often the session closed beyond the broken extreme, not how often a break happened.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
What shows up by day of the week#
A break of the Initial Balance high ends with a close above the level in 57.4% of the 1,009 Friday breaks in ES, and in 56.6% of the 1,047 Thursday breaks. Wednesday is the weakest: 51.6% across 1,109 breaks.
To the downside the picture is different. A break of the low ends with a close below in 48.7% of the 1,109 Wednesday breaks in ES and in 43.6% of the 1,000 Monday breaks. Every day falls below 50%.
That asymmetry between up and down runs through the entire table, and it fits a long series of an index that rose over the period as a whole. It is not a property of the Initial Balance: it is the market's own drift creeping into the measurement.
None of these figures is enough to support a rule on its own. The highest, 57.4%, describes little more than a slight imbalance, and that is before subtracting costs.
IB size changes the shape of the day#
The second table splits ES sessions by the size of the Initial Balance, measured as a percentage of price, and looks at what the rest of the day did: break only one side, break both, or stay inside the range.
The trend is orderly. With a very narrow IB, from 0 to 0.25%, the day breaks both sides in 34.1% of 533 ES sessions. With an IB of 1.0 to 1.5%, that figure drops to 18.1% across 293 sessions.
The reverse reading also holds: breaking only one side goes from 64.2% with a narrow IB, across 533 ES sessions, to 76.1% in the 1.0 to 1.5% bracket, across 293 sessions. A wide IB tends toward a more directional day; a narrow one, toward a day that rotates within the range.
Staying inside the Initial Balance all day is rare in any bracket: 1.7% in the narrowest, across 533 ES sessions, and 5.8% in the 1.0 to 1.5% bracket, across 293 sessions.
What the day does by Initial Balance size
ES
Swipe to see the sample →
| IB size | Breaks one side | Breaks both sides | No break | Sessions |
|---|---|---|---|---|
| 0-0.25% | 64.2% | 34.1% | 1.7% | 533 |
| 0.25-0.5% | 68.3% | 30.1% | 1.6% | 1,796 |
| 0.5-0.75% | 73.8% | 23.7% | 2.6% | 1,014 |
| 0.75-1.0% | 72.5% | 23.5% | 4.0% | 455 |
| 1.0-1.5% | 76.1% | 18.1% | 5.8% | 293 |
| 1.5-2.0% | 70.2% | 29.8% | 0.0% | 57 |
| >2.0% | 70.6% | 20.6% | 8.8% | 34 |
n = 4,182 · 2010-06-07 to 2026-09-15 · historical futures data
IB size as a percentage of price. A narrow IB breaks both sides more often (more rotation); a wide one tends to break only one side.
What IB size does not decide#
The table says how the range is broken, not in which direction. None of its columns distinguishes an upside break from a downside one, so it offers nothing about direction.
It also does not say how much room there is after the break. A day that breaks one side can extend a long way or only a few points. That distance is what decides whether an idea is viable, and it is not in this table: the extensions table, further down, measures it.
The extreme brackets call for extra caution. The 1.5 to 2.0% bracket has 57 ES sessions and the one above 2.0% has 34. With samples like that, the ordering can change with just a few new days, and in fact they already break the progression seen in the rest of the table.
Thirty or sixty minutes, wick or close#
Two decisions that almost nobody states change the answer completely: how long the IB lasts and what counts as a break. The table measures all four combinations on the same ES sessions, from 2010-06-07 to 2026-10-05.
With the sixty-minute IB and a wick break, price exceeds both extremes in 27.5% of 4,195 sessions. If a five-minute candle has to close beyond the level, that drops to 19.1%. With a thirty-minute IB, breaking both sides rises to 45.7% by wick and 33.8% by close, across 4,196 sessions.
The reason is mechanical. A shorter range sits closer to price for the rest of the day, so it gets touched sooner and more often; requiring a close filters out one-tick touches. No version is the correct one: what you cannot do is compare a figure measured by wick with one measured by close as if they were the same statistic.
The Initial Balance by its length and by how the break is counted
ES
Swipe to see the sample →
| Variant | Breaks one side | Breaks both sides | No break | Sessions |
|---|---|---|---|---|
| 30-min IB, by wick | 53.9% | 45.7% | 0.4% | 4,196 |
| 30-min IB, by close | 64.9% | 33.8% | 1.3% | 4,196 |
| 60-min IB, by wick | 70.1% | 27.5% | 2.4% | 4,195 |
| 60-min IB, by close | 76.0% | 19.1% | 4.9% | 4,195 |
n = 4,196 · 2010-06-07 to 2026-10-05 · historical futures data
IB = range of the first 30 or 60 minutes of the regular session (from 9:30 ET). 'By wick': a break when any later 5-minute candle trades beyond the extreme; 'by close': only when a 5-minute candle closes beyond it. A shorter IB and the wick count break more often; always compare the same variant.
How far price went after the break#
This table answers a different question: on the days price broke the sixty-minute IB, how far it extended beyond the broken extreme, measured in multiples of the IB's own range. That is 4,093 ES breaks, from 2010-06-07 to 2026-10-05; if a day broke both sides, the larger extension counts.
With a narrow IB, 0 to 0.25% of price, half the breaks reached at least one full IB size (a median of 1.0) and one in four went past 1.81 times, across 527 days. With an IB of 1.0 to 1.5%, the median drops to 0.62 times and the 75th percentile to 1.07, across 276 days.
Measured in multiples, the narrow IB extends further; measured in points, not necessarily, because the starting range is smaller. The two widest brackets have small samples, 57 and 31 days, and their ordering can change with a few new sessions. The table describes what happened, not a target.
How far price went after breaking the Initial Balance, by IB size
ES
Swipe to see the sample →
| IB size | Median | 75th percentile | Days with a break |
|---|---|---|---|
| 0-0.25% | 1.0 × IB | 1.8 × IB | 527 |
| 0.25-0.5% | 0.8 × IB | 1.3 × IB | 1,774 |
| 0.5-0.75% | 0.7 × IB | 1.2 × IB | 990 |
| 0.75-1.0% | 0.6 × IB | 1.1 × IB | 438 |
| 1.0-1.5% | 0.6 × IB | 1.1 × IB | 276 |
| 1.5-2.0% | 0.6 × IB | 1.1 × IB | 57 |
| >2.0% | 0.6 × IB | 0.8 × IB | 31 |
n = 4,093 · 2010-06-07 to 2026-10-05 · historical futures data
Extension past the broken edge of the IB (60 minutes), in multiples of the IB range, on the days that broke it only; if both sides broke, the larger one counts. Half of the breaks went at least as far as the median and one in four as far as the 75th percentile. What happened, not a price target.
The limits of this measurement#
The Initial Balance is a time-based convention, not a level the market observes. The first hour matters out of habit and liquidity, not because that range has some special property. Measuring it with thirty minutes produces another table that is just as defensible, as the four-variant table shows.
The tables are ES. The first two cover 2010-06-07 to 2026-09-15, with 5,226 breaks and 4,182 sessions; the variants and extensions tables run to 2026-10-05, with 4,195 and 4,196 sessions in the first and 4,093 breaks in the second. They mix very different volatility regimes, and an average over so many years does not describe the particular month you are trading.
Three biases are present. Drift, already mentioned, which inflates the bullish side. Classification, which decides where a day that grazes the boundary between two brackets falls. And cost: no percentage subtracts spread, commissions or slippage, and all three easily eat up an imbalance this small.
Finally, none of these figures is conditional on the rest of the context. They do not separate a session with macro data from one without it, nor an open inside the prior value from one outside it.
How to fit it into a routine#
A sensible use is descriptive. Note the day's Initial Balance size and its position relative to the prior range, and use it to gauge how much room may be left, not to decide direction.
The second use is record-keeping. Saving what the session did against what you expected turns the table into something comparable with your own trading.
This content is informational material about reading historical data and does not constitute personalized investment advice. Past results do not predict future results, and trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- What happens if price does not break the Initial Balance all day?
- It is uncommon. In ES it happened in 1.7% of the 533 sessions with an IB of 0 to 0.25% and in 5.8% of the 293 sessions with an IB of 1.0 to 1.5%. It tends to coincide with contained-range days and low participation.
- How long does the Initial Balance last?
- Sixty minutes from the open of the regular session: in U.S. index futures, 9:30 to 10:30 a.m. New York time. Some people calculate it with thirty minutes, and then the statistics change a lot: in ES, price breaks both sides in 45.7% of sessions with a thirty-minute IB and 27.5% with a sixty-minute one, both by wick.
- Is the Initial Balance useful for trading NQ?
- It is calculated the same way in NQ and with the same hours. That said, the figures in this article are from ES and cannot be carried over to NQ without measuring again: different instruments produce different splits under the same definition.
- What changes if the IB break is measured by close instead of by wick?
- The figure drops considerably. With the sixty-minute ES IB, breaking both sides goes from 27.5% by wick to 19.1% when a five-minute candle has to close beyond the level, across 4,195 sessions. Before comparing two IB statistics, confirm they use the same definition.
- How far does price extend after breaking the Initial Balance?
- It depends on the IB's size. In ES, with an IB of 0 to 0.25% of price, the median extension beyond the broken extreme is 1.0 times the IB range, across 527 break days; with an IB of 1.0 to 1.5%, it is 0.62 times, across 276 days. It describes what happened, not a target.
- Does a narrow Initial Balance mean the day will be bigger?
- That is not what the data shows. In ES a narrow IB is mostly associated with breaking both sides, at 34.1% across 533 sessions, versus 18.1% in the 1.0 to 1.5% bracket across 293 sessions. That describes rotation, not the size of the move.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- Markets: price against the IB — Where price sits relative to the Initial Balance (above, below or inside), across 25 instruments.
- In-session Market Profile — Initial Balance, Value Area, POC and profile shape during the session, against their history.
- Alerts — Alerts by Telegram or webhook, each with its historical frequency and its n.
The calculation and its limits are in the methodology.
Take it to your chart, free
Setup State: What state are today's gap, Initial Balance and opening range in?
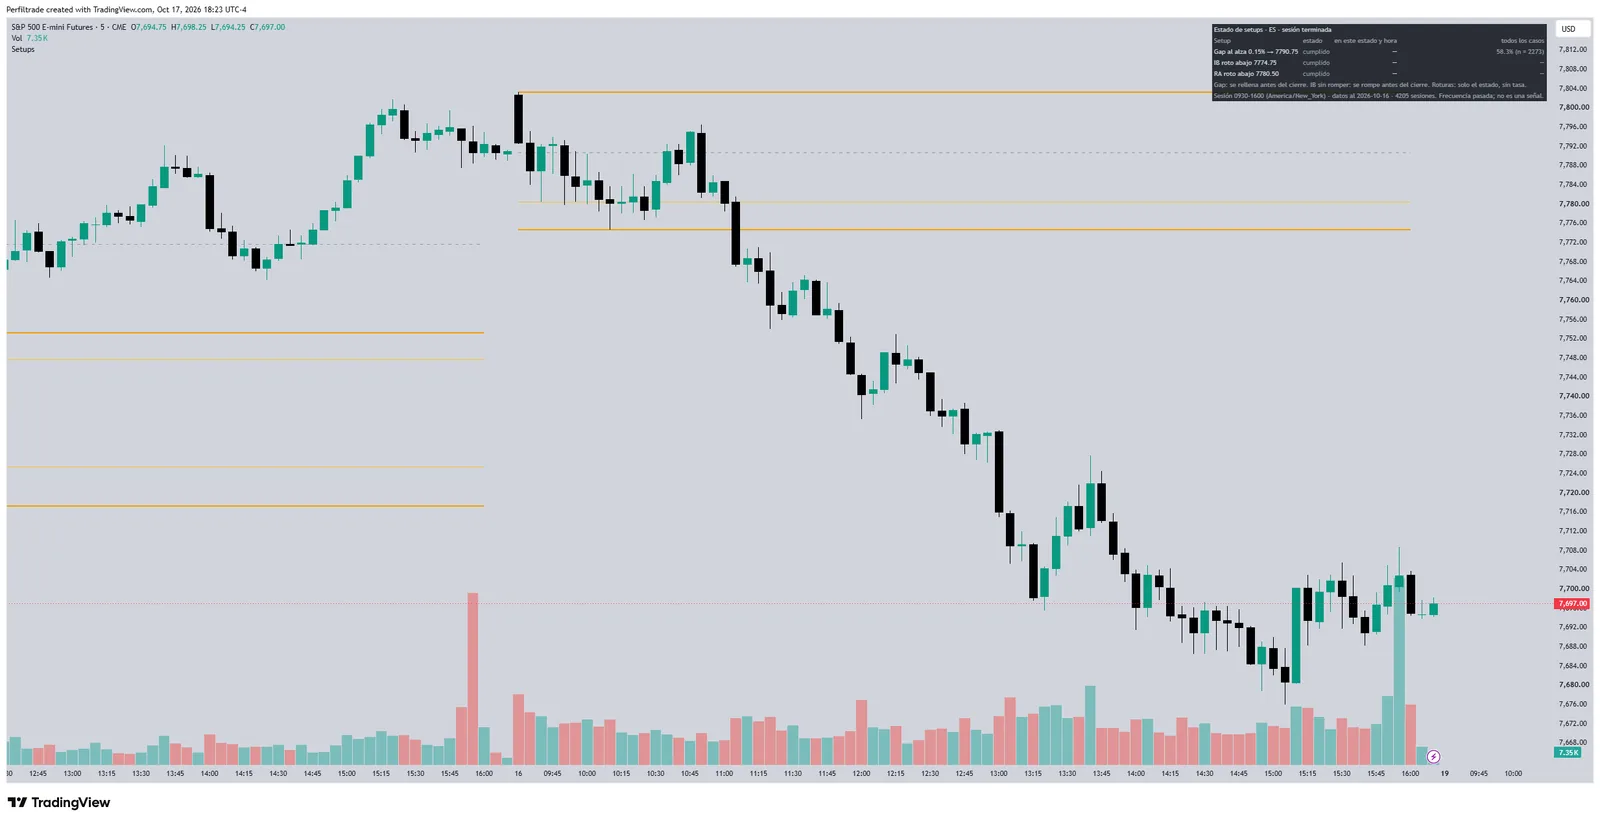
While the gap is open, how many past sessions that had it open at the same time of day filled it before the close, with the rate of all cases as the base.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 6, 2026). Initial Balance: What It Is and How to Use It Intraday. https://www.perfiltrade.com/en/learn/initial-balance-trading
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →