Monthly seasonality: almost no month departs from chance
Updated October 25, 2026
The question at the start of every month#
Every month the same question comes back: what does this month usually do? September has a bad name, 'sell in May' is almost a proverb and every commodity has its season.
We measured it on the thirty contracts we have: 5,408 complete months across indices, metals, energy, agriculture, currencies, rates and crypto, since 2010. Each month of each contract is compared with what is normal for that same contract, not with 50%.
A warning before the figures, because it shapes everything else: each month-and-contract combination rests on about sixteen years. With so few years, a single one moves the count a lot.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
How many special months chance produces#
There are 360 month-and-contract combinations. If none were special, with sixteen-year samples an ordinary statistical test would flag about 15 by pure chance.
It flags 9. Fewer than chance would give.
Those 9 are scattered with no pattern: different months in different contracts, and no month repeats across a whole family, which is what we would see if the calendar mattered.
Put plainly: with sixteen years per month, the monthly seasonality of these thirty futures cannot be told apart from noise. The table of a market with no seasonality would also have its 'strong' and 'weak' months.
Thirteen calendar effects, defined before looking#
Months are not the only calendar repeated in forums: the turn of the month, the pre-holiday session, 'sell in May', options-expiration week, the Christmas rally. To measure them without cheating ourselves, we first wrote down thirteen classic effects, each with a single window and the markets it is claimed for.
That makes 86 effect-and-market combinations. Testing so many at once, some come out well by chance: 14 look significant on their own, and about 4 were expected by pure chance. With a false-discovery control over the 86 together, 4 pass.
The 4 are the same effect: the end of the month in the four Treasury futures. The turn of the month in indices, options-expiration week, November-April against May-October and the sessions before Christmas and New Year do not hold up, among others.
It is what happened in the measured period: an effect passing the control does not say what next month will do.
What this study does not say#
It does not say seasonality exists in no market. It says sixteen years are not enough to see it month by month: with forty years of data some patterns might hold; with sixteen, they cannot be separated from luck.
It does not look at physical commodity seasons, such as planting or winter, which need their own contract-by-contract analysis.
And it does not exclude extreme years: in sixteen-year cells, a single year such as 2020 or 2022 weighs a lot.
October 2026 correction: the count was recalculated with complete months only, through September 2026, with currency data before 2016 cleaned and with the day defined as the trading day, which closes at 17:00 ET.
What to do with this at the start of the month#
Distrust any seasonal calendar that does not say how many years sit behind each cell. With sixteen, a month that 'almost always' did something is a month that did it twelve times out of sixteen, and chance produces that often.
And if a seasonal pattern convinces you, ask it the same question as any other: how many patterns like it would appear by chance in a table this size?
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Is one month better than another in ES?
- Not one that can be told apart from chance. In ES no month departs from what is normal for that contract, and across the thirty contracts only 9 of 360 month-and-contract combinations do, fewer than the 15 chance would give.
- Does the turn of the month or 'sell in May' work?
- In our measurement, no. Of thirteen calendar effects defined in advance and tested in 86 effect-and-market combinations, only the end of the month in Treasury futures passes the false-discovery control. The turn of the month in indices and November-April against May-October do not hold up.
- Is September a bad month?
- With sixteen years of data, September does not depart from what is normal in ES, the Nasdaq or gold: its reputation cannot be told apart from chance.
- What happens in October?
- In ES and the Nasdaq, October does not depart from what is normal for that contract. Across the thirty contracts only two October combinations do, the yen and the 30-year bond, within the 9 that fit inside what chance would give.
- Does seasonality work in futures?
- With sixteen years of data, it cannot be shown month by month. Of 360 month-and-contract combinations, 9 depart from what is normal for their contract; by pure chance about 15 would be expected.
- Why exclude the contract roll day?
- Because in the continuous futures series the switch from one expiry to the next produces a price jump that is not a market move. If it is left in, the expiry months inherit that jump. Here each month is computed close to close without that day.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
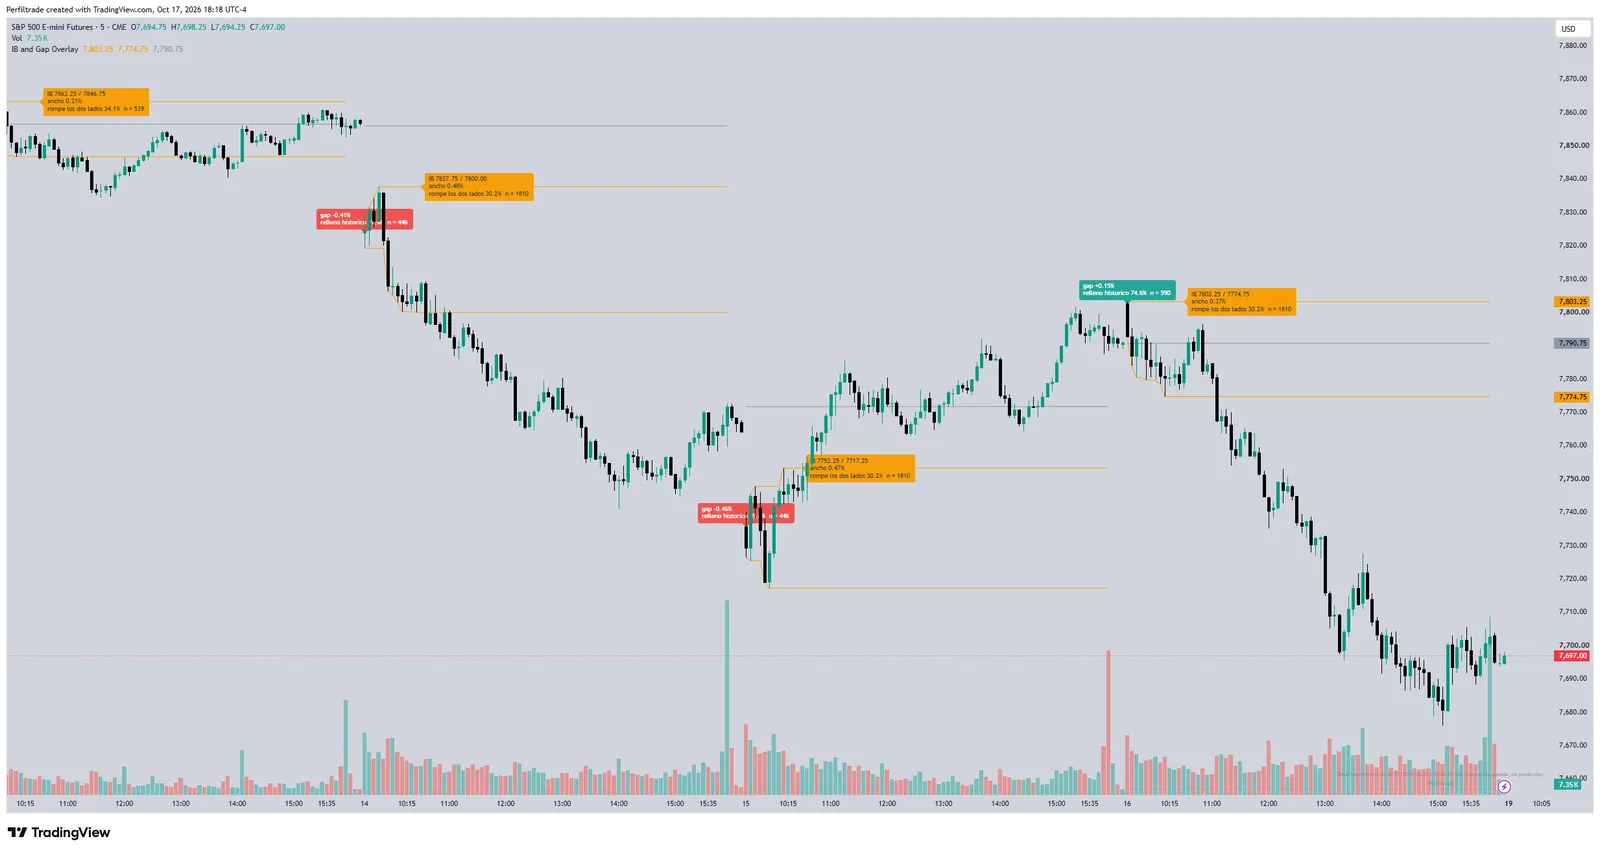
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 25, 2026). Monthly seasonality: almost no month departs from chance. https://www.perfiltrade.com/en/learn/futures-seasonality-by-month-thirty-contracts
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →