NQ Initial Balance Statistics
Updated October 12, 2026
What this NQ data sheet measures#
The Initial Balance, or IB, is the range between the high and the low of the first sixty minutes of the regular session, 9:30 to 10:30 New York time. Why that hour matters belongs to the general guide on the concept.
This is something else: the statistical sheet for the E-mini Nasdaq-100. Two tables measured on NQ alone, with 4,929 breaks in the first and 4,182 sessions in the second, from 7 June 2010 to 15 September 2026.
They do not answer what the Initial Balance is. They answer what NQ did after breaking it, and how far that carries over to other contracts. Not far, as you will see.
Breaking the IB and closing beyond it, by weekday#
The table measures one specific thing that is easy to confuse with another. It does not count how often price leaves the Initial Balance. It counts, out of every break recorded, how often the session ended up closing beyond the level it broke.
Each row is a weekday and rests on between 940 and 1,043 NQ breaks. The samples are of the same order of magnitude, so the rows can be compared with one another without any of them dragging the rest.
Monday leads on the upside: the close landed above the broken high in 58.9% of 940 NQ breaks. Friday follows at 58.0% of 942. Wednesday is the weakest row in the table, at 52.4% of 1,043.
NQ: rotura del Initial Balance y cierre más allá del nivel
NQ
Swipe to see the sample →
| Día | Rompe el máximo | Rompe el mínimo | Roturas |
|---|---|---|---|
| Lunes | 58.9% | 46.9% | 940 |
| Martes | 55.5% | 45.3% | 1,001 |
| Miércoles | 52.4% | 49.7% | 1,043 |
| Jueves | 54.4% | 45.6% | 1,003 |
| Viernes | 58.0% | 51.8% | 942 |
n = 4,929 · 2010-06-07 to 2026-09-15 · historical futures data
IB = rango de los primeros 60 minutos de la sesión regular (9:30-10:30 ET). El porcentaje es cuántas veces la sesión cerró por fuera del extremo roto, no cuántas veces hubo rotura.
See it on a real day
The Today brief: how much your market usually moves, how far its levels are and when the next release is due, every figure with its n. No sign-up.
See the demo →The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The asymmetry between the upside and the downside#
The contrast between the two columns is the main finding. On all five weekdays, a break of the high ends with the close above it more often than a break of the low ends with the close below it. In NQ there is no exception.
The distance is widest on Monday: 58.9% up against 46.9% down, over 940 NQ breaks. On Wednesday it nearly vanishes, 52.4% against 49.7% over 1,043. On the downside, only Friday clears 50%, at 51.8% over 942 breaks.
Tuesday closes below in 45.3% of its 1,001 NQ breaks, Thursday in 45.6% of 1,003. Before reading that as a property of the Nasdaq: the series covers sixteen years in which the index rose far more than it fell, and that drift seeps into any directional measurement.
What the day does depending on IB size#
The second table splits 4,182 NQ sessions by the size of the Initial Balance measured as a percentage of price, then looks at what the day did next: break one side, break both, or stay inside the range.
From the 0.25-0.5% bucket onward the progression is orderly. Breaking both sides falls from 29.6% over 1,064 NQ sessions to 21.6% in the 0.5-0.75% bucket, over 1,220, and down to 16.5% between 1.5% and 2.0%, over 206.
The mirror reading holds: breaking a single side climbs from 67.2% to 77.3% in the 1.0-1.5% bucket, over 648 NQ sessions. Staying inside all session is rare, between 3.2% and 5.8%, except above 2.0%, where it reaches 12.6% over 87 sessions.
NQ: qué hace el día según el tamaño del Initial Balance
NQ
Swipe to see the sample →
| Tamaño del IB | Rompe un lado | Rompe los dos | Sin rotura | Sesiones |
|---|---|---|---|---|
| 0-0,25% | 75.0% | 21.0% | 4.0% | 124 |
| 0,25-0,5% | 67.2% | 29.6% | 3.2% | 1,064 |
| 0,5-0,75% | 74.7% | 21.6% | 3.7% | 1,220 |
| 0,75-1,0% | 74.5% | 19.7% | 5.8% | 833 |
| 1,0-1,5% | 77.3% | 17.7% | 4.9% | 648 |
| 1,5-2,0% | 77.7% | 16.5% | 5.8% | 206 |
| >2,0% | 69.0% | 18.4% | 12.6% | 87 |
n = 4,182 · 2010-06-07 to 2026-09-15 · historical futures data
Tamaño del IB como porcentaje del precio. Un IB estrecho rompe los dos lados con más frecuencia (más rotación); uno ancho tiende a romper un solo lado.
The narrowest bucket breaks the pattern#
One row does not fit. The narrowest IB, 0-0.25%, breaks both sides in 21.0% of sessions. If the relationship were clean that should be the highest value in the column, and it sits below the bucket above it.
The likely reason is the sample: 124 NQ sessions, against 1,064 in the 0.25-0.5% bucket and 1,220 in the 0.5-0.75% one. An Initial Balance that narrow is uncommon in this contract.
The above-2.0% bucket, with 87 NQ sessions, deserves the same caution. When both ends of a table behave oddly and are also the thinnest samples, the sensible move is to treat them as a hint rather than a firm result.
The most repeated session statistics, next to a control#
Dozens of NQ session figures with high percentages circulate. Almost all of them are true. The question is a different one: whether they say anything. To find out, each figure is compared with a random control: from the moment the condition is known, what happened next is replaced by a price with no direction and the same volatility. The control keeps where price was and how much time was left, and removes direction only.
'The first hour gets broken on one side before the close': 95.8% in NQ, over 4,045 sessions. The random control gives 96.2%. It is true and says nothing: with five and a half hours to go, almost any one-hour range gets broken.
The same goes for 'the first five-minute range breaks to the upside' (86.2% measured, 85.6% for the control), 'the day's high and low sit in opposite halves of the session' (72.8% and 72.9%) and 'the first hour closes in its upper half and its high gets broken' (81.9% and 81.0%). They describe position and time, not an edge.
The most repeated one is the 9:00 candle: if it is green, the session closes green. As usually told it gives 69.9%, but the half hour from 9:30 to 10:00 sits in both the signal and the outcome. Measured without that overlap, from 10:00 to 16:00, it comes to 57.9%, over 2,127 sessions, against 55.4% for all sessions in the period.
Two rows do depart from their control, and neither the way it is told. 'Breaks the prior hour's extreme and returns to the hour's open' happens 88.6% of the time against 85.9% for the control. Net of costs, the difference is smaller than what one trade costs. And 'opens below yesterday's low and closes below it' gives 60.6% against 67.5% for the control: it holds less often than chance. It is usually presented as continuation and describes the opposite.
Much-repeated NQ session statistics, next to a random control
NQ, ES
Swipe to see the sample →
| The figure, in words | NQ: the figure, measured | NQ: a random control with the same position, time and volatility | ES: the figure, measured | ES: the same control | Sessions |
|---|---|---|---|---|---|
| The first hour (9:30-10:30) is broken on either side before the close | 95.8% | 96.2% | 97.7% | 98.3% | 4,045 |
| The first hour closes in its upper half → its high is broken | 81.9% | 81.0% | 82.1% | 82.7% | 2,195 |
| The day's high and low fall in opposite halves of the session | 72.8% | 72.9% | 75.2% | 74.8% | 4,065 |
| Breaks the previous hour's extreme in the first 20 minutes of the 9:00 hour → returns to the hour's open | 88.6% | 85.9% | 85.5% | 82.9% | 2,077 |
| The 9:00 candle is green → the session closes green (no overlap: 10:00 to 16:00) | 57.9% | 55.4% | 57.0% | 54.8% | 2,127 |
| Opens below yesterday's low → closes below that low | 60.6% | 67.5% | 61.8% | 67.3% | 548 |
| The range of the first 5 minutes is broken to the upside | 86.2% | 85.6% | 87.6% | 87.8% | 4,069 |
| London extends only upward → New York exceeds its high | 82.3% | 82.6% | 78.9% | 81.2% | 1,611 |
n = 4,069 · 2010-06-07 to 2026-10-09 · historical futures data
NQ and ES futures, 1-minute bars of the front contract, from 7-Jun-2010 to 9-Oct-2026; times in ET. Each row is a much-repeated figure about the session, measured with the definition it is usually stated with ('break' = exceed the level by at least one tick). 'The figure, measured' = percentage of the sessions in which the row's condition holds; 'Sessions' are NQ's and the n in the footer is the number of NQ sessions with a complete regular session. Control: from the moment the condition is known, what happened next is replaced by a price with no direction and the same minute-by-minute volatility (each later bar is mirrored with probability one half; 40 repetitions). It keeps where the price was, how much time was left and how much it was moving, and removes only direction. Reading rule: if the two columns look alike, the figure is true but says nothing; it describes position and time left, not an edge. Definitions: the first hour is followed until 16:00, on the sessions where 10:30 opens inside its range; halves of the session = 8:00-12:00 and 12:00-16:00; 9:00 candle = 9:00 to 10:00, and the previous hour, 8:00 to 9:00, with the return to the open before 10:00; yesterday's low = that of the previous regular session (9:30-16:00), with the 9:30 open; first 5 minutes = 9:30-9:35, until 16:00; London = 2:00-8:00 when it exceeds the high of Asia (20:00-2:00) without breaking its low, and New York = 8:00-16:00. The 9:00 candle: as usually repeated (the 9:30 to 16:00 session closes green) the figure is 69.9% on NQ, but the half hour from 9:30 to 10:00 sits in both the signal and the outcome and that alone already gives 64.8% in the control (ES: 68.6% and 62.1%). The row measures without that overlap, from 10:00 to 16:00: 57.9%. In this row the second column is not the random control but the base rate of all days, because the market rose over the period: from 10:00 to 16:00 NQ closed green in 55.4% of all sessions (4,035) and in 52.6% after a red candle (1,908); on ES, 54.8% (3,975) and 52.4% (1,894). Difference against the control on NQ, with a 95% confidence interval (resampling in blocks of 5 sessions), in percentage points: return to the hour's open +2.8 [1.4 to 4.1]; open below yesterday's low −6.9 [−10.9 to −2.9], that is, it holds less often than chance: the figure is usually presented as continuation and describes the opposite. In the other five rows with a random control the interval includes zero. Two of the figures were tested as rules, with 1 tick per side and USD 4.50 of round-trip commission. Trading the return to the hour's open (enter on the break, exit at the hour's open or at 10:00) left −0.77 NQ points per trade (2,077 trades, 84.1% winners: many small wins and a few large losses) and −0.25 points on ES (1,941). Trading the first break of the 5-minute range before 10:00, with the stop on the other side of the range and a target of one times the risk, left −0.05 times the risk per trade on NQ (4,030) and −0.16 on ES (4,024). It is what happened, not a signal.
These numbers are NQ's and do not transfer#
Lifting a percentage from one table and applying it to another contract is exactly the temptation this comparison argues against. The same measurement, same definition and same period, produces a different split on the E-mini S&P 500.
On Monday, a close above the broken high is 58.9% of 940 breaks in NQ and 54.9% of 1,000 in ES. With an IB of 0-0.25%, breaking both sides is 21.0% in NQ over 124 sessions and 34.1% in ES over 533.
Scale does not match either: average daily true range is 174.8 points in NQ and 43.7 in ES, over 4,218 sessions each. What carries from one contract to another is the method, never the number.
Limits of the measurement and sensible use#
The Initial Balance is a clock convention, not a level the market watches. Measuring it over thirty or ninety minutes produces a different table that is just as defensible, and its figures stop being comparable with these.
Both tables run from 2010-06-07 to 2026-09-15 and blend very different volatility regimes: a sixteen-year average does not describe the particular month you are trading. No figure is conditional on context, and no percentage nets out spread, commissions or slippage.
The sensible use is descriptive: note the size of today's IB, place it in its bucket, and see which shape of session is more frequent there, without inferring direction. This content is informational material about reading historical data, not personalized investment advice; past results do not anticipate future ones, and trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- How often does NQ close beyond the Initial Balance it broke?
- It depends on the side and the day. On the upside, between 52.4% on Wednesday, over 1,043 breaks, and 58.9% on Monday, over 940. On the downside, between 45.3% on Tuesday, over 1,001, and 51.8% on Friday, over 942. In total, 4,929 NQ breaks.
- Why does the upside look better than the downside in NQ?
- It is the clearest asymmetry in the table: on Monday, 58.9% against 46.9% over 940 NQ breaks. The likeliest explanation is not the Initial Balance but sixteen years of series in which the index rose far more than it fell.
- Does a narrow Initial Balance in NQ point to a bigger day?
- The data does not say that: the columns only separate breaking one side, breaking both, or neither, and nothing measures the travel afterward. The 0-0.25% bucket also holds just 124 NQ sessions and breaks both sides in 21.0%, below the 29.6% of the next bucket.
- Can I use these NQ figures on ES or other futures?
- Not without measuring again. With the same definition and period, breaking both sides on a 0-0.25% IB is 21.0% in NQ over 124 sessions and 34.1% in ES over 533.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- In-session Market Profile — Initial Balance, Value Area, POC and profile shape during the session, against their history.
The calculation and its limits are in the methodology.
Take it to your chart, free
Setup State: What state are today's gap, Initial Balance and opening range in?
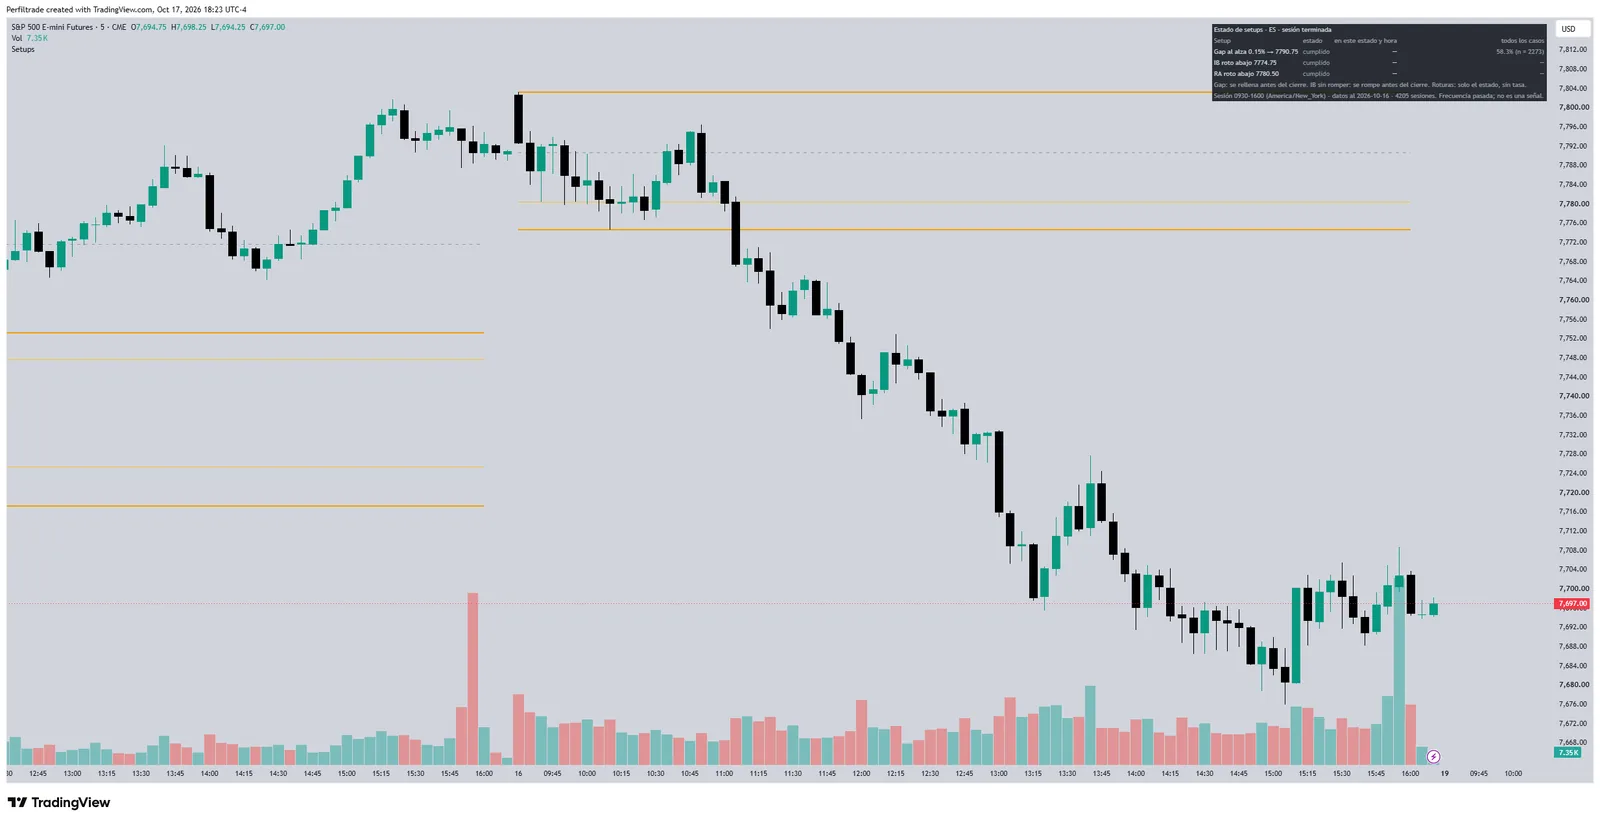
While the gap is open, how many past sessions that had it open at the same time of day filled it before the close, with the rate of all cases as the base.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). NQ Initial Balance Statistics. https://www.perfiltrade.com/en/learn/nq-initial-balance-statistics
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →