CME FX Futures Statistics: 6E, 6J, 6B, 6A
Updated October 12, 2026
What CME FX futures are#
An FX future is a standardized contract to exchange a fixed amount of one currency for dollars on a future date. The four most followed are the euro (6E), the yen (6J), the pound (6B) and the Australian dollar (6A).
Contract size is set by the exchange. The 6E covers 125,000 euros, with a minimum tick of 0.00005 worth $6.25. The 6B covers 62,500 pounds, with a 0.0001 tick and the same $6.25. The 6J covers 12,500,000 yen, with a 0.0000005 tick and again $6.25. The 6A covers 100,000 Australian dollars, with a 0.0001 tick and $10.00.
There is a one-line check: tick value equals contract size times tick size. These are each contract's public specifications.
What changes versus spot forex#
Against the spot market the underlying does not change, since it is the same exchange rate. The infrastructure does. In the future, size, tick and expiry are identical for everyone. In spot, each trade is agreed with a counterparty that sets the terms.
The second difference is the clearing house: it stands between buyer and seller, and both post margin with it under published rules. Credit risk against a specific counterparty becomes risk against the clearing house.
The third is hours and calendar: exchange-defined sessions, daily settlement, and expiries on fixed dates that force a roll into the next contract. Spot does not expire that way. These are design differences; no volume or cost comparison is made here, because this series measures neither.
Breaking the previous day's range#
The first table answers a simple question: when price clears yesterday's high or loses yesterday's low, which way does the day close? It gathers 15,963 breaks across the four contracts, from 2010-06-07 to 2026-10-09.
The 6E closes green 70.6% of the times it breaks yesterday's high and red 70.2% of the times it loses the low, across 4,018 breaks. The 6J: 71.1% and 71.1% across 3,917. The 6B: 71.9% and 71.5% across 3,997. The 6A: 70.6% and 67.5% across 4,031.
That green or red is the close against the same day's open, not against the level that broke. A day breaking both extremes counts in both columns, so the figures do not add up to 100.
Currencies: breaking yesterday's range and the colour of the close
6E, 6J, 6B, 6A
Swipe to see the sample →
| Contract | Breaks the high and closes green | Breaks the low and closes red | Breaks |
|---|---|---|---|
| 6E | 70.6% | 70.2% | 4,018 |
| 6J | 71.1% | 71.1% | 3,917 |
| 6B | 71.9% | 71.5% | 3,997 |
| 6A | 70.6% | 67.5% | 4,031 |
n = 15,963 · 2010-06-07 to 2026-10-09 · historical futures data
Currency futures quoted against the dollar. Colour of the session = close against the open of the same day; a day that breaks both sides counts in both columns. Version of 12-Oct-2026, with data to 9-Oct-2026: a close equal to the open no longer counts as red, which used to inflate the low column. Currency data before 2016 is cleaned of off-market prices.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The four contracts behave alike#
What stands out is not any single figure but how little they separate. On the upside all four sit between the 70.6% of the 6E and the 6A and the 6B's 71.9%: 1.3 points. On the downside the spread reaches 4.0 points, from 67.5% to 71.5%.
Compare that with the index contracts under an equivalent measurement: in gap fill by instrument, an upside gap fills 40.6% of the time on NKD and 63.0% on RTY, 22.4 points apart. There the contract you pick changes the answer; here, barely.
What rules is the type of day, not the pair. Four currencies with different central banks, time zones and calendars give almost the same number; hunting for the contract that breaks best is hunting for a difference these tables do not find.
When the day opens inside yesterday's range#
The second table looks at every session and asks whether price leaves the previous day's range at any point, above or below. The alternative is staying fully inside.
Leaving is the norm. The 6E breaks out in 85.8% of sessions and stays fully inside in 14.2%, across 4,009 days. The 6A: 85.7% and 14.3% across 4,008. The 6B: 84.6% and 15.4% across 4,032. The 6J breaks out least: 83.5% and 16.5%, across 3,986.
A day that stays inside is an inside day: its high and low fit within the prior range. Again there is little dispersion, 2.3 points between the contract that breaks out most and the one that breaks out least. Knowing the break is usual says nothing about which way, when, or how far.
Currencies: how many sessions stay inside yesterday's range
6E, 6J, 6B, 6A
Swipe to see the sample →
| Contract | Breaks out | Stays inside | Sessions |
|---|---|---|---|
| 6E | 85.8% | 14.2% | 4,009 |
| 6J | 83.5% | 16.5% | 3,986 |
| 6B | 84.6% | 15.4% | 4,032 |
| 6A | 85.7% | 14.3% | 4,008 |
n = 16,035 · 2010-06-07 to 2026-10-09 · historical futures data
The denominator is every session, not only those following an inside day: 'stays inside' is the inside day, with its high and low within the prior day's range. Breaking it is the norm; what is informative is how far each contract strays from that norm. Data cleaned on 14-Oct-2026: off-market prices that appeared in the currency data before 2016 were removed.
Why these two measurements, and what they do not prove#
They were chosen because neither depends on a regular-session clock. In FX, activity is split between Asia, London and New York, so a measurement tied to the U.S. window would describe only one slice of the day. Correction of October 2026: currency data before 2016 carried, in some bars, a price that was not a market price. It was cleaned and both tables were recomputed, now through 2026-10-09. Also, a day that closes exactly at its open no longer counts as red, which used to inflate the low column. The figures changed by 1.3 points at most from the first version.
Neither shows those breaks are tradable. The first measures the closing color once the break has happened, over the whole day: it does not say at what price you would have entered, or how far price pulled back first. The second measures whether a break occurred, not whether it held.
The data has limits. The continuous series chains the most traded contract of each day, so on roll days the jump between expiries can look like movement. The day is the exchange trading day, from 18:00 the evening before to 17:00, New York time. And no percentage here nets out spread, commissions or slippage.
To close#
In short: breaking yesterday's range comes with a same-direction close around 70% of the time, opening inside that range ends in a break on more than four of every five sessions, and the four contracts do almost the same thing.
The use is calibration: telling the usual from the exceptional when you look at a chart. Choosing between 6E, 6J, 6B and 6A on these two measurements makes little sense; what does separate them is contract size and tick value.
This text is informational and educational material about reading historical data. It is not personalized investment advice, nor a recommendation to buy or sell. Trading futures involves risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- How big is the 6E contract and what is a tick worth?
- The euro future (6E) covers 125,000 euros, and its minimum tick of 0.00005 is worth $6.25. The 6B, over 62,500 pounds, carries that same tick; the 6A, over 100,000 Australian dollars, is worth $10.00 per tick.
- How do FX futures differ from spot forex?
- In the infrastructure, not the underlying. The future has exchange-set size and tick, a clearing house between the parties, daily settlement, and expiries that force a roll. Spot is agreed with each counterparty and does not expire.
- How often does a session that opens inside yesterday's range leave it?
- In this series, between the 6J's 83.5% and the 6E's 85.8%, with the 6B at 84.6% and the 6A at 85.7%. Staying inside all day is the minority case: from 14.2% to 16.5% depending on the contract.
- Can a previous-day range break be used as an entry signal?
- These tables do not support that. They measure the closing color once the break has happened, over the whole day and without netting out costs, so they describe a historical frequency, not an entry or an exit.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- COT positioning — Weekly COT for 17 instruments with a 0-100 index and loaded positioning.
The calculation and its limits are in the methodology.
Take it to your chart, free
IB and gap: How often did a gap like today's fill?
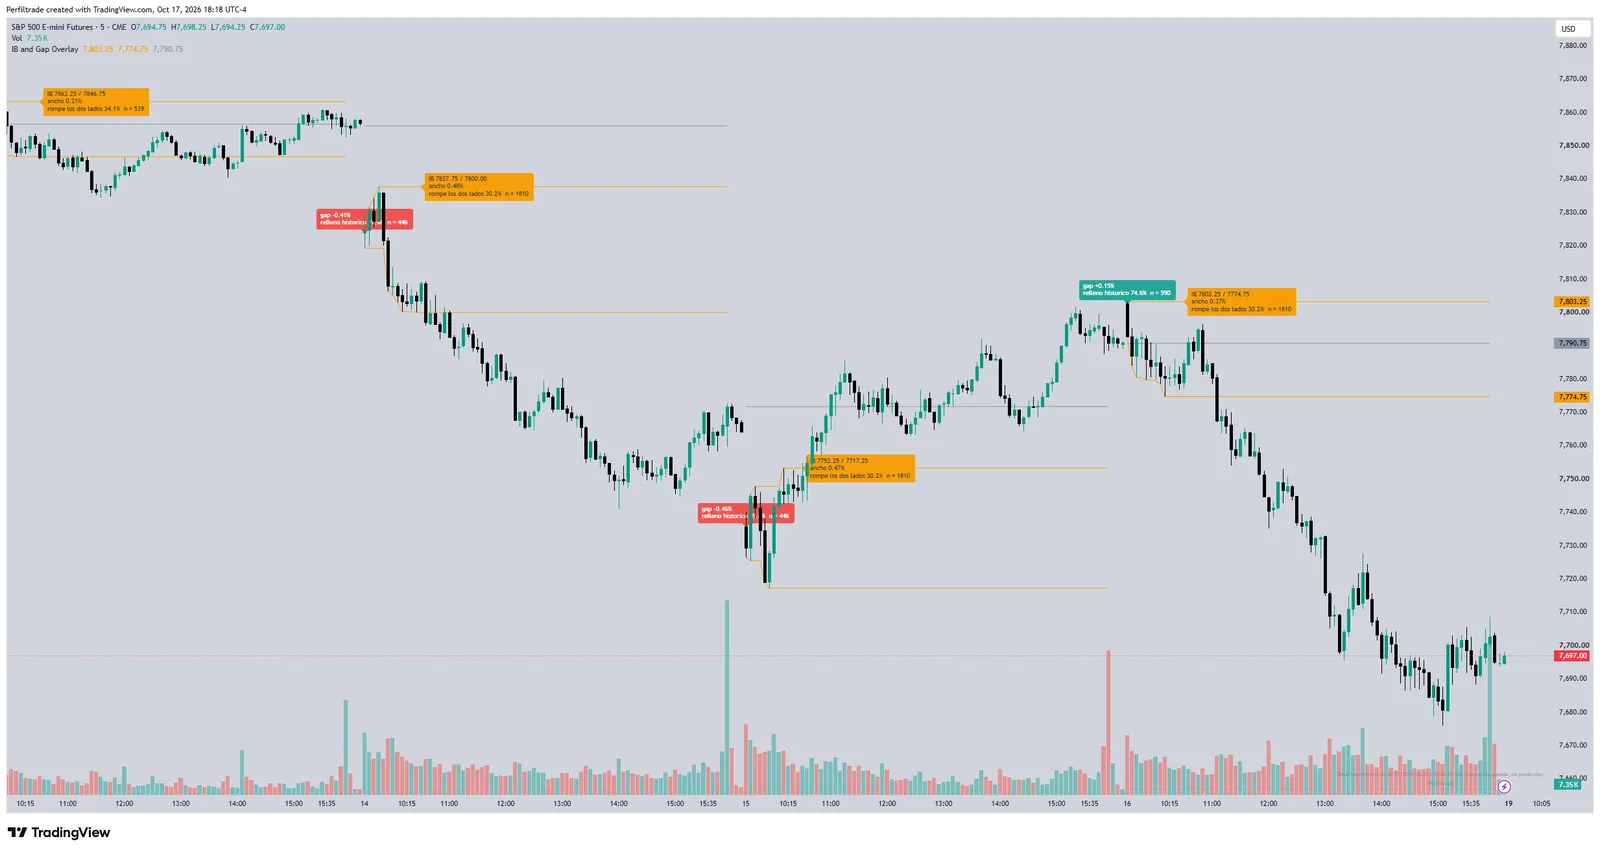
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). CME FX Futures Statistics: 6E, 6J, 6B, 6A. https://www.perfiltrade.com/en/learn/cme-fx-futures-statistics
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →