ES vs NQ: The Differences, Measured
Updated October 4, 2026
What this comparison measures#
ES is the E-mini S&P 500 and NQ the E-mini Nasdaq-100, both listed on CME. The usual question is which one to trade, and the usual answer is an impression: that NQ moves more. This article does not say which one to trade, only where the two differ when measured the same way.
Four measurements run over the same dates: average daily true range in index points, gap fill at the open across five indices, and the Initial Balance break calculated separately on each contract. Every table carries its own sample and period.
The short version: gap behaviour is nearly identical on both, the range gap shrinks once points are converted into money, and the Initial Balance break is where the two contracts do part company.
Average range in points is not comparable#
Average daily true range over 4,218 sessions of each contract, from 2010-06-08 to 2026-09-16: 43.7 points on ES and 174.8 on NQ. Exactly four times as much, since 43.7 x 4 = 174.8.
Within each contract the weekday spread is narrow. ES runs from Tuesday, its quietest day at 42.46 points, to Thursday, its widest at 45.32. NQ runs from Friday at 169.44 to Thursday at 181.88.
That four-times figure is the most repeated and the most misread, because a point of ES and a point of NQ are not the same quantity of anything. Comparing them unconverted is comparing two rulers with different markings.
Average true range by instrument, in points
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Average range | Quietest day | Busiest day | |
|---|---|---|---|---|
| ES | 43.7 pts | Tuesday 42.46 | Thursday 45.32 | 4,218 |
| NQ | 174.8 pts | Friday 169.44 | Thursday 181.88 | 4,218 |
| RTY | 39.6 pts | Monday 38.69 | Wednesday 40.69 | 2,388 |
| YM | 339.4 pts | Monday 332.67 | Thursday 350.03 | 4,222 |
| NKD | 451.1 pts | Monday 439.32 | Thursday 459.49 | 4,217 |
n = 19,263 · 2010-06-08 to 2026-09-16 · historical futures data
Average daily true range in index points, averaged over every session from 2010 to 2026. In points, that average depends mostly on the price level: ES closed at 1,049 in June 2010 and at 7,786 on 15 October 2026, so the ES average of 43.7 points sits far below what the market moves today and does not describe the size of a current day. How much each contract moves today, over its last 250 sessions and in dollars per standard contract and per micro, is in the table "How much each future moves today, in points and in dollars". It is what happened, not a signal.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
From points to money: $50 against $20#
The contract specifications settle it: one ES point is worth $50 and one NQ point is worth $20. The minimum tick is 0.25 points on both, and that tick is worth $12.50 on ES against $5.00 on NQ.
Converted, the average range stops being a point count. ES: 43.7 x 50 = $2,185 per contract per day. NQ: 174.8 x 20 = $3,496. The ratio is 3,496 / 2,185 = 1.6. NQ does not move four times more money per day. It moves 1.6 times more.
The weekday extremes convert the same way. Thursday: ES 45.32 x 50 = $2,266 and NQ 181.88 x 20 = $3,637.60. The quietest days: ES Tuesday 42.46 x 50 = $2,123 and NQ Friday 169.44 x 20 = $3,388.80.
A 10-point move is $500 per contract on ES and $200 on NQ. Three-figure swings on an NQ chart do not mean more risk on the screen. They mean the unit of measurement is smaller.
Gap fill: this is where they look alike#
The gap runs from the previous regular-session close at 16:00 ET to today's open at 9:30 ET. It counts as filled when price trades back to that close within the same regular session. Zero gaps are excluded.
Under that definition ES fills 58.3% of gaps up across 4,072 sessions and 61.3% of gaps down; NQ fills 60.3% across 4,099 sessions and 64.2%. The distance between them is 2.0 percentage points on the upside and 2.9 on the downside.
That is small next to the rest of the table: RTY prints 63.0% and 62.2% across 2,321 sessions, YM 57.6% and 62.2% across 4,096, and NKD 40.6% and 43.1% across 4,062. Between the highest and lowest gap-up fill there are 63.0 - 40.6 = 22.4 percentage points. Both contracts also share the same asymmetry: gaps down fill more often than gaps up, by 3.0 points on ES and by 3.9 on NQ.
The same gap, five instruments
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Gap up | Gap down | Sessions |
|---|---|---|---|
| ES | 58.3% | 61.3% | 4,072 |
| NQ | 60.3% | 64.2% | 4,099 |
| RTY | 63.0% | 62.2% | 2,321 |
| YM | 57.6% | 62.2% | 4,096 |
| NKD | 40.6% | 43.1% | 4,062 |
n = 18,650 · 2010-06-07 to 2026-09-15 · historical futures data
The same measurement applied to each index. Differences between instruments are why a bare figure, without saying which market it comes from, is useless.
The Initial Balance break on ES#
The Initial Balance is the range of the first sixty minutes of the regular session, 9:30 to 10:30 ET. The table does not count how often a break happened: it measures, out of every break, how often the session closed beyond the extreme that was broken.
ES has 5,226 breaks. On the upside, the close finishes beyond the level in 51.6% of Wednesday's 1,109 breaks, the weakest cell, and in 57.4% of Friday's 1,009, the strongest: 5.8 percentage points between the extremes.
On the downside, none of the five ES cells reaches 50%: 43.6% on Monday across 1,000 breaks, 46.6% on Tuesday across 1,061, 48.7% on Wednesday across 1,109, 43.9% on Thursday across 1,047 and 47.7% on Friday across 1,009.
Initial Balance break and close beyond the level
ES
Swipe to see the sample →
| Day | Breaks the high | Breaks the low | Breaks |
|---|---|---|---|
| Monday | 54.9% | 43.6% | 1,000 |
| Tuesday | 54.5% | 46.6% | 1,061 |
| Wednesday | 51.6% | 48.7% | 1,109 |
| Thursday | 56.6% | 43.9% | 1,047 |
| Friday | 57.4% | 47.7% | 1,009 |
n = 5,226 · 2010-06-07 to 2026-09-15 · historical futures data
IB = range of the first 60 minutes of the regular session (9:30-10:30 ET). The percentage is how often the session closed beyond the broken extreme, not how often a break happened.
The same measurement on NQ, and where they split#
The same measurement on NQ collects 4,929 breaks. On the upside Monday prints 58.9% across 940 breaks, the highest value in either table, and Friday 58.0% across 942. Wednesday is again the weakest, at 52.4% across 1,043.
Against ES weekday by weekday, the shift is not uniform: Monday puts NQ 4.0 points higher, 58.9% against 54.9%; Thursday 2.2 points lower, 54.4% against 56.6%; and Wednesday only 0.8 higher.
The cleanest contrast sits on the downside. NQ's Friday prints 51.8% across 942 breaks, the only downside cell above 50% in either table. The same Friday on ES is 47.7% across 1,009, 4.1 points lower.
That is the difference worth noting: gap fill behaves almost identically on the two contracts while the close after an Initial Balance break does not, and that divergence owes nothing to the size of a point.
NQ: rotura del Initial Balance y cierre más allá del nivel
NQ
Swipe to see the sample →
| Día | Rompe el máximo | Rompe el mínimo | Roturas |
|---|---|---|---|
| Lunes | 58.9% | 46.9% | 940 |
| Martes | 55.5% | 45.3% | 1,001 |
| Miércoles | 52.4% | 49.7% | 1,043 |
| Jueves | 54.4% | 45.6% | 1,003 |
| Viernes | 58.0% | 51.8% | 942 |
n = 4,929 · 2010-06-07 to 2026-09-15 · historical futures data
IB = rango de los primeros 60 minutos de la sesión regular (9:30-10:30 ET). El porcentaje es cuántas veces la sesión cerró por fuera del extremo roto, no cuántas veces hubo rotura.
Limits, and what changes when sizing#
It helps to size up the finding. The ES-against-NQ differences in these two tables run from 0.6 to 4.1 percentage points, on cells of roughly a thousand cases each. None nets out spread, commissions or slippage, and none says direction or how far price travels after the break.
The series span 2010 to 2026 and mix very different regimes, so no average here describes the specific month being traded. The samples do not match across contracts either: 5,226 breaks on ES against 4,929 on NQ.
When sizing, contract arithmetic rules, not the impression the chart gives: contract count comes from the stop distance in points times the point value. With a stop of one average range, each contract puts $2,185 at stake on ES and $3,496 on NQ, 1.6 times more.
This text is informational material about reading historical data. It is not personalised investment advice and not a recommendation on any contract. Past results do not anticipate future results, and trading futures carries a risk of loss.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Which is more volatile, ES or NQ?
- It depends on the unit. In points, average true range is 174.8 on NQ against 43.7 on ES, four times as much, across 4,218 sessions of each. In money that is $3,496 against $2,185: 1.6 times as much.
- What is a point worth on ES and on NQ?
- One ES point is worth $50 and one NQ point is worth $20. The minimum tick is 0.25 points on both contracts, which comes to $12.50 per tick on ES and $5.00 on NQ. These are contract specifications.
- Does the gap fill more often on NQ than on ES?
- Slightly more, and only slightly. NQ fills 60.3% of gaps up and 64.2% of gaps down across 4,099 sessions; ES fills 58.3% and 61.3% across 4,072. The difference is 2.0 and 2.9 percentage points.
- Do the ES Initial Balance statistics carry over to NQ?
- Not without measuring again. Under the same definition, Monday's upside break is 58.9% on NQ across 940 breaks against 54.9% on ES across 1,000, and Friday's downside is 51.8% against 47.7%. Same calculation, different splits.
These numbers, instrument by instrument
See all 30 instruments →Where this is used in Perfiltrade
- Base-rate reports — 18 core reports and 24 more in the archive across 30 instruments, every figure with n, period and caveats.
The calculation and its limits are in the methodology.
Take it to your chart, free
IB and gap: How often did a gap like today's fill?
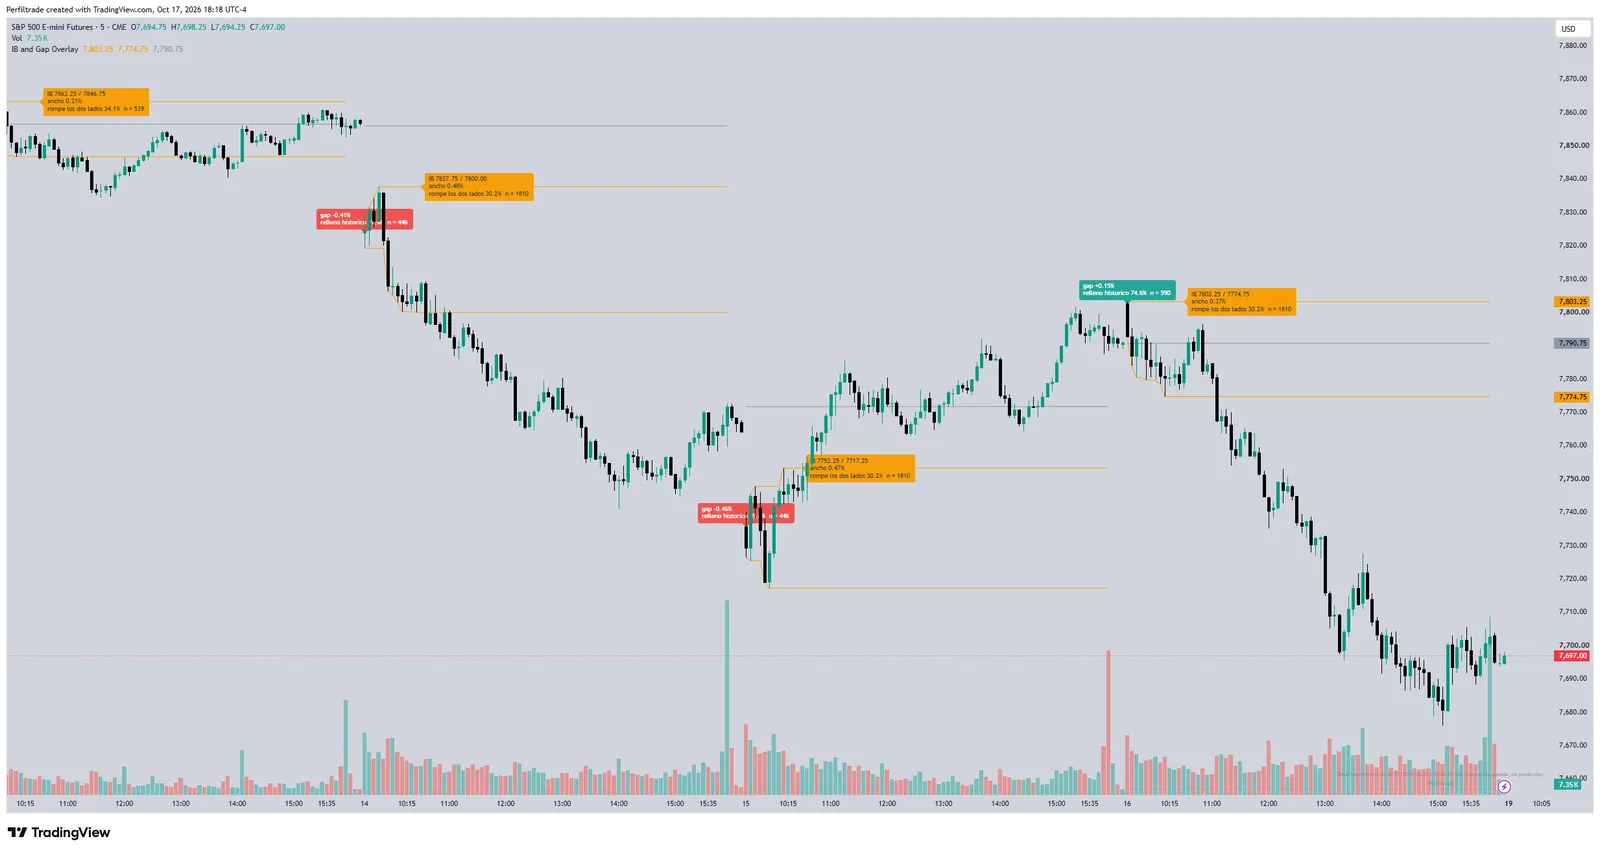
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 4, 2026). ES vs NQ: The Differences, Measured. https://www.perfiltrade.com/en/learn/es-vs-nq-statistical-differences
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →