Gap Fill Statistics for Five Index Futures: 18,650 Sessions
Updated October 24, 2026
Why this had to be measured on five markets at once#
"Gaps always get filled" is probably the most repeated claim about the futures open. It almost never comes with the three things that would make it checkable: which market, what counts as a fill, and over how many sessions.
When a figure does appear, it usually comes from a single instrument, normally the E-mini S&P 500, and then gets quoted as if it described markets in general. This study exists to check whether that holds.
Here is the same measurement applied to five index futures: ES, NQ, RTY, YM and NKD. Same code, same data source, same definition of gap and of fill. 18,650 daily sessions and 3,834 weekly opens.
It is not a strategy and not a signal. It is a base rate: how often something happened in the past, with the sample in plain sight so it can be argued with.
How it is measured, definitions first#
The gap runs from the previous regular-session close, 16:00 New York time, to today's open at 9:30. Overnight prices are not used as the reference: the anchor is the official prior regular-session close.
"Filled" means price traded back to that prior close within the same regular session. If it gets there the next day, it counts here as unfilled. Sessions that open exactly at the previous close are excluded.
Gap size is expressed as a percentage of price, never in points. That is the only way to compare a contract trading around 6,000 points with one trading near 45,000: fifty points do not mean the same thing in both.
One warning about the sample: the RTY series starts in 2017 and the other four in 2010. Their percentages are comparable; their session counts are not.
The overall result: four similar contracts and one outlier#
Side by side, ES, NQ, RTY and YM sit in a narrow band: from YM's 57.6% on gaps up to NQ's 64.2% on gaps down. If someone says "the gap fills about 60% of the time", for these four they are not far off.
NKD breaks the pattern: 40.6% up and 43.1% down. That is between seventeen and twenty-two percentage points below the other four, on a sample of 4,062 sessions, which is too large to put down to chance.
A second detail repeats itself: in four of the five contracts, gaps down fill more often than gaps up. RTY is the exception: 63.0% up against 62.2% down, eight tenths of a point on the shortest sample of the five.
The useful reading is not which number is best but that a range exists at all. A bare figure, with no market attached, can be twenty points wrong.
The same gap, five instruments
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Gap up | Gap down | Sessions |
|---|---|---|---|
| ES | 58.3% | 61.3% | 4,072 |
| NQ | 60.3% | 64.2% | 4,099 |
| RTY | 63.0% | 62.2% | 2,321 |
| YM | 57.6% | 62.2% | 4,096 |
| NKD | 40.6% | 43.1% | 4,062 |
n = 18,650 · 2010-06-07 to 2026-09-15 · historical futures data
The same measurement applied to each index. Differences between instruments are why a bare figure, without saying which market it comes from, is useless.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
Gap size matters more than the market does#
Splitting each instrument by the size of the gap brings out the dominant effect of the whole study, and it is the same in all five contracts.
When the gap is smaller than 0.1% of price, the fill rate runs from NKD's 89.1% to RTY's 92.6%. All five markets behave almost identically. When the gap is larger than 1.0%, the range collapses to RTY's 28.1% and NKD's 10.2%.
Compare the distance along the two axes of the table. Within ES alone, going from a tiny gap to a large one takes the fill rate from 91.3% to 20.3%: seventy-one points. Within any single row, the gap between the best and worst contract rarely reaches twenty.
Put differently: "will the gap fill?" is the wrong question. The one carrying information is "how big is it?". The specific market matters, but it matters less.
Gap fill by gap size, across the five indices
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Gap size | ES | NQ | RTY | YM | NKD | Sessions |
|---|---|---|---|---|---|---|
| 0-0.1% | 91.3% | 91.8% | 92.6% | 92.5% | 89.1% | 3,010 |
| 0.1-0.25% | 74.4% | 79.3% | 84.1% | 72.7% | 72.2% | 4,125 |
| 0.25-0.5% | 54.7% | 61.8% | 66.3% | 52.2% | 51.1% | 4,683 |
| 0.5-1.0% | 33.2% | 45.2% | 47.8% | 32.0% | 30.9% | 4,227 |
| >1.0% | 20.3% | 23.8% | 28.1% | 18.6% | 10.2% | 2,605 |
n = 18,650 · 2010-06-07 to 2026-09-15 · historical futures data
Gaps up and down together, filled within the same regular session. Size is measured as a percentage of price, not in points, so the five contracts are comparable. The RTY series starts in 2017, not 2010: its sample is smaller and comparable in percentage only, not in session count.
Do big gaps fill rarely because of release days?#
A common explanation: big gaps hardly fill because they land on CPI, jobs or Fed days. We measured it in ES, NQ, YM and RTY, from 1-Jul-2010 to 23-Oct-2026 (RTY since 2017), with the gap measured in 14-session ATR: 3,281 gaps of 0.5 ATR or more.
Across the four, 25.6% filled. On release days, 27.2% (987 gaps); on other days, 24.9%. Had release days filled like the other days of the same bucket, direction and open, the rate would have been 24.8%: a 0.8-point difference, with an interval of −0.6 to 2.2.
With 93 comparisons at once, none holds up: the same as chance. Depending on the index, release days are almost the same share of big gaps (27.8% to 34.6%) as of all gaps (27.8% to 28.4%). The fill rate falls with the size of the gap; the day's release does not change it.
Big gaps (0.5 ATR or more): how much of the low fill rate comes from macro-release days
ES, NQ, YM y RTY
Swipe to see the sample →
| Index | Fills, release day | Fills, no release | Fills, all | If release days filled like the others | Difference (points) | 95% interval | Reading | Big gaps on release days | Big gaps |
|---|---|---|---|---|---|---|---|---|---|
| ES | 27.4% | 22.4% | 23.9% | 22.4% | 1.6 | 0.2 to 3.0 | same as chance | 296 | 965 |
| NQ | 28.1% | 28.0% | 28.0% | 28.0% | 0 | −1.5 to 1.6 | same as chance | 267 | 900 |
| YM | 24.5% | 23.7% | 24.0% | 23.6% | 0.4 | −1.0 to 1.7 | same as chance | 269 | 968 |
| RTY | 29.7% | 26.6% | 27.7% | 26.5% | 1.2 | −1.2 to 3.6 | same as chance | 155 | 448 |
| The four together | 27.2% | 24.9% | 25.6% | 24.8% | 0.8 | −0.6 to 2.2 | same as chance | 987 | 3,281 |
n = 3,281 · 2010-07-01 to 2026-10-23 · historical futures data
Gaps of 0.5 ATR or more (14-session ATR known at the open), regular session of ES, NQ, YM and RTY, 1-Jul-2010 to 23-Oct-2026 (RTY from 28-Jul-2017); contract-roll days excluded. Same gap, fill and release-day definitions as the bucket table. 'If release days filled like the others' = each big gap on a release day is given the fill rate of the no-release days in its same bucket, direction and open (inside or outside yesterday's range), averaged with the other big gaps as they were. The difference is how much release days move the big-gap fill rate, in percentage points; the interval of the pooled row resamples whole dates. Release days are 27.8 to 34.6% of the big gaps and 27.8 to 28.4% of all gaps: almost the same share. The size difference-in-differences (big minus small, release minus no release) is 1.2 points (interval −4.0 to 6.5). The interval is the uncorrected 95% interval; the 'Reading' comes from the correction. The study computed 93 comparisons; with a Holm correction at 5% over all of them, none in this table holds up: same as chance. That big gaps fill rarely (25.6% for the four together) does not come from release days: without them the rate would be almost the same. It is what happened, not a signal.
The weekday adds little, except on Monday#
Monday is the lowest-filling day in all five contracts without exception: 53.3% in ES, 59.2% in NQ, 59.9% in RTY, 53.5% in YM and 36.9% in NKD. There is a mechanical reason: the Monday gap carries everything that happened over the weekend and tends to be larger.
Wednesday is the highest day in ES, NQ and YM, at 66.0%, 65.0% and 65.8%. In RTY the peak is Friday, at 64.9%, ahead of Wednesday at 64.3%, and in NKD it falls on Tuesday, at 46.7%.
The size of the effect is moderate. In ES it is almost thirteen points from Monday to Wednesday; in NKD, ten from Monday to Tuesday. Real and consistent, but nowhere near what gap size produces.
The reading order these two tables suggest is clear: size first, then the day, and only then the contract.
Gap fill by day of the week, across the five indices
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Day | ES | NQ | RTY | YM | NKD | Sessions |
|---|---|---|---|---|---|---|
| Monday | 53.3% | 59.2% | 59.9% | 53.5% | 36.9% | 3,685 |
| Tuesday | 59.8% | 62.4% | 61.1% | 57.9% | 46.7% | 3,816 |
| Wednesday | 66.0% | 65.0% | 64.3% | 65.8% | 42.5% | 3,800 |
| Thursday | 61.0% | 62.9% | 62.9% | 62.9% | 41.0% | 3,751 |
| Friday | 57.5% | 60.2% | 64.9% | 57.9% | 41.5% | 3,598 |
n = 18,650 · 2010-06-07 to 2026-09-15 · historical futures data
Same intraday fill as the table above, split by weekday and with both directions together. The RTY series starts in 2017, not 2010: its sample is smaller and comparable in percentage only, not in session count.
The Sunday open changes the Nikkei's portrait#
There is a second kind of gap that is almost never measured alongside the daily one: the one between Friday's close and Sunday's open, counted as filled if price returns to that close at any point during the week.
There the five contracts look much alike: 83.1% to 87.1% on gaps up and 89.3% to 93.7% on gaps down. And NKD, at 84.9% and 89.3%, stops being the odd one out.
This is the finding we expected least and the one that says most. The Nikkei's difference does not look like a gap thing but a time thing: within a single US regular session it returns to the level far less than the others, and over a full week it returns almost as often as they do.
The two tables should not be mixed. They are different measurements: one allows six and a half hours to get back to the level, the other five days.
The weekly opening gap, across the five indices
ES, NQ, RTY, YM, NKD
Swipe to see the sample →
| Instrument | Gap up | Gap down | Weeks |
|---|---|---|---|
| ES | 83.1% | 92.3% | 835 |
| NQ | 84.6% | 92.7% | 845 |
| RTY | 87.1% | 93.7% | 478 |
| YM | 84.6% | 92.2% | 846 |
| NKD | 84.9% | 89.3% | 830 |
n = 3,834 · 2010-06-07 to 2026-09-16 · historical futures data
Gap from Friday's close to Sunday's open, and whether price returns to that close during the week. A different measurement from the daily one: more time available to get back to the level. The RTY series starts in 2017, not 2010: its sample is smaller and comparable in percentage only, not in session count.
What this study does not say#
It does not say when the fill happens. A session that returns to the prior close in the first ten minutes and one that does it at 15:55 count exactly the same here.
It says nothing about direction or about what happens afterwards. A fill is price touching a level: it does not measure how far price ran first or what it did next.
It does not net out costs or slippage, and it describes no particular day. These are frequencies over sixteen years that blend very different regimes.
And it does not explain the differences between contracts. We measure that NKD behaves differently; why it does is a hypothesis, not a result of this data.
How to use these tables when preparing a session#
Treat them as a starting point, not a signal. Before opening the chart, the question is: which row of the size table does today's gap fall into? That answer alone moves the expectation between 90% and 20%.
Then the contract. Trading NKD with ES figures in mind means working with an expectation almost twenty points higher than the one that applies.
And last, the day. Monday deserves a discount in any of the five markets.
For the definition of the gap and the ES detail, the opening gap guide develops the concept. Each instrument page also carries its own gap, range and Initial Balance tables.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Do opening gaps always get filled?
- No. Across these 18,650 sessions, the fill rate within the same regular session runs from NKD's 40.6% to NQ's 64.2%. Only very small gaps, below 0.1% of price, clear 89% in all five contracts.
- Why does the Nikkei fill so much less than the S&P 500?
- This data measures it, it does not explain it. The accompanying fact is that on the weekly open NKD does fill like the rest, 84.9% up and 89.3% down, which points to the difference being the time available inside the US session rather than the gap itself. That is a reasonable hypothesis, not a conclusion of the study.
- Which fills more often, a gap up or a gap down?
- Gaps down, in four of the five contracts: 61.3% against 58.3% in ES, 64.2% against 60.3% in NQ, 62.2% against 57.6% in YM and 43.1% against 40.6% in NKD. In RTY it is narrowly the other way: 63.0% up against 62.2% down.
- What matters more, gap size or the instrument?
- Size, by a wide margin. Within ES, the fill rate falls from 91.3% to 20.3% depending on the size of the gap. Within any single size bucket, the distance between the best and worst of the five contracts rarely exceeds twenty points.
- Why does RTY have fewer sessions than the others?
- Because its data series starts in 2017 and the other four start in 2010. The percentages are comparable across contracts; the session counts are not, which is worth remembering when reading the sample column.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
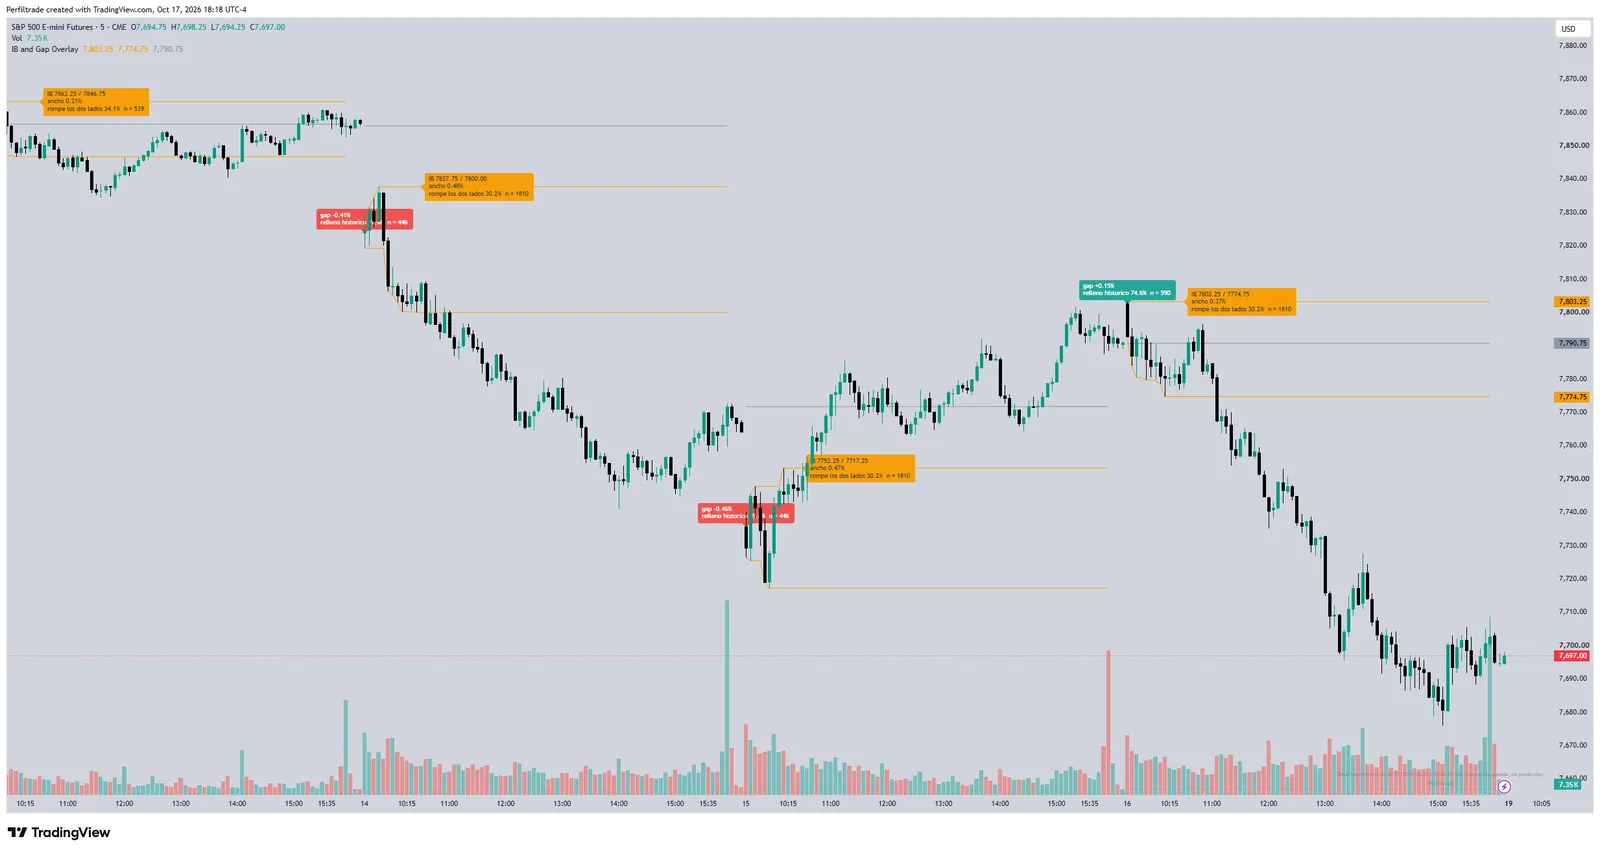
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 24, 2026). Gap Fill Statistics for Five Index Futures: 18,650 Sessions. https://www.perfiltrade.com/en/learn/gap-fill-statistics-five-index-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →