Which Session Makes the Daily High and Low: 10 Futures, 39,937 Sessions
Updated October 1, 2026
The question, and why it needs ten contracts#
Everyone trades one slice of the clock, and almost nobody has checked whether the day's extreme tends to land inside it. The common retail belief is that the New York session decides the day, because that is the session being watched.
Here is the actual split of the daily high and low across the windows of the 24-hour cycle, on ten futures from three families: the five index contracts, gold, and the four US Treasury contracts from 2 to 30 years. 39,937 sessions.
The result that carries the study sits in a short stretch: the New York morning until 11:30, when London is still open and the US main session is already under way. That is two hours in the indices and a little over three in gold and bonds. In nine of the ten contracts that stretch collects between 18.7% and 30.4% of the day's highs.
One warning before going on: this is not a magic hour or a recommended schedule. It is a historical split, and the most useful part of the study is the benchmark it has to be read against.
Correction, October 1, 2026: the first version of this study credited London with every extreme that landed in the overlap with New York. That inflated London and led to wrong conclusions about New York. The current figures and text split the overlap into its own column. On October 2 the overlap hours and the chance benchmark were also adjusted to each contract's main session, which is not the same in indices, gold and bonds.
How it is measured, and why the split by hours is not the benchmark#
Each day the high and the low of the full 24-hour cycle are located and assigned to the window they fell in. The windows are fixed: Asia 09:00 to 15:00 Tokyo time, London 08:00 to 16:30 local with daylight saving handled, and New York, which is each contract's main session: 9:30 to 16:00 Eastern in the indices, 8:20 to 13:30 in gold and 8:20 to 15:00 in bonds. London closes at 11:30 Eastern, so the two overlap for two hours in the indices and a little over three in gold and bonds; an extreme that lands there belongs to both sessions and is counted in its own column, the overlap. The Nikkei is a case apart: its main session is Tokyo's, which nearly coincides with the Asia window, so in its row the overlap and New York columns do not measure the same thing.
That leaves two holes with no window: the stretch between the close of the main session and the Asian open, about three hours of trading in the indices and quite a bit more in gold and bonds, which close earlier, and one or two hours between the Asian close and the London open. Rather than assigning those extremes to the nearest window, they are declared separately in the "outside sessions" column. By construction exactly one of the five columns wins each day, and the five add up to 100%.
The detail that changes the whole reading: not even a market with no memory would split the extremes by hours. In a random walk, the high of an interval tends to land near its start or its end; that is the arcsine law. The day in this series is the UTC calendar day, which starts with Asia and ends after the New York close, so pure chance would give roughly, in the order Asia, London, overlap, rest of New York and outside sessions: 34, 18, 6, 16 and 26% in the indices; 34, 15, 9, 6 and 36% in gold; and 34, 15, 9, 12 and 30% in bonds.
That row is a rough benchmark: it assumes constant volatility through the day, and the real market does not have it. It is good for spotting large deviations, not for interpreting differences of two or three points. And the large deviations are there.
On the sample: the RTY series starts in 2017 and the other nine in 2010. FX, energy and agricultural contracts are missing because this report is not computed for them yet; they get added when it is.
Where the day's high and low form
ES
Swipe to see the sample →
| Session | Day's high | Day's low | Sessions |
|---|---|---|---|
| Asia | 15.5% | 22.3% | 4,175 |
| London | 18.3% | 17.7% | 4,175 |
| London/NY overlap | 18.7% | 19.5% | 4,175 |
| New York | 29.4% | 27.8% | 4,175 |
| Outside sessions | 18.0% | 12.7% | 4,175 |
n = 4,175 · 2010-06-07 to 2026-09-15 · historical futures data
Split of the daily extreme across the sessions of the 24-hour cycle. 'London/NY overlap' is when the extreme prints while both sessions are open, so it cannot be credited to just one. 'Outside sessions' are the minutes left between close and open.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
The overlap takes three or four times its share#
In the indices, against a benchmark of around 6%, the overlap collects 18.7% of the highs in ES, 21.1% in NQ, 21.4% in YM and 25.6% in RTY. In gold and bonds, where the overlap is longer and the benchmark is around 9%, it collects 27.7% in gold and between 26.8% and 30.4% in the four Treasury contracts.
The exception is the Nikkei, for the obvious reason: by then Tokyo has been shut for hours. Its high lands in Asia 44.0% of the time, above the 34% benchmark. Its overlap and New York columns, nearly empty, do not measure the US session: its main session is Tokyo's, which coincides with the Asia window.
The European morning on its own, by contrast, does not stand out. London before the overlap stays close to its benchmark in the nine contracts with a US session: between 17.0% and 18.3% in the indices, against 18%, and between 13.8% and 15.6% in gold and bonds, against 15%.
Put shortly: the day's extreme does not concentrate in one session, but in the moment the two big ones cross.
Which session makes the daily high, across ten futures
ES, NQ, RTY, YM, NKD, GC, ZT, ZF, ZN, ZB
Swipe to see the sample →
| Instrument | Asia | London | London/NY overlap | New York | Outside sessions | Sessions |
|---|---|---|---|---|---|---|
| ES | 15.5% | 18.3% | 18.7% | 29.4% | 18.0% | 4,175 |
| NQ | 14.1% | 17.0% | 21.1% | 28.4% | 19.4% | 4,175 |
| RTY | 14.0% | 18.3% | 25.6% | 27.1% | 15.1% | 2,369 |
| YM | 15.8% | 18.2% | 21.4% | 27.9% | 16.8% | 4,179 |
| NKD | 44.0% | 20.6% | 0.1% | 1.0% | 34.3% | 4,184 |
| GC | 26.2% | 15.5% | 27.7% | 8.9% | 21.7% | 4,155 |
| ZT | 26.1% | 13.8% | 30.4% | 15.1% | 14.5% | 4,184 |
| ZF | 21.7% | 15.6% | 27.9% | 17.4% | 17.5% | 4,180 |
| ZN | 22.2% | 15.6% | 26.8% | 17.3% | 18.2% | 4,165 |
| ZB | 20.6% | 15.4% | 27.4% | 17.5% | 19.1% | 4,171 |
n = 39,937 · 2010-06-07 to 2026-09-15 · historical futures data
Split of the daily extreme across the sessions of the 24-hour cycle: Asia 09:00-15:00 Tokyo, London 08:00-16:30 local, and each contract's main session as 'New York': 9:30-16:00 ET for equity indices, 8:20-13:30 for gold, 8:20-15:00 for Treasuries, and the Tokyo cash session for the Nikkei, whose overlap and New York columns therefore do not mean the US session. London closes at 11:30 ET, so the overlap lasts two hours for indices and about three for gold and Treasuries; an extreme printed while both are open counts in 'London/NY overlap', not in either one. 'Outside sessions' are the minutes between the main-session close and the Asian open, and between the Asian close and the London open. The five columns add up to 100. Rough random-walk benchmark (arcsine law, UTC calendar day; Asia/London/overlap/New York/outside): indices ~34/18/6/16/26%, gold ~34/15/9/6/36%, Treasuries ~34/15/9/12/30%; it assumes constant volatility. The RTY series starts in 2017, not 2010.
After 11:30, indices and gold part ways#
In the four US index futures, the rest of the regular session, from 11:30 to 16:00, stays busy: between 27.1% for RTY and 29.4% for ES of the highs, against a 16% benchmark. Adding the overlap, the regular session holds close to half of the highs: 48.1% in ES, 49.5% in NQ, 49.3% in YM and 52.7% in RTY.
In gold the main session closes at 13:30, so after the overlap only two hours are left. That is where 8.9% of the highs and 7.4% of the lows show up, close to its 6% benchmark. Its full session, from 8:20 to 13:30, holds 36.6% of the highs, and three out of four arrive before 11:30.
Across the four Treasury contracts, the rest of the session, from 11:30 to 15:00, sits between 15.1% and 17.5% of the highs, somewhat above its 11 or 12% benchmark. What sets bonds apart is not that stretch, but the weight of the overlap.
This section says nothing about the Nikkei: its New York column actually measures the last fifteen minutes of the Tokyo session, which is why it comes out nearly empty, with 1.0% of the highs.
The low forms earlier than the high, except in bonds#
Comparing the two tables surfaces an asymmetry that repeats across the six equity and metal contracts: the day's low lands in Asia more often than the day's high does.
In ES it is 22.3% against 15.5%; in NQ, 20.6% against 14.1%; in YM, 20.8% against 15.8%; in RTY, 18.2% against 14.0%. Gold repeats the pattern, 28.9% against 26.2%, and so does the Nikkei, 48.3% against 44.0%.
The mirror image is in the outside-sessions column: across the four US index futures the high lands in that overnight hole between 16.8% and 19.4% of days, and the low only between 12.5% and 12.7%.
In the four Treasury contracts the asymmetry disappears. ZT even reverses it, with 22.9% of lows in Asia against 26.1% of highs, and ZF, ZN and ZB sit within a point of each other on the two figures.
The temptation is to explain it with the overnight upward drift documented in US equity indices for years: if price tends to rise while the US sleeps, the low has to form early and the high late. It is coherent, but this data does not prove it. It measures the split; it does not measure the cause.
Which session makes the daily low, across ten futures
ES, NQ, RTY, YM, NKD, GC, ZT, ZF, ZN, ZB
Swipe to see the sample →
| Instrument | Asia | London | London/NY overlap | New York | Outside sessions | Sessions |
|---|---|---|---|---|---|---|
| ES | 22.3% | 17.7% | 19.5% | 27.8% | 12.7% | 4,175 |
| NQ | 20.6% | 16.6% | 23.9% | 26.4% | 12.5% | 4,175 |
| RTY | 18.2% | 15.4% | 26.5% | 27.4% | 12.5% | 2,369 |
| YM | 20.8% | 17.5% | 21.8% | 27.3% | 12.6% | 4,179 |
| NKD | 48.3% | 24.2% | 0.0% | 1.2% | 26.3% | 4,184 |
| GC | 28.9% | 15.5% | 29.9% | 7.4% | 18.4% | 4,155 |
| ZT | 22.9% | 13.5% | 32.8% | 16.3% | 14.5% | 4,184 |
| ZF | 21.2% | 16.2% | 29.2% | 16.2% | 17.2% | 4,180 |
| ZN | 22.4% | 15.9% | 29.1% | 15.5% | 17.1% | 4,165 |
| ZB | 20.7% | 15.6% | 30.3% | 16.8% | 16.6% | 4,171 |
n = 39,937 · 2010-06-07 to 2026-09-15 · historical futures data
Split of the daily extreme across the sessions of the 24-hour cycle: Asia 09:00-15:00 Tokyo, London 08:00-16:30 local, and each contract's main session as 'New York': 9:30-16:00 ET for equity indices, 8:20-13:30 for gold, 8:20-15:00 for Treasuries, and the Tokyo cash session for the Nikkei, whose overlap and New York columns therefore do not mean the US session. London closes at 11:30 ET, so the overlap lasts two hours for indices and about three for gold and Treasuries; an extreme printed while both are open counts in 'London/NY overlap', not in either one. 'Outside sessions' are the minutes between the main-session close and the Asian open, and between the Asian close and the London open. The five columns add up to 100. Rough random-walk benchmark (arcsine law, UTC calendar day; Asia/London/overlap/New York/outside): indices ~34/18/6/16/26%, gold ~34/15/9/6/36%, Treasuries ~34/15/9/12/30%; it assumes constant volatility. The RTY series starts in 2017, not 2010. Same measurement as the high table, over the same sessions.
The Treasury curve behaves like a single instrument#
Between the 2-year contract and the 30-year there are large differences in duration, in volatility and in who trades them. In where the day's extreme forms, almost none.
The overlap makes the high on 30.4% of days in ZT, 27.9% in ZF, 26.8% in ZN and 27.4% in ZB. Four contracts, less than four points between the first and the last.
On the low the agreement holds: 29.1% to 32.8% in the overlap. And the rest of New York moves between 15.1% and 17.5% of the highs.
It is a negative result and that is why it is worth publishing: if anyone expected the short and long ends to run on different clocks, they do not. What maturity changes is how much they move, not when.
What this study does not say#
It does not say what time the extreme forms. It says which window it landed in, and the windows are wide: knowing it was "in London" still leaves between five and six and a half hours depending on the contract, and "in the overlap", between two and three.
It says nothing about direction or size. A high that beats the previous day's by one tick and one that breaks the weekly range count the same.
It is not a scheduling recommendation. Gold's extreme often landing in the overlap does not mean trading that stretch is better: the extreme is a point in the day, not an opportunity, and finding it in real time is a different problem.
And it does not cover FX, energy or agriculturals. Ten contracts from three families is what exists measured under this definition; the rest arrives when the report is computed, not before.
And the chance benchmark is approximate: it assumes constant volatility, and the daylight saving mismatch between Europe and the United States shifts the windows by an hour for a few weeks each year.
How to use this when preparing a session#
The practical question is not "what time does the high form?" but "does the window I trade contain the extreme more or less often than its share?".
For US index futures traded on a New York schedule, the answer is yes: the regular session holds close to half of the highs and of the lows, and the afternoon weighs as much as the morning.
For gold or bonds, the New York morning until 11:30 is the stretch that concentrates the most extremes for its length. That does not rule out trading later, but it is worth knowing before expecting the day to resolve late.
For one contract in detail, each instrument page carries its own extremes table next to gap and range. And the guide on what time the daily high forms develops the concept with fewer contracts and more context.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- Which session makes the daily high most often?
- In absolute terms, in the US index futures the rest of the New York session wins (27.1% to 29.4%), in gold and bonds the overlap with London (26.8% to 30.4%), and in the Nikkei, Asia (44.0%). Against what chance would give, the stretch that stands out most in nine of the ten is the overlap with London, which ends at 11:30 Eastern: it collects three or four times its share.
- When does gold make its daily high?
- Most often in the overlap between London and New York: 27.7% of the highs and 29.9% of the lows, over 4,155 sessions. Between 11:30 and the close of its session, at 13:30, 8.9%. This data measures the split; it does not explain the cause.
- Does the low form earlier than the high?
- In the five index futures and in gold, the low lands in the Asian session more often than the high: 22.3% against 15.5% in ES, for example. In the four Treasury contracts that asymmetry does not appear.
- Does the result change between the 2-year and the 30-year?
- Almost not at all. The overlap makes the high on between 26.8% and 30.4% of days across the four contracts, and the low between 29.1% and 32.8%. Maturity changes how much the contract moves, not when its extreme forms.
- Does this mean it is better to trade the London/NY overlap?
- No. The study locates the extreme once the day is over; it does not claim it is identifiable in real time or tradable. It is context for knowing whether the window you trade tends to contain the day's extreme point, nothing more.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
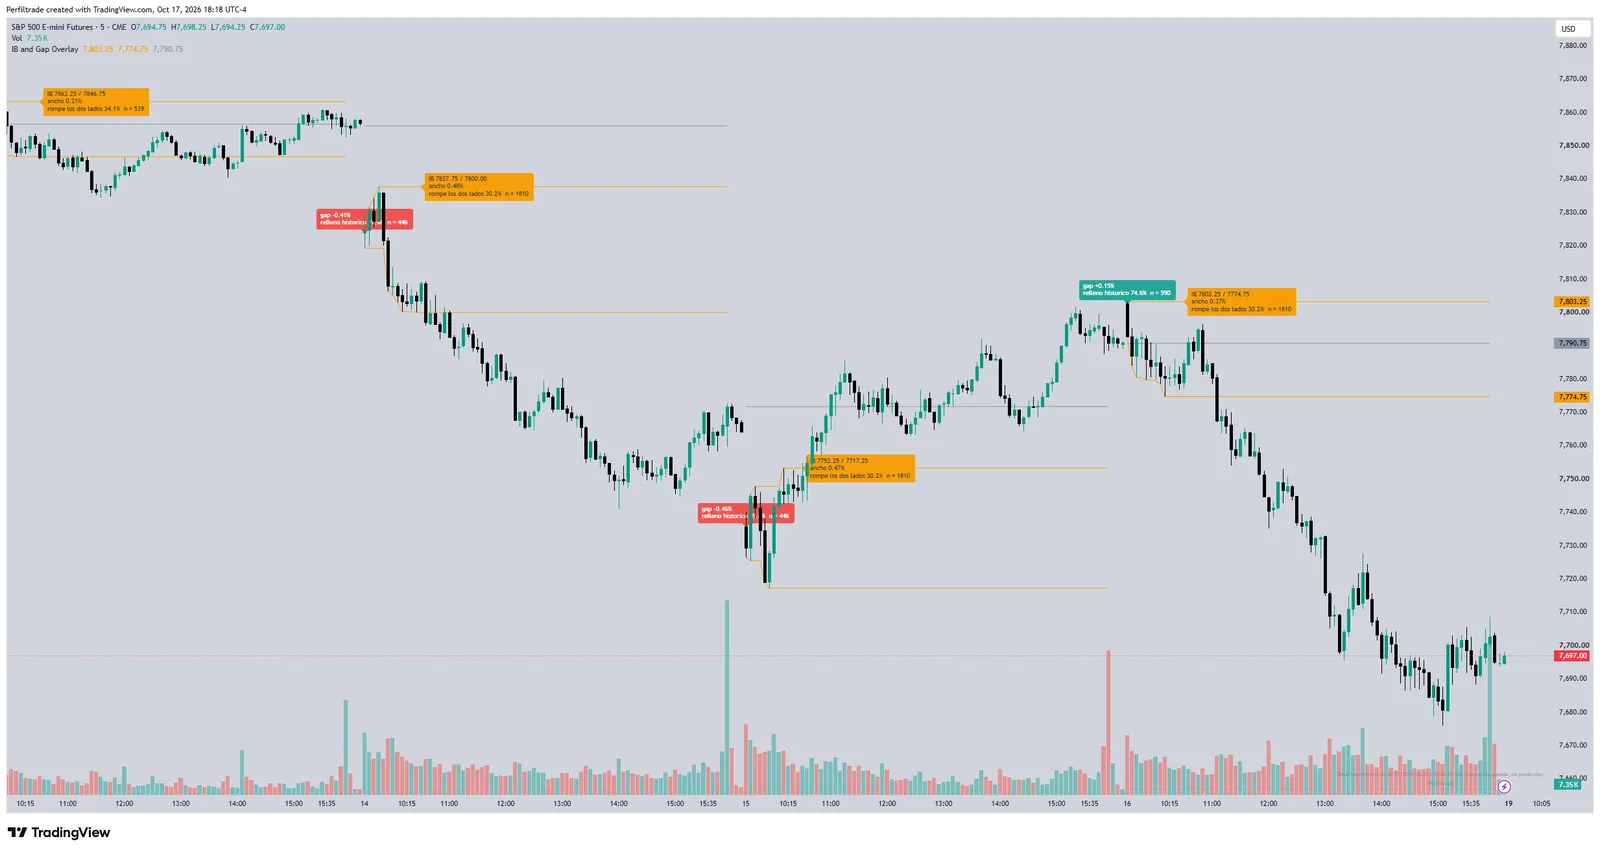
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 1, 2026). Which Session Makes the Daily High and Low: 10 Futures, 39,937 Sessions. https://www.perfiltrade.com/en/learn/session-high-low-statistics-ten-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →