Breaking Yesterday's Range: the 70% Against Chance Across 30 Futures and 109,260 Breaks
Updated October 17, 2026
The level everyone draws, counted across thirty contracts#
Yesterday's high and low are probably the two most-drawn levels in the world. Almost nobody publishes them with the figure that would make them checkable: when price takes one out, how does the session end?
Here is that count across the thirty futures contracts we have measured, from seven families: five index futures, five metals, two energies, three grains, eight currencies, five rates contracts and two cryptocurrencies. 109,260 breaks.
The result for the set: when the session takes out yesterday's high, it closes green 70.4% of the time. When it loses the low, it closes red 69.9%.
Seven out of ten, in both directions and across thirty different markets. It is by a distance the highest and steadiest number we have published, and it is worth saying up front exactly what it means and what it does not, because it is easy to read it as something it is not.
What this number measures, and why it is not a signal#
A break means that at some point in the session price took out the prior day's high, or lost its low. It does not matter when inside the day, nor by how much: one tick counts the same as 2%.
The percentage is the colour of the close, that is, the close against that same day's open. It does not measure whether the close ended beyond the broken level, which is a different and much harder question.
Here is the nuance that changes everything: breaking yesterday's high and closing green are not independent events. A session that rises from the open is both more likely to take out the previous high and more likely to close green. The 70.4% describes a relationship that is largely mechanical, not a prediction.
Put differently: this table does not say "if it breaks the high, buy". It says sessions that break the high are mostly bullish sessions, which is close to a tautology. Its value is in how constant the number is across markets.
A day that breaks both sides counts in both columns, so they do not add up to 100.
Breaking yesterday's range and the colour of the close, by family
30 contratos, 7 familias
Swipe to see the sample →
| Family | Breaks the high and closes green | Breaks the low and closes red | Breaks |
|---|---|---|---|
| Index futures | 70.4% | 67.5% | 18,706 |
| Metals | 71.4% | 71.6% | 19,377 |
| Energy | 68.5% | 70.3% | 7,826 |
| Grains | 69.4% | 70.5% | 11,554 |
| Currencies | 70.8% | 70.1% | 32,009 |
| Rates | 70.2% | 68.6% | 16,505 |
| Crypto | 68.9% | 74.4% | 3,283 |
| All 30 contracts | 70.4% | 69.9% | 109,260 |
n = 109,260 · 2010-06-07 to 2026-10-09 · historical futures data
A break means the session took out the prior day's high or lost its low at some point. The percentage is the colour of the close against that same day's open, not whether the close ended beyond the broken level. A day that breaks both sides counts in both columns, so they do not add up to 100. The benchmark is 50%. The RTY (2017), SR3 (2022), BTC (2017) and ETH (2021) series start later than the rest. Version of 12-Oct-2026, with data to 9-Oct-2026: a close equal to the open no longer counts as red, which used to inflate the low column; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
How much of the 70% comes from the break itself?#
That needs a comparison. For each break, the table takes the distance between the open and yesterday's high and looks at how many sessions that rose that same distance above their own open, to any level, closed green.
Breaking yesterday's high ends green 70.4% of the time (n = 55,574), and any level at the same distance above the open gives 69.8%: equal to chance. All days, with no condition, close green 50.3% (n = 113,968). Almost all of the 70% comes from the session having already risen to reach the level, more than from yesterday's high.
Same on the downside: losing the low ends red 69.9% (n = 53,451) and the control gives 69.4%. And when the session already opened above the high, it closes green only 47.7% (n = 3,040), below its control. Through 2021 and since 2022, the verdict does not change.
Breaking yesterday's range: how much of the green close comes from the break itself
30 contratos, 7 familias
Swipe to see the sample →
| Case | Closes in favour (%) | 95% interval | Control: same distance from the open (%) | Difference (points) | 95% interval of the difference | Reading | Days |
|---|---|---|---|---|---|---|---|
| All days: closes green | 50.3% | 50.0 to 50.6% | -- | -- | -- | — | 113,968 |
| Breaks yesterday's high: closes green | 70.4% | 70.0 to 70.7% | 69.8% | 0.5 | -0.1 to 1.1 | same as chance | 55,574 |
| Breaks the high, opened below it: closes green | 71.7% | 71.3 to 72.0% | 70.9% | 0.7 | 0.1 to 1.3 | above the control | 52,534 |
| Breaks the high, opened above it: closes green | 47.7% | 45.9 to 49.5% | 50.5% | -2.8 | -5.1 to -0.6 | below the control | 3,040 |
| Opens less than 0.25 ATR under the high and does not break it: closes green | 5.5% | 5.0 to 6.1% | -- | -- | -- | — | 7,380 |
| Breaks the high: closes above yesterday's high | 51.3% | 50.8 to 51.7% | 51.1% | 0.1 | -0.6 to 0.8 | same as chance | 55,574 |
| Breaks the high: closes green · through 2021 | 70.8% | 70.3 to 71.2% | 70.1% | 0.7 | 0.0 to 1.4 | same as chance | 38,074 |
| Breaks the high: closes green · from 2022 | 69.5% | 68.8 to 70.1% | 69.3% | 0.2 | -1.0 to 1.3 | same as chance | 17,500 |
| All days: closes red | 48.6% | 48.3 to 48.8% | -- | -- | -- | — | 113,968 |
| Loses yesterday's low: closes red | 69.9% | 69.5 to 70.3% | 69.4% | 0.5 | -0.1 to 1.2 | same as chance | 53,451 |
| Loses the low, opened above it: closes red | 71.1% | 70.7 to 71.5% | 70.5% | 0.7 | 0.0 to 1.3 | above the control | 50,791 |
| Loses the low, opened below it: closes red | 46.8% | 45.0 to 48.7% | 49.0% | -2.2 | -4.9 to 0.5 | same as chance | 2,660 |
| Opens less than 0.25 ATR above the low and does not lose it: closes red | 4.5% | 4.0 to 5.0% | -- | -- | -- | — | 7,099 |
| Loses the low: closes below yesterday's low | 50.0% | 49.6 to 50.4% | 49.5% | 0.5 | -0.2 to 1.3 | same as chance | 53,451 |
| Loses the low: closes red · through 2021 | 69.3% | 68.8 to 69.8% | 69.0% | 0.3 | -0.5 to 1.1 | same as chance | 35,837 |
| Loses the low: closes red · from 2022 | 71.3% | 70.6 to 71.9% | 70.3% | 1 | -0.2 to 2.2 | same as chance | 17,614 |
n = 109,025 · 2010-06-25 to 2026-10-15 · historical futures data
The 30 contracts of 'rango-previo-familia-3', daily bars by exchange trading date, 2010-06-25 to 2026-10-15; the sample is split into through 2021 and from 2022. Break = the session trades above the prior day's high (or below its low) at some point; 'in favour' = a close above the same day's open after breaking the high (below it after losing the low). Pairs of days on different contracts are left out, and so are the first 15 sessions of each series (no ATR); the data run to 2026-10-15 instead of 2026-10-09: 109,025 breaks against the 109,260 of 'rango-previo-familia-3' (on its same days the count gives exactly 70.4% and 69.9%). ATR = Wilder average of 14 sessions of the true range, known at the open. Control, same distance from the open: for a break whose level was D ATR above the open, the share of sessions of the same contract and the same period whose high rose more than D ATR above their own open (any level at that distance, not yesterday's high) and that closed green; in the 'closes above' row, those that closed more than D ATR above the open. If the session already opened beyond the level, the control is the share of all sessions. Difference = mean of (outcome minus control) in points, with a 95% interval that groups the breaks of all contracts by week. 'Same as chance' = the interval includes zero. Reading: a session that opened under the high and went past it has already risen that distance from the open, and a green close is then what any level gives: all days close green 50.3% of the time, the breaks 70.4% and the control 69.8%. The rate intervals treat each break as independent. No costs. It is what happened, not a signal.
Seven families inside seven points#
Metals 71.4% on the upside and 71.6% on the downside; currencies 70.8 and 70.1; index futures 70.4 and 67.5; rates 70.2 and 68.6; grains 69.4 and 70.5; crypto 68.9 and 74.4; energy 68.5 and 70.3.
Under three points separate the highest family from the lowest in the high-break column. In the low-break one it is almost seven, from 67.5% in index futures to 74.4% in crypto, which is the family with the smallest sample. Samples run from 3,283 breaks in crypto to 32,009 in currencies.
That uniformity is the finding, not the 70%. A number that repeats identically in palladium, in wheat and in the two-year note does not describe how a market behaves: it describes how the measurement is built.
And there is a small asymmetry, which is not general: in 18 of the 30 contracts, breaking the high and closing green happens more often than breaking the low and closing red, the five index futures among them; in 11 it is the other way round, and in 1 the two figures match. Five tenths of a point of difference across the set, in favour of the upside.
One contract measured wrong, and what the table does show#
The first published version of this table showed one contract far from the rest: three-month SOFR. It was not a market effect. It was an error in how the daily series chose the contract for that market: it switched contract almost every day.
Rebuilt, and measured from 2022, its row posts 68.5% in the high-break column and 70.4% in the low-break one, inside the band like the rest. Its sample is the smallest in the table: 1,009 breaks. Today no value in the table is anywhere near 50%.
The largest asymmetries are in bitcoin, at 68.5% against 74.4%, wheat, at 69.1% against 74.1%, and ether, at 69.7% against 74.4%. All three with the same shape: the downside higher than the upside. In the other direction the largest is ES, at 70.5% against 66.1%. No contract has more than 5.9 points between its two columns.
At the top end sits palladium, 74.8% and 74.5%, the highest contract in the table on both columns and also one of the least liquid. At the bottom, natural gas at 67.5% in the high-break column, and ES and NQ at 66.1% in the low-break one.
Breaking yesterday's range and the colour of the close, contract by contract
Los 30 contratos medidos
Swipe to see the sample →
| Contract | Breaks the high and closes green | Breaks the low and closes red | Breaks |
|---|---|---|---|
| ES | 70.5% | 66.1% | 4,122 |
| NQ | 69.7% | 66.1% | 4,180 |
| RTY | 69.5% | 69.2% | 2,345 |
| YM | 71.3% | 67.4% | 4,091 |
| NKD | 70.6% | 69.6% | 3,968 |
| GC | 70.4% | 69.5% | 3,903 |
| SI | 70.0% | 70.4% | 3,848 |
| HG | 70.8% | 70.7% | 3,927 |
| PL | 70.9% | 73.0% | 3,942 |
| PA | 74.8% | 74.5% | 3,757 |
| CL | 69.5% | 71.4% | 3,863 |
| NG | 67.5% | 69.3% | 3,963 |
| ZC | 70.5% | 68.5% | 3,855 |
| ZW | 69.1% | 74.1% | 3,829 |
| ZS | 68.6% | 68.7% | 3,870 |
| 6E | 70.6% | 70.2% | 4,018 |
| 6J | 71.1% | 71.1% | 3,917 |
| 6B | 71.9% | 71.5% | 3,997 |
| 6A | 70.6% | 67.5% | 4,031 |
| 6C | 68.8% | 70.9% | 4,048 |
| 6S | 70.2% | 71.2% | 4,010 |
| 6N | 71.7% | 69.4% | 4,048 |
| 6M | 71.0% | 69.0% | 3,940 |
| ZT | 69.7% | 69.1% | 3,698 |
| ZF | 70.4% | 67.7% | 3,950 |
| ZN | 70.3% | 68.2% | 3,918 |
| ZB | 70.7% | 69.1% | 3,930 |
| SR3 | 68.5% | 70.4% | 1,009 |
| BTC | 68.5% | 74.4% | 1,995 |
| ETH | 69.7% | 74.4% | 1,288 |
n = 109,260 · 2010-06-07 to 2026-10-09 · historical futures data
A break means the session took out the prior day's high or lost its low at some point. The percentage is the colour of the close against that same day's open, not whether the close ended beyond the broken level. A day that breaks both sides counts in both columns, so they do not add up to 100. The benchmark is 50%. Ordered by family: index futures, metals, energy, grains, currencies, rates and crypto. Version of 12-Oct-2026, with data to 9-Oct-2026: a close equal to the open no longer counts as red, which used to inflate the low column; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
Measured from the level: what is left in ES#
The figures above use the full 24-hour session and the colour of the day. Measuring from the level itself needs a different definition: the ES regular session (9:30-16:00 ET), with one-minute data, and the distance from the broken level to the close. That is 4,117 breaks, from 2010-06-28 to 2026-10-05. Under this definition the colour of the day is already a little lower: 64.8% green days on a high break and 63.2% red days on a low break.
From the level, the session closed above the broken high 61.1% of the time and below the broken low 52.6%. The average distance from the level to the close is practically zero: 0.01 ATR on the high, over 2,310 breaks, and 0.00 on the low, over 1,807. Measured from any minute after the break it is the same, and the difference is not significant.
There is a trap worth knowing. In 45.9% of high breaks the session had already opened above the level. Measure "from the level" without accounting for that and the opening gap is added to the distance, so the number looks like a clear effect. Measuring from the open on those days, as this table does, the effect disappears.
Breaking yesterday's range: what happened from the level to the close
ES
Swipe to see the sample →
| Break | Green (or red) day from the open | Closes beyond the level | Average distance from the level to the close (ATR) | Average distance from any minute after the break (ATR) | Days |
|---|---|---|---|---|---|
| Breaks the high (green day) | 64.8% | 61.1% | 0.01 ATR | 0.00 ATR | 2,310 |
| Breaks the low (red day) | 63.2% | 52.6% | 0.00 ATR | 0.00 ATR | 1,807 |
n = 4,117 · 2010-06-28 to 2026-10-05 · historical futures data
Break = today's regular session (9:30-16:00 ET) trades above yesterday's regular-session high or below its low. 'Green/red' compares today's close with its open; 'closes beyond' compares the close with the broken level. The distance runs from the level to the close, in 14-session ATR known at the open, signed in the direction of the break; if the session already opened beyond the level, it is measured from the open. The control column measures the same from any minute after the break; the difference between the two is not significant. Days with a contract change excluded. In 45.9% of the breaks of the high the session already opened above it: measured from the level without that correction, the gap would be added to the distance. Regular session: the colour of the day gives somewhat less than the 70% of the full 24-hour session.
What this study does not say#
It does not say the break is tradable. The colour of the close is known at the close; between the break and that hour there is a whole session of travel this measurement cannot see. The previous section measures it in ES, from the level, and the edge disappears.
It does not say how much. A session that closes a tick above its open counts the same as one that closes 3% up, and the difference between those two is the entire trade.
It does not measure whether the close ended beyond the broken level, which is the question that actually matters to anyone trading breakouts. That measurement exists for the Initial Balance and gives much lower numbers, between 43.6% and 57.4%.
And it does not separate breaks by size or by time of day. A break in the first five minutes and one at 15:55 count the same.
Correction of October 2026: the two tables for the 30 contracts were recomputed with data through 2026-10-09, with the currency data from before 2016 cleaned, the day defined as the market's trading day, and a session that closes exactly at its open no longer counted as red; the three-month SOFR series, which had an error in how the contract was chosen, was rebuilt. The set moved from 69.8% to 70.4% on a high break and from 70.8% to 69.9% on a low break, with 109,260 breaks instead of 112,250.
So what is it good for#
As a benchmark against which to judge any claim about previous-range breaks. If someone shows a system with a 70% hit rate defined this way, they have found nothing: that is the background number across thirty markets.
Also for knowing where the effect is not. If the number were real market behaviour, the families would separate. They barely do.
And as a contrast with the demanding version. Ask instead whether the session closed beyond the broken level, rather than merely green, and the percentages fall from 70% to the 50s. The gap between those two questions is the gap between a statistic that sounds good and one you can use.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- If price breaks yesterday's high, does the session close green?
- 70.4% of the time across the 30 contracts (55,574 breaks of the high). But any level at the same distance above the open gives 69.8%: equal to chance. The 70% comes from the session having already risen to reach the level; all days close green 50.3%.
- Does it work better on the upside or the downside?
- The upside, very slightly and not everywhere: 70.4% against 69.9% for the set, and the upside is the higher one in 18 of the 30 contracts, the five index futures among them; in 11 it is the downside and in 1 they match. The largest asymmetries, though, lean to the downside: bitcoin (68.5 against 74.4), wheat (69.1 against 74.1) and ether (69.7 against 74.4).
- Are there markets where this does not hold?
- None. The thirty contracts fit between 67.5% and 74.8% on the high break, and between 66.1% and 74.5% on the low break. The first published version showed three-month SOFR far from the rest: that was an error in how the daily series chose the contract for that market, not a market effect. Rebuilt, its row posts 68.5% and 70.4%.
- Can I trade this 70%?
- Not as it stands. In ES, measured in the regular session from the broken level to the close, the average result is practically zero (0.01 ATR over 2,310 high breaks) and cannot be told apart from entering at random after the break. It is a background benchmark, not an entry rule.
- Why do the two columns not add up to 100?
- Because they are two independent measurements over different populations: the days that broke the high and the days that broke the low. A day that breaks both appears in each.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
Key Levels: How far did price travel from the open in past sessions?
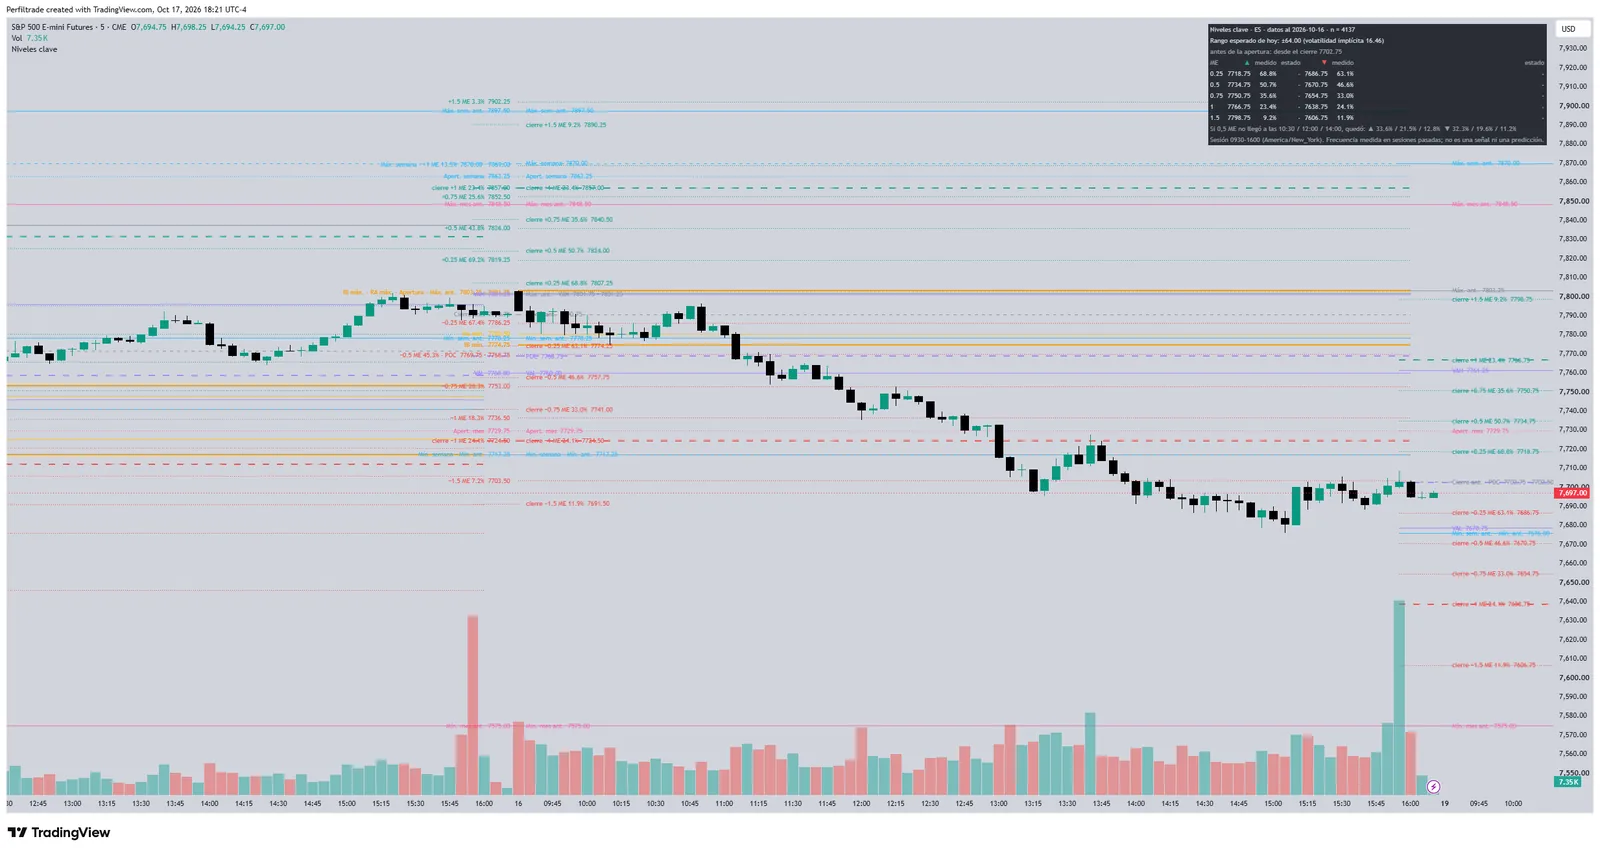
A ladder of distances from the open, from 0.25 to 1.5 times the day's typical move, with how often price reached each rung and its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 17, 2026). Breaking Yesterday's Range: the 70% Against Chance Across 30 Futures and 109,260 Breaks. https://www.perfiltrade.com/en/learn/previous-day-range-break-thirty-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →