Monday Has the Most Inside Days: 30 Futures and 109,806 Sessions
Updated October 12, 2026
Monday is the day that stays inside most often#
An inside day is a session whose high and low both fit within the previous day's range. Nothing new happened: the market moved inside what it already knew.
Measured across the thirty contracts we have, it happens in 15.2% of sessions. A bit more than one in seven. That number on its own is not interesting.
What is interesting is how it splits by day of the week: 20.2% of Mondays and 13.8% of Tuesdays. One Monday in five, against slightly fewer than one Tuesday in seven.
That is a gap of about six points, and it is not spread evenly. It is concentrated in two families, interest rates and currencies. In energy and in grains there is nothing.
The full week#
Monday 20.2%, Tuesday 13.8%, Wednesday 13.8%, Thursday 13.5%, Friday 15.2%. Across 109,806 sessions from thirty contracts, of which 20,155 are Mondays.
Monday is the highest and the only one that stands apart. The other four days fit inside less than two points, with Friday a touch above the middle of the week.
Before looking for an explanation it is worth saying what that Monday actually is. The day is measured as the exchange trading day: from 18:00 ET of the previous evening to 17:00 ET. So Monday starts on Sunday evening, and the session before it is Friday's. In between sit two days with no session.
So the comparison is not "Monday versus Tuesday" on equal terms. It is "the session that follows a long break" versus "the session that follows another session". The difference exists, but it is moderate and depends heavily on the market.
How often the session stays inside yesterday's range
30 contratos, 7 familias
Swipe to see the sample →
| Day | Stays inside | Sessions |
|---|---|---|
| Monday | 20.2% | 20,155 |
| Tuesday | 13.8% | 22,696 |
| Wednesday | 13.8% | 22,720 |
| Thursday | 13.5% | 22,548 |
| Friday | 15.2% | 21,687 |
| Every session | 15.2% | 109,806 |
n = 109,806 · 2010-06-07 to 2026-10-09 · historical futures data
Inside day = its high and low both fit within the prior day's range. The denominator is every session, not only those following an inside day. It is measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET), so Monday comes after two days without a session in all thirty contracts, the bitcoin and ether futures included, which close for the weekend even though their underlying keeps trading. Those two, futures whose underlying trades at the weekend, are the only control available and the comparison is not conclusive, with few Mondays: BTC 18.1% on Monday (299 Mondays) against 19.6% from Tuesday to Friday, and ETH 20.5% (190 Mondays) against 17.9%. Energy and grains do not show the Monday excess either: 11.3% against 13.7% in crude and gas, and 14.8% against 14.5% in corn, wheat and soybeans. Version of 12-Oct-2026, with data to 9-Oct-2026: the note about the Monday of the bitcoin and ether futures is corrected; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
Rates and currencies have it; energy and grains do not#
The effect is clear in the eight currencies and the five interest-rate contracts: in all thirteen, Monday beats the rest of the week by more than seven points. The Canadian dollar goes from 11.0% to 26.4% and the euro from 11.8% to 24.5%, more than double in both cases. The five-year note, from 14.3% to 25.3%. The two-year posts 31.2%. The highest Monday in the table belongs to three-month SOFR (SR3), 32.6%, on the shortest sample among the rates: 1,198 sessions, measured since 2022.
In index futures and metals it is smaller and uneven. The ES goes from 12.2% to 17.4% and the YM from 12.9% to 17.8%, about five points; the NQ (12.2% to 14.2%), the RTY (12.2% to 13.9%) and the NKD (14.6% to 16.4%) stay at two points or less. In metals, gold (14.7% to 22.7%) and silver (15.8% to 21.3%) show it; platinum barely does (14.2% to 16.5%), copper posts 14.7% on both sides and palladium inverts it (16.5% against 17.9%).
And in energy and grains it does not appear. Crude oil posts 11.9% on Mondays against 13.8% across the rest of the week, and natural gas 10.5% against 13.6%: both invert it. Corn (15.1 on both sides) and wheat (14.0 against 14.3) do not move, and soybeans stay at 15.4 against 14.2.
On a simple count, Monday is higher than the rest of the week in 23 of the 30 contracts, equal in two and lower in five. But that count misleads: outside rates, currencies, gold, silver, the ES and the YM, the difference is around three points at most, one way or the other.
The inside day: Monday against the rest of the week
Los 30 contratos medidos
Swipe to see the sample →
| Contract | Monday | Tuesday to Friday | All | Sessions |
|---|---|---|---|---|
| ES | 17.4% | 12.2% | 13.1% | 3,946 |
| NQ | 14.2% | 12.2% | 12.6% | 3,961 |
| RTY | 13.9% | 12.2% | 12.5% | 2,260 |
| YM | 17.8% | 12.9% | 13.7% | 3,980 |
| NKD | 16.4% | 14.6% | 14.9% | 3,933 |
| GC | 22.7% | 14.7% | 16.2% | 4,030 |
| SI | 21.3% | 15.8% | 16.8% | 4,047 |
| HG | 14.7% | 14.7% | 14.7% | 4,045 |
| PL | 16.5% | 14.2% | 14.6% | 4,064 |
| PA | 16.5% | 17.9% | 17.6% | 4,053 |
| CL | 11.9% | 13.8% | 13.5% | 3,894 |
| NG | 10.5% | 13.6% | 13.2% | 3,676 |
| ZC | 15.1% | 15.1% | 15.1% | 3,803 |
| ZW | 14.0% | 14.3% | 14.3% | 3,791 |
| ZS | 15.4% | 14.2% | 14.4% | 3,678 |
| 6E | 24.5% | 11.8% | 14.2% | 4,009 |
| 6J | 22.8% | 15.0% | 16.5% | 3,986 |
| 6B | 24.4% | 13.3% | 15.4% | 4,032 |
| 6A | 21.8% | 12.6% | 14.3% | 4,008 |
| 6C | 26.4% | 11.0% | 14.1% | 4,064 |
| 6S | 24.2% | 12.5% | 14.8% | 4,048 |
| 6N | 22.0% | 12.1% | 14.0% | 3,936 |
| 6M | 24.1% | 12.7% | 15.0% | 3,992 |
| ZT | 31.2% | 17.8% | 20.4% | 4,072 |
| ZF | 25.3% | 14.3% | 16.3% | 4,019 |
| ZN | 25.2% | 13.7% | 15.9% | 4,036 |
| ZB | 20.8% | 13.1% | 14.6% | 4,073 |
| SR3 | 32.6% | 23.9% | 25.6% | 1,198 |
| BTC | 18.1% | 19.6% | 19.4% | 1,932 |
| ETH | 20.5% | 17.9% | 18.3% | 1,240 |
n = 109,806 · 2010-06-07 to 2026-10-09 · historical futures data
Inside day = its high and low both fit within the prior day's range. The denominator is every session, not only those following an inside day. It is measured on the exchange trading day (from 18:00 ET the evening before to 17:00 ET), so Monday comes after two days without a session in all thirty contracts, the bitcoin and ether futures included, which close for the weekend even though their underlying keeps trading. Those two, futures whose underlying trades at the weekend, are the only control available and the comparison is not conclusive, with few Mondays: BTC 18.1% on Monday (299 Mondays) against 19.6% from Tuesday to Friday, and ETH 20.5% (190 Mondays) against 17.9%. Energy and grains do not show the Monday excess either: 11.3% against 13.7% in crude and gas, and 14.8% against 14.5% in corn, wheat and soybeans. Ordered by family: index futures, metals, energy, grains, currencies, rates and crypto. Version of 12-Oct-2026, with data to 9-Oct-2026: the note about the Monday of the bitcoin and ether futures is corrected; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The control that looked clean is not#
Bitcoin and ether futures are the only ones in the table whose underlying trades over the weekend. The future also closes, like all the others; what does not stop is the reference price.
That made them look like a control group: if the Monday effect came from the break, something different should show up there. The result is mixed. Bitcoin posts 18.1% on Mondays against 19.6% across the rest of the week; ether, 20.5% against 17.9%. One each way, and on small samples: 1,932 and 1,240 sessions in total, of which only 299 and 190 are Mondays.
Besides, they are not the only ones without the effect. Energy and grains do stop for the weekend and do not show it either: crude oil 11.9% against 13.8%, natural gas 10.5% against 13.6%, corn 15.1% on both sides, wheat 14.0% against 14.3%. The break, on its own, does not explain who has an inside Monday and who does not.
What is left is a description, not a cause: the effect lives in rates and currencies, shows faintly in gold, silver and two index futures, and is missing in the rest. Why those families and not others is a question for another study, one that measures the same thing hour by hour.
What this study does not say#
It does not say what price does after the inside day. Not whether it breaks up or down, nor when, nor how far. It only counts how often the session stayed inside.
It does not say Monday is a quiet day. An inside day can have a large range if Friday's was enormous; inside is a comparison, not a measure of volatility.
It does not adjust for holidays. A Tuesday following a Monday holiday behaves like a Monday and is counted here as a Tuesday, which if anything dilutes the effect rather than inflating it.
And it does not prove the cause. The weekend break is the explanation closest to hand, but there are markets with the same break and no effect. Correction of October 2026: the tables were recomputed with data through 2026-10-09, with currency data before 2016 cleaned, with the day defined as the exchange trading day and with a few contract series rebuilt, among them three-month SOFR (SR3), now measured since 2022; the Monday figure for the 30 contracts went from 23.2% to 20.2%, mostly because of the change in the definition of the day.
What to do with it when you plan the week#
The direct part: if you trade currencies, between 21.8% and 26.4% of Mondays stay inside the previous session's range, depending on the contract, against 11.0% to 15.0% across the rest of the week. Interest rates look much the same. If your Monday plan expects the market to define something new, count on it not doing so roughly one time in four.
The indirect part, and probably the more useful one: in those markets, any daily statistic that mixes Mondays in with the rest of the week is mixing two different populations. In a study about breakouts, about ranges or about gaps it is worth looking at Monday separately.
And if you trade crude oil, natural gas or grains, this effect is not yours; in crypto, the table is not enough to say. Which is, in its own way, the most useful result in the table: knowing when a widely quoted pattern does not apply to your market.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- What is an inside day?
- A session whose high and low both fit within the previous day's range. The market made no new extreme in either direction. Here it is measured over every session, not only those following another inside day.
- How often does it happen?
- 15.2% of sessions across the 30 contracts, over 109,806 sessions. The split by day is uneven: 20.2% on Mondays and between 13.5% and 15.2% across the rest of the week.
- Why does Monday have more inside days?
- The study does not prove it. Monday is the only session that follows two days without trading, but that is not enough: energy and grains have the same break and do not show the effect (crude oil, 11.9% on Mondays against 13.8% the rest). Bitcoin and ether futures, whose underlying trades over the weekend, give a mixed result on small samples: 18.1% against 19.6% and 20.5% against 17.9%.
- Which markets show it most strongly?
- Currencies and interest rates. The Canadian dollar goes from 11.0% to 26.4% on Mondays and the euro from 11.8% to 24.5%, more than double; the five-year note, from 14.3% to 25.3%. The two-year note posts 31.2%. The highest Monday in the table belongs to three-month SOFR (SR3), 32.6%, over 1,198 sessions.
- Is it useful for trading Mondays?
- On its own, no: the table does not say which way the market will break afterwards, nor when. Its soundest use is as a warning: in currencies and interest rates, any daily statistic that lumps Mondays in with the rest of the week is mixing two populations that behave differently.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
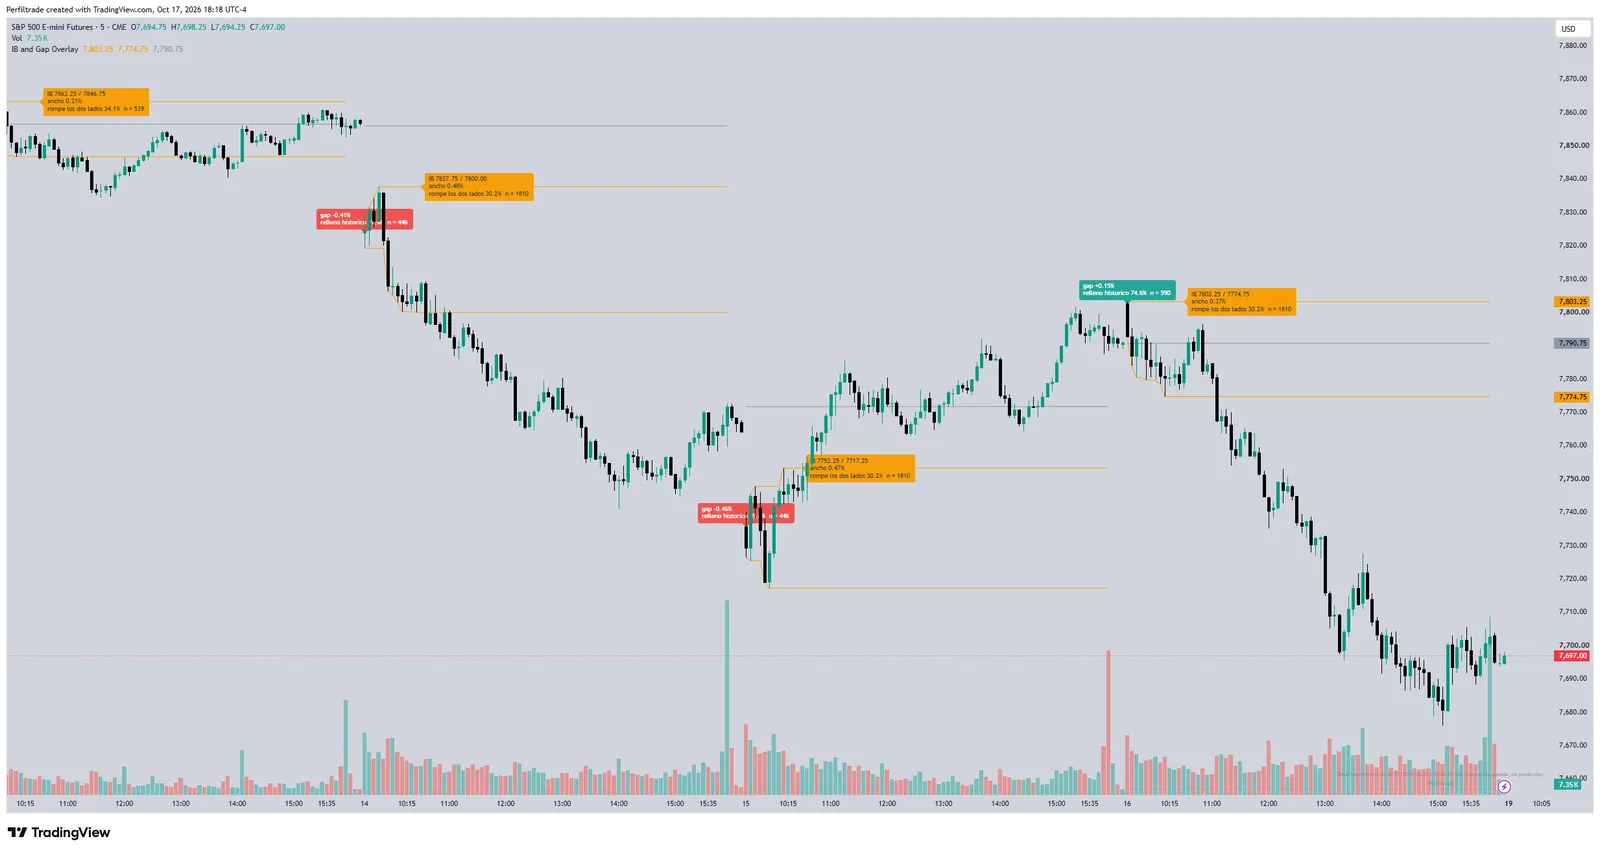
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). Monday Has the Most Inside Days: 30 Futures and 109,806 Sessions. https://www.perfiltrade.com/en/learn/monday-is-the-inside-day
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →