Do Streaks Exist? Daily Continuation Across 30 Futures and 115,233 Sessions
Updated October 12, 2026
The line everyone repeats and almost nobody has counted#
"It's been up three days, it's due for a pullback." That is probably the most widespread idea in short-term analysis, and it has one advantage over most of the others: it is easy to check. Count how often, after a run of N days in the same direction, the next day carried on in that direction.
Here is that count across thirty futures contracts from seven families: the five index futures, five metals, two energies, three grains, eight currencies, five rates contracts and two cryptocurrencies. 115,233 classified days, most of the series starting in 2010.
The result in one line: after three or more days in the same direction, the set continues 48.1% of the time. After two days, 48.3%. After one, 48.4%.
So yes, there is a very slight tendency to reverse, and it is almost the same after one day as after three: three tenths apart. Three is not a threshold. It is a number that sounds good when you say it out loud.
How it is measured, and why 50% is the benchmark#
Each day's direction is measured from its own open to its own close, not against the previous close. A three-day streak is three consecutive days closing in the same direction. The percentage in the table is how often the next day also closed in that direction instead of turning around.
The benchmark is not a number anyone picked: it is 50%. Above it the market carries on more often than it turns; below it, the other way round. The belief being tested predicts clearly below 50% in the three-or-more column, and well below, or it would be of no use to anyone.
One detail shaves a fraction off almost every market: a day that closes exactly at its open counts as not continuing, and it also ends the streak. In most markets there are few of them, but they explain part of why nearly every figure lands under 50. In three-month SOFR and the two-year note they weigh more: 9% and 6% of their sessions close unchanged, and that takes several points off.
The series do not all start together. Most begin in June 2010; the RTY in 2017, SOFR in 2022, bitcoin in 2017 and ether in 2021. Their samples are smaller because of it, and the days column is in the table precisely so it can be discounted while reading.
Correction of October 2026: the tables were recomputed with data through 9 October 2026, with the currency data from before 2016 cleaned, the day defined as the market's full trading day, and a day that closes exactly at its open no longer counted as a continuation. The three-month SOFR series, which had a contract-selection error, was rebuilt and is no longer the highest value in the study; the figures for the whole set fell by four to eight tenths against those first published (49.0%, 48.7% and 48.9% across 117,560 days).
Continuation after a streak, by contract family
30 contratos, 7 familias
Swipe to see the sample →
| Family | After 1 day | After 2 days | After 3 or more | Days |
|---|---|---|---|---|
| Index futures | 47.6% | 50.1% | 50.4% | 19,118 |
| Metals | 48.2% | 47.5% | 47.3% | 20,920 |
| Energy | 48.4% | 48.8% | 45.9% | 8,396 |
| Grains | 49.2% | 47.9% | 49.6% | 12,198 |
| Currencies | 49.1% | 48.4% | 48.0% | 33,358 |
| Rates | 47.4% | 47.0% | 45.9% | 17,520 |
| Crypto | 48.3% | 49.0% | 49.8% | 3,723 |
| All 30 contracts | 48.4% | 48.3% | 48.1% | 115,233 |
n = 115,233 · 2010-06-07 to 2026-10-09 · historical futures data
Streak = consecutive days closing in the same direction, each day measured from its own open to its own close. The percentage is how often the next day closed in that same direction instead of turning around; a day that closes exactly at its open counts as not continuing, which shaves a fraction off almost every market and several points off SR3 and ZT, where 9% and 6% of sessions close unchanged. The benchmark is 50%: above it the market carries on more than it turns, below it the other way round. The RTY (2017), SR3 (2022), BTC (2017) and ETH (2021) series start later than the rest. Version of 12-Oct-2026, with data to 9-Oct-2026: a day that closes at its open no longer counts as a down day or as part of a streak; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The weekly report, every Sunday
One email a week: what moved the macro picture, next week's calendar, rates and COT positioning, and the new study with its sample size. No signals; unsubscribe in one click.
Seven families, and not one leaves the band#
Index futures 50.4%, crypto 49.8%, grains 49.6%, currencies 48.0%, metals 47.3%, and energy and rates both at 45.9%, all in the three-or-more column.
Five of the seven families fit inside 3.1 points. The other two, energy and rates, sit 1.4 points below the next one. Energy is just two contracts, crude oil and natural gas, with 8,396 days: the smallest sample in the study after crypto. In rates, the two shortest-maturity contracts weigh on the figure, and they are the ones with the most unchanged sessions.
What does not show up anywhere is a family where streaks work. The highest, index futures, stops at 50.4%, four tenths above a coin flip. And the cryptocurrencies, the market where momentum gets talked about most, post 49.8% after three days, across 3,723 days.
That is what makes this hard to wave away. If streaks worked in one family and not another, the measurement would be worth arguing about. That none of the seven gets past 50.4%, whether index futures, grains or bitcoin, points at there being nothing to use.
Contract by contract: 23 of 30 below 50%#
Twenty-three of the thirty contracts continue less than half the time after a run of three days or more. Six are above and one, the Mexican peso, lands right at 50.0%. That split alone says the tendency to turn is real but small: if it did not exist, the split would be roughly fifteen and fifteen.
The full range runs from three-month SOFR at 43.6% to the Dow at 52.4%. Neither stands alone: right above SOFR are the ten-year note at 44.8% and the thirty-year bond at 45.2%, and right below the Dow is the Nasdaq at 51.6%.
Almost nine points from top to bottom looks like a lot until you read the days column. SOFR has 1,117 measured days and the Russell 2,386, against 4,191 for the Dow. Short samples explain some of the table's extremes, but not all of them: the Dow and the ten-year note have the full series.
The other two columns behave in a similar way. After one day, 42.2% in SOFR to 50.6% in the euro. After two, 43.9% in the two-year note to 52.7% in the Dow. No contract marks the extreme in all three columns at once, which is what it would take to call it a behaviour of its own. The closest is SOFR, the lowest in two of the three, and it is also the shortest sample in the study.
Continuation after a streak, contract by contract
Los 30 contratos medidos
Swipe to see the sample →
| Contract | After 1 day | After 2 days | After 3 or more | Days |
|---|---|---|---|---|
| ES | 47.2% | 49.6% | 51.0% | 4,176 |
| NQ | 47.2% | 51.8% | 51.6% | 4,195 |
| RTY | 49.4% | 47.8% | 45.6% | 2,386 |
| YM | 46.9% | 52.7% | 52.4% | 4,191 |
| NKD | 48.1% | 47.8% | 48.9% | 4,170 |
| GC | 46.6% | 47.0% | 45.4% | 4,190 |
| SI | 48.0% | 44.4% | 46.1% | 4,168 |
| HG | 48.1% | 47.3% | 46.3% | 4,181 |
| PL | 48.3% | 49.8% | 48.2% | 4,190 |
| PA | 50.4% | 49.2% | 49.8% | 4,191 |
| CL | 47.3% | 49.6% | 46.5% | 4,204 |
| NG | 49.5% | 48.0% | 45.3% | 4,192 |
| ZC | 49.8% | 45.2% | 50.5% | 4,036 |
| ZW | 49.6% | 50.1% | 49.0% | 4,083 |
| ZS | 48.1% | 48.4% | 49.3% | 4,079 |
| 6E | 50.6% | 49.9% | 45.3% | 4,187 |
| 6J | 48.7% | 48.5% | 47.0% | 4,175 |
| 6B | 50.5% | 50.0% | 48.8% | 4,171 |
| 6A | 47.8% | 49.1% | 46.3% | 4,167 |
| 6C | 49.0% | 47.3% | 47.7% | 4,160 |
| 6S | 48.2% | 47.8% | 48.6% | 4,174 |
| 6N | 49.9% | 46.6% | 50.2% | 4,179 |
| 6M | 48.3% | 47.8% | 50.0% | 4,145 |
| ZT | 45.8% | 43.9% | 47.8% | 3,973 |
| ZF | 49.0% | 47.3% | 46.3% | 4,155 |
| ZN | 48.0% | 48.6% | 44.8% | 4,132 |
| ZB | 48.3% | 48.5% | 45.2% | 4,143 |
| SR3 | 42.2% | 46.1% | 43.6% | 1,117 |
| BTC | 47.7% | 49.5% | 50.1% | 2,262 |
| ETH | 49.4% | 48.1% | 49.4% | 1,461 |
n = 115,233 · 2010-06-07 to 2026-10-09 · historical futures data
Streak = consecutive days closing in the same direction, each day measured from its own open to its own close. The percentage is how often the next day closed in that same direction instead of turning around; a day that closes exactly at its open counts as not continuing, which shaves a fraction off almost every market and several points off SR3 and ZT, where 9% and 6% of sessions close unchanged. The benchmark is 50%: above it the market carries on more than it turns, below it the other way round. Ordered by family: index futures, metals, energy, grains, currencies, rates and crypto. Version of 12-Oct-2026, with data to 9-Oct-2026: a day that closes at its open no longer counts as a down day or as part of a streak; SR3 is measured from 2022 on a single quarterly contract (its series used to jump between contracts almost daily and its row was not valid) and in the other markets a contract roll needs two days running of higher volume. Currency data before 2016 is cleaned of off-market prices.
The two extremes, and why they are no use either#
The Dow posts 52.4% after three days or more, the highest figure in the study, across 4,191 days. Next come the Nasdaq at 51.6% and the S&P 500 at 51.0%. All three are US stock index futures with many companies in common, so they count almost as one observation, not three. And the fourth US index, the Russell, posts 45.6%, among the lowest in the table.
Three-month SOFR sits at the other end with 43.6%, across 1,117 days, the shortest series in the study, from 2022. It is also the contract where most sessions close unchanged, 9%, and each one counts as not continuing. Right behind it are the ten-year note at 44.8% and the thirty-year bond at 45.2%. That rates turn a little more often than the rest is plausible; that about five points off a coin flip is tradable is another matter.
And here is the deeper problem with both extremes: to trade them you would have had to pick them in advance. Across thirty contracts, the highest landing 2.4 points from the centre is what chance produces. The lowest lands 6.4 away, but it is the shortest series and the one with the most unchanged sessions. Pointing at them after seeing the table is picking the winner with the race already run.
What this study does not say#
It says nothing about size. A day that continues by a tick and one that continues by 3% count the same. It is entirely possible that continuations are larger than reversals, or the reverse; this measurement cannot see it.
It says nothing about what happens inside the day. A day that opens against the streak, travels 2% and closes in the streak's direction counts as a continuation, however untradable it was.
It does not separate runs longer than three days. The last column groups three, four, seven and fifteen days into one bucket, and there could be differences inside it. That is the cut the report provides.
And it does not say momentum does not exist. It says that, measured this way, daily and open to close, it does not show up. Other timeframes and other definitions are a different study.
What to do with this when you plan the session#
First, stop using the streak as an argument. Neither for nor against: three days up make neither the fourth nor the reversal any more likely, in none of the thirty contracts measured.
Second, be suspicious of any rule with a round number inside it. Three days, five candles, two touches. If the threshold were real it would show in the table as a step between the two-day column and the three-day one. There is no step: there is 48.3% and 48.1%.
Third, and this is the only actionable part: if a strategy depends on the market turning after a run, this study caps it. The lowest cell in the table is SOFR after one day, at 42.2%, but the short sample and the unchanged sessions, which are not reversals, weigh on it. Outside the two shortest-maturity rates contracts, the most edge available, before costs, is 5.6 points on a coin flip: silver after two days, at 44.4%. Any commission and any spread eats that.
For a single contract, each instrument page carries its own streak table next to range, gap and inside day.
Free PDF: 20 futures figures with their sample
The figures from our studies on one sheet, each with its n and date range (in Spanish for now). Subscribe to the weekly report and download it right away; the link also comes in the welcome email.
Frequently asked questions
- After three days up, is the market more likely to fall?
- Slightly, and only slightly. Across the 30 contracts measured, after a run of three days or more the market continues in that direction 48.1% of the time, across 115,233 days. That is 1.9 points below a coin flip, and a similar deviation shows up after a single-day run (48.4%).
- Is there any market where streaks do work?
- Not in a way you could use. The highest figure after three days or more is the Dow at 52.4%, followed by the Nasdaq (51.6%) and the S&P 500 (51.0%), three US index futures that are very much alike. The other end is three-month SOFR, at 43.6% and with the shortest series in the study (1,117 days, from 2022). With thirty contracts on the table, some extremes far from centre is what chance produces.
- How is a streak defined here?
- Consecutive days closing in the same direction, with each day measured from its own open to its own close. The three-or-more bucket includes longer runs. A day that closes exactly at its open counts as not continuing and ends the streak.
- Do cryptocurrencies behave differently?
- Not in this measurement. Bitcoin and ether together give 49.8% continuation after three days or more, across 3,723 days, between index futures (50.4%) and grains (49.6%). The market where momentum gets discussed most does not show it on a daily scale.
- So momentum does not exist?
- That is not what this study says. It says that, measured in days and open to close, yesterday's direction carries no information about today's in any of the 30 contracts. Momentum on other timeframes, or with other definitions of direction, is a different question this table does not answer.
These numbers, instrument by instrument
See all 30 instruments →Take it to your chart, free
IB and gap: How often did a gap like today's fill?
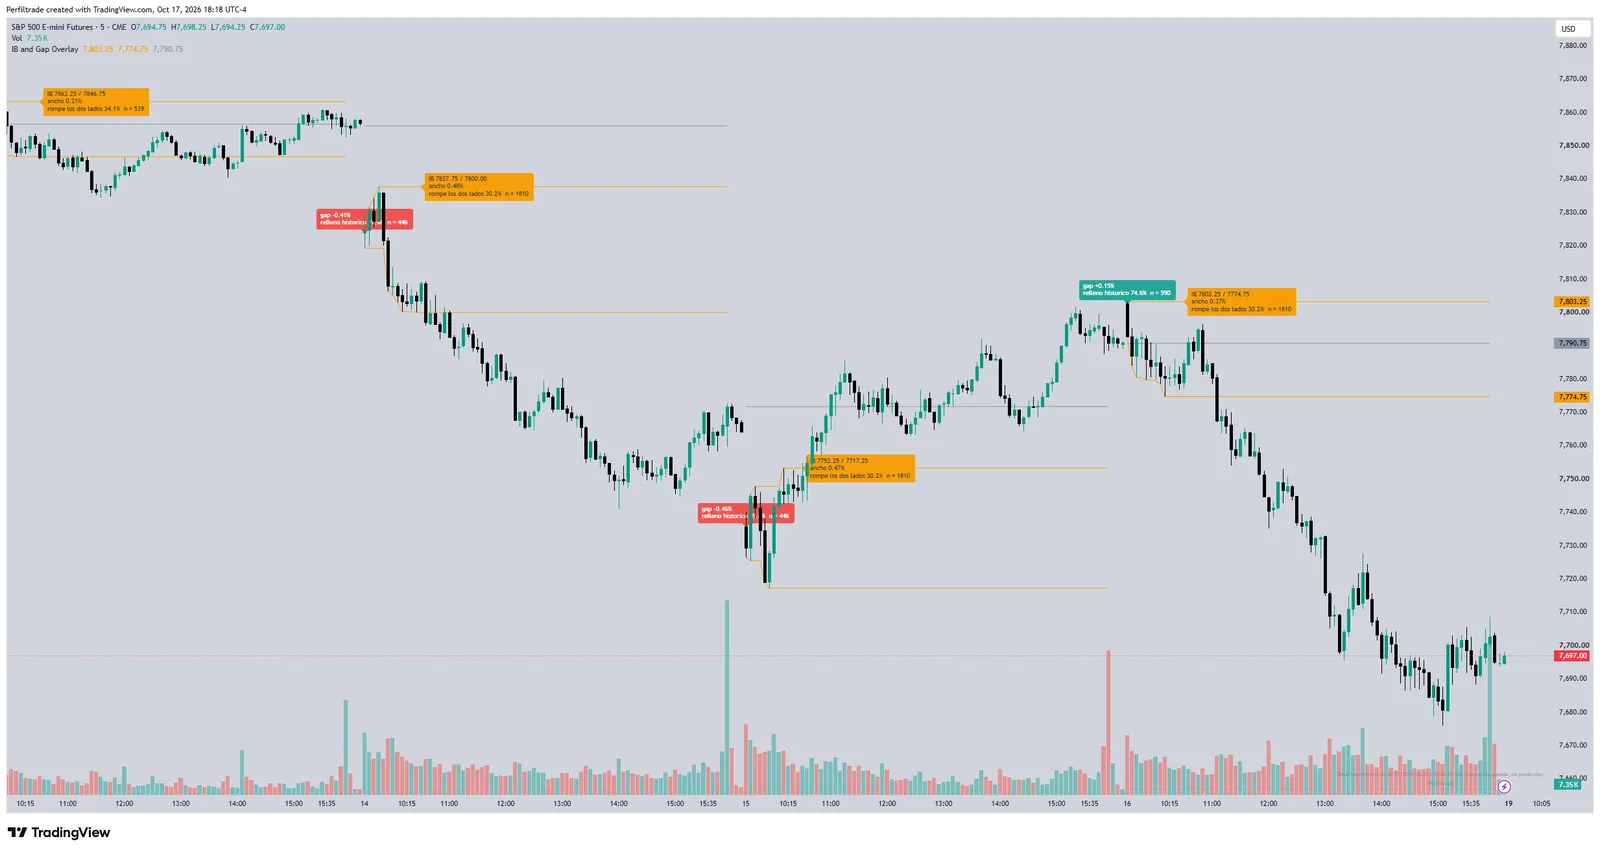
Next to the gap, how often one of that size and direction filled, with its n.
How to cite this data
The tables on this page are our own work, built from historical futures data. You may reproduce them, translate them or build on them, including commercially, as long as you credit the source and link back to the original page. If you use them, tell us: we like knowing what they get used for.
Licence: CC BY 4.0
Suggested citation:
Perfiltrade (October 12, 2026). Do Streaks Exist? Daily Continuation Across 30 Futures and 115,233 Sessions. https://www.perfiltrade.com/en/learn/daily-streaks-thirty-futures
Try these concepts with real data
14 days free, no card. An analysis tool, not investment advice.
See plans →